
A standard insurance policy is designed to protect the average home, yet your property and lifestyle are anything but average. When your assets exceed typical market thresholds, relying on a generic provider often means accepting restrictive fine print that can lead to rejected claims and significant financial exposure. You deserve better than an automated call centre when trying to value a unique art collection or a bespoke jewellery set. This is why high net worth home insurance is no longer just a luxury; it’s a vital necessity for those with rebuilding costs typically starting from £750,000.
We understand the frustration of feeling like just another number in a database. You want the certainty that your home is fully protected by a policy that reflects your specific risk profile and lifestyle. This 2026 guide shows you how to secure tailored property protection that goes far beyond standard market limits, even as premiums are projected to rise by 8% across the industry this year. We’ll examine how to eliminate the anxiety of claim denials, the benefits of working with a dedicated expert, and the proactive steps you can take to safeguard your legacy with total confidence.
Key Takeaways
- Understand why high net worth home insurance offers a customised contract that removes the restrictive warranties typically found in standard, off-the-shelf policies.
- Learn how to distinguish between market value and unique rebuild costs to prevent the risk of being underinsured in an escalating 2026 property market.
- Gain total peace of mind through “Agreed Value” settlements, which eliminate disputes over item worth and ensure you receive the full value of your assets if you need to claim.
- Follow a structured, room-by-room approach to inventorying your contents, ensuring every piece of fine art and jewellery is documented with clinical precision.
- Discover the advantage of using an independent broker to access specialist syndicates and unlisted markets that provide more robust security than generic direct insurers.
What is High Net Worth Home Insurance and Why Does it Matter?
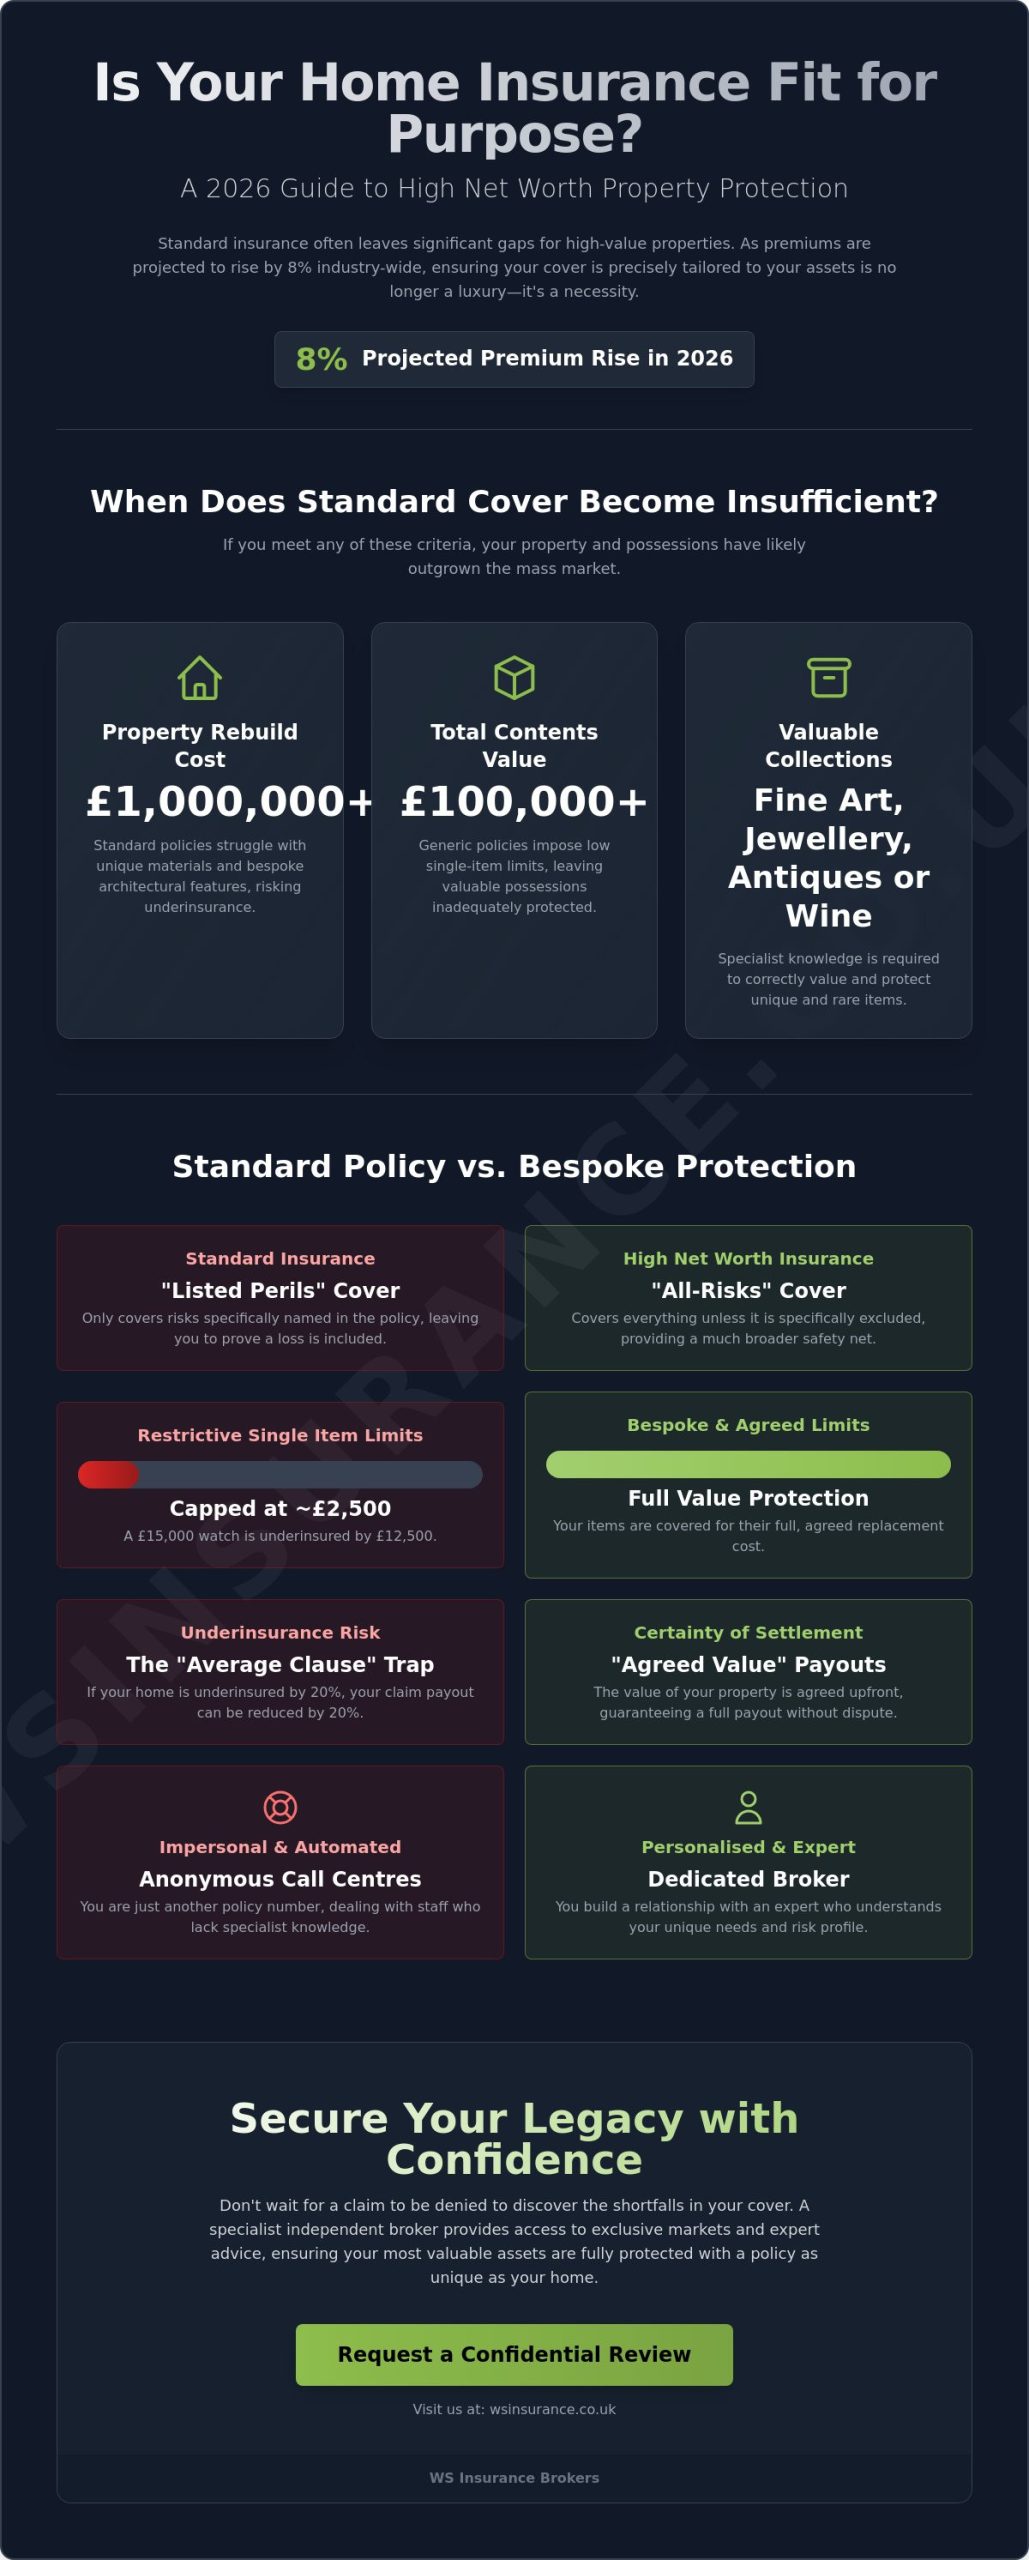
High net worth home insurance represents a fundamental shift in how your most valuable assets are protected. Unlike standard home insurance policies, which are built on rigid, standardised templates for the mass market, HNW cover is a customised contract. It’s designed specifically for properties and lifestyles that fall outside the “average” risk profile. This isn’t just about higher limits; it’s about a different philosophy of protection called “all-risks” cover. While a basic policy lists what is covered, a high-value contract covers everything unless it’s specifically excluded. This creates a safety net that removes the uncertainty often found in cheaper, off-the-shelf products.
The transition from mass-market coverage to a bespoke policy is often psychological. It marks the moment you stop viewing insurance as a commodity and start seeing it as a shield for your legacy. Standard policies often fail when handling complex claims because they lack the flexibility to account for unique architectural features or rare materials. A specialist provider acts as a steady hand, offering a consultative approach that prioritises your long-term security over a simple transaction. By choosing high net worth home insurance, you’re securing a partnership with experts who understand the nuances of luxury assets.
The Limitations of Standard Home Insurance
Standard policies often contain restrictive single-item limits, frequently capping jewellery or art at just £2,500 per item. If you own a watch worth £15,000, you’re effectively uninsured for the difference. Even more concerning is the “average clause” trap. If you underinsure your home by 20%, the insurer can legally reduce your claim payout by 20%, even for a partial loss. We also see strict security warranties in basic policies. These clauses can invalidate your entire claim if you forget to set the alarm on the one night a burglary occurs. A bespoke policy eliminates these traps, providing clarity during the claims process.
Defining the High Net Worth Threshold in 2026
In the 2026 market, the entry point for specialist cover has shifted due to rising construction costs and inflation. We typically see properties with a rebuild value exceeding £1,000,000 requiring high net worth home insurance to ensure full protection. However, the building’s value is only half the story. If your total contents exceed £100,000, or if you possess significant collections of fine art, antiques, or jewellery, you’ve likely outgrown the standard market. These lifestyle indicators suggest a level of complexity that requires a dedicated expert. Your risk profile is unique, and your policy should reflect that precision.
Identifying Your Need: When Standard Cover Becomes Insufficient
Beyond the physical structure, your lifestyle often dictates the need for specialized coverage for high-value homes. If you employ domestic staff like housekeepers or gardeners, you have specific legal obligations regarding Employers Liability that basic policies might not adequately address. Similarly, high-frequency travel or niche hobbies involving expensive equipment require a policy that provides worldwide protection without the restrictive “away from home” limits found in mass-market products. We act as a shield, ensuring your daily life is protected from the complexities of the broader insurance market.
Hidden assets often represent the largest area of vulnerability for wealthy homeowners. A climate-controlled wine cellar or a designer wardrobe can easily hold £50,000 in value, yet these are frequently overlooked during standard applications. If you’re unsure whether your current arrangements provide sufficient security, a consultation with our team can help you identify potential gaps in your cover and restore total peace of mind.
High-Value Contents and Single Item Limits
Standard policies typically impose a “specified item” limit, often capped at £2,500. This means a single engagement ring or a high-end watch could be significantly underinsured from the moment you sign the contract. Opting for high value jewellery insurance ensures these items are protected for their true replacement value. Crucially, bespoke high net worth home insurance wording includes “pairs and sets” clauses. If one earring from a pair is lost, the insurer pays for the replacement of the entire set, rather than just the missing half.
Specialist Buildings: Listed Status and Non-Standard Construction
Owning a Grade I or Grade II listed building carries heavy legal responsibilities. You’re legally required to restore the property using period-accurate materials and methods, which are exponentially more expensive than modern alternatives. Specialist materials like thatch, local stone, or bespoke glass require niche underwriting that standard providers simply don’t offer. Should a major loss occur, high-value policies provide enhanced “Alternative Accommodation” cover. This ensures your family’s lifestyle is maintained in a comparable property during the lengthy, complex repair process required for historic homes. Understanding the full scope of your obligations is essential, and our guide to listed building home insurance explains how to secure the right specialist heritage protection whilst remaining compliant with conservation law.
Core Benefits of a Bespoke HNW Insurance Policy
Choosing a bespoke policy provides a level of certainty that standard products simply cannot match. One of the most significant advantages is the provision of “Agreed Value” settlements. In the event of a total loss, the insurer pays the exact amount specified in your policy schedule, removing any clinical disputes over an item’s worth at the time of the claim. This transparency ensures you aren’t left haggling over the value of a cherished heirloom or a unique piece of furniture during an already stressful period. It’s a methodical approach to protection that eliminates doubt from the outset.
Many clients find the removal of restrictive warranties to be the most reassuring feature of high net worth home insurance. Standard policies often contain “condition precedents” that can invalidate your cover for minor oversights, such as failing to activate a specific alarm zone before leaving the house. Bespoke wording is typically warranty-free, meaning your protection remains intact even if human error occurs. Navigating the HNW insurance market requires understanding these subtle but vital differences in contract law that act as a shield for your assets. You also receive full accidental damage cover as standard, providing a safety net for both your building’s fabric and your high-value contents without the need for expensive add-ons.
Worldwide Cover and Lifestyle Protection
Your lifestyle isn’t confined to your postcode, and your insurance shouldn’t be either. Bespoke policies provide worldwide protection for your possessions as standard, ensuring your jewellery and technology are covered whilst you travel. This extends to family members, such as students living away at university, whose belongings remain protected under your primary policy. We also include specific extensions for unique lifestyle risks. Whether it’s “hole-in-one” cover for a golf tournament, marquee hire for a garden party, or event cancellation protection, the policy is built to reflect your specific behaviour and interests.
Liability Protection for the Modern Household
Managing a large estate often involves a complex network of domestic staff and social responsibilities. High net worth home insurance includes robust Employers’ Liability cover for gardeners, nannies, and housekeepers, protecting you against claims for injury or illness. Public liability cover is similarly enhanced to account for unique land features or large-scale entertaining. For those who contribute to their community, we provide Director and Officers (D&O) liability. This protects your personal assets if you face legal action whilst serving on a charity board or a residents’ association, ensuring your philanthropic efforts don’t create unnecessary financial risk.
Essential Considerations When Buying HNW Insurance
Once the structure is accounted for, you should conduct a room-by-room inventory of your contents. This diligent exercise ensures that every piece of technology, bespoke furniture, and designer item is documented. Following this, a thorough review of your physical security is essential. Aligning your locks, alarms, and safes with insurer standards not only validates your cover but often leads to more favourable terms. Finally, engaging an independent broker allows you to access the niche market where these tailored contracts are negotiated. This partnership acts as a shield between you and the complexities of the broader market.
Accurate Valuations and Professional Appraisals
A common pitfall for many homeowners is relying on “index linking” to adjust their sums insured annually. Whilst this accounts for general inflation, it often fails for unique heritage properties or rare collections where values fluctuate independently of the mass market. We recommend a professional re-appraisal of jewellery and fine art every three to five years to ensure your prestige home insurance remains accurate. These appraisals provide the documented evidence required to support an “Agreed Value” settlement, removing any ambiguity during the claims process.
Security Requirements and Risk Management
Insurers for high-value properties typically maintain specific “minimum security standards” that exceed those of the standard market. This often includes requirements for Grade 3 or 4 monitored alarm systems featuring “dual-path” signalling, which ensures the signal reaches the monitoring centre even if a phone line is cut. Proactive risk management is becoming increasingly sophisticated. Integrating smart home technology, such as water leak sensors and remotely monitored CCTV, acts as an additional layer of security for your property. These measures don’t just reduce the likelihood of a claim; they demonstrate to underwriters that you are a diligent risk, which can result in significant premium savings. If you would like a professional review of your current arrangements, you can contact our expert team today for a confidential consultation.
Navigating the Market: Why an Independent Broker is Your Best Asset
Navigating the market for high net worth home insurance requires a steady hand and a deep understanding of the global underwriting landscape. Direct insurers, whilst often reputable, are restricted by their own internal risk appetites and limited product sets. They can only offer you the specific solutions they have on the shelf, which may not align with your unique requirements. An independent broker like WS Insurance acts as a seasoned professional, standing between you and the complexities of the market to ensure your interests always remain the priority. We provide a single point of contact for all your requirements, removing the frustration of generic call centres and impersonal automated systems.
The fundamental difference lies in our autonomy and lack of bias. Whilst a direct insurer represents their own bottom line, an independent broker is fiercely loyal to the client. We search the entire breadth of the market to find the most robust security for your assets, acting as a trusted advisor who understands the clinical precision required for high-value protection. This partnership directly results in your ease and confidence, as we handle the proactive labour of market analysis whilst you enjoy the resulting benefit of comprehensive, tailored cover. Our role is to eliminate doubt at every stage of the selection process.
Accessing the Unlisted Market and Niche Underwriters
Comparison sites are designed for the masses; they cannot handle the nuances of a Grade II listed manor or a private art gallery. Many of the most robust high net worth home insurance policies exist within the unlisted market, accessible only through specialist high net worth insurance brokers who maintain relationships with syndicates at Lloyd’s of London. This access allows us to negotiate bespoke terms for non-standard risks that a standard underwriter would simply reject. For those with complex estates, we can consolidate your UK and overseas properties into a single, cohesive portfolio policy. This structure simplifies your administration and ensures no gaps in your security exist across your global assets.
The Value of Personal Advocacy and Claims Support
The true value of a broker is most visible during the claims process. We act as your personal advocate, providing professional representation that removes the clinical stress of negotiating with loss adjusters. Our advice is transparent and prioritises your long-term security over insurer profits. As your lifestyle evolves, whether through new acquisitions or changes in domestic staff, we remain your expert guide, adjusting your protection to mirror your changing risk profile. This ongoing consultative approach ensures your policy remains a perfect fit for your lifestyle, providing the permanent removal of uncertainty regarding your most cherished possessions.
Securing Your Legacy with Total Confidence
Protecting a high-value estate requires more than just a generic policy; it demands a strategic partnership built on precision and transparency. Clarity is your greatest asset. High net worth home insurance removes the restrictive warranties of the mass market, replacing them with “Agreed Value” settlements and “all-risks” protection that mirrors your specific lifestyle. By prioritising professional rebuild assessments and room-by-room inventories, you eliminate the anxiety of underinsurance and ensure your most cherished assets are shielded from the complexities of the broader market.
As an independent and FCA regulated broker, we provide access to the entire UK market, including specialist syndicates that don’t appear on comparison sites. Our role is to act as your steady hand. We offer dedicated personal claims advocacy and a single point of contact for all your security needs. We invite you to speak with a specialist broker at WS Insurance to organise your bespoke cover and experience the peace of mind that comes from a truly tailored solution. Your property is unique, and it deserves protection that is equally exceptional.
Frequently Asked Questions
What is the difference between high net worth and standard home insurance?
High net worth insurance provides “all-risks” protection whereas standard policies usually only cover “defined perils” like fire or theft. Standard contracts often include restrictive warranties that can invalidate a claim for a minor oversight. In contrast, high net worth home insurance is a bespoke contract designed to remove these traps and provide significantly higher limits for unique assets.
How much does high net worth home insurance cost in the UK?
The cost of your premium depends entirely on your property’s rebuild value, the total value of your contents, and your specific risk profile. Whilst mass-market policies focus on the lowest price, HNW cover is priced to reflect the comprehensive nature of the protection and the quality of the claims service. Working with a broker allows you to access competitive pricing from specialist syndicates that don’t appear on comparison sites.
Do I need a professional valuation for my jewellery and art?
Professional valuations are vital for ensuring you receive an “Agreed Value” settlement in the event of a total loss. Without a recent appraisal, usually conducted every three to five years, you may find it difficult to prove the true worth of a rare piece of art or a unique jewellery set. This diligent approach ensures your sums insured remain accurate in a fluctuating market and removes any clinical disputes during a claim.
What is a single item limit and how does it affect my cover?
A single item limit is the maximum amount an insurer will pay for an individual item that hasn’t been specifically listed on the policy. Standard policies often cap this at £2,500, which is frequently insufficient for luxury goods. A high-value policy offers significantly higher limits or allows you to specify items to ensure they are covered for their full replacement value without any ambiguity.
Can I include my holiday home on a high net worth policy?
You can absolutely include holiday homes and overseas properties within a single high net worth home insurance portfolio policy. Consolidating your assets this way simplifies your administration and ensures consistent levels of protection across all your residences. It also allows your broker to negotiate better terms by viewing your total risk as a single, managed portfolio rather than separate, disconnected risks.
What security measures are required for high-value home insurance?
Insurers typically require minimum security standards such as Grade 3 or 4 monitored alarm systems with dual-path signalling. You may also need specific locks on all entry points and an approved safe for jewellery exceeding a certain value. These measures act as a shield for your home and can lead to more favourable premium rates by demonstrating a proactive approach to risk management.
Does high net worth insurance cover accidental damage as standard?
Accidental damage cover is almost always included as standard in high net worth policies for both buildings and contents. Standard policies often treat this as an expensive add-on with various exclusions. In the HNW market, the “all-risks” philosophy means you’re protected against most forms of accidental loss or damage unless the event is specifically excluded in the contract wording.
Why should I use a broker instead of a comparison site for HNW insurance?
Brokers provide access to unlisted markets and specialist underwriters, such as those at Lloyd’s of London, who don’t engage with comparison sites. A broker acts as your personal advocate during the claims process, ensuring your interests are prioritised over insurer profits. This human-centric approach provides a level of expert guidance and tailored contract negotiation that automated platforms simply cannot replicate.