
Would you trust a standard policy to cover a bespoke jewellery collection when the average homeowner’s premium reached £1,952 in December 2025, a figure calculated for mass-market risks rather than your specific assets? For those with properties where the rebuild cost exceeds £750,000, relying on off-the-shelf cover often leads to a painful discovery during a claim: restrictive single-item limits and inadequate valuations that fail to reflect the true cost of specialist materials. Choosing prestige home insurance isn’t just about higher limits; it’s about securing bespoke protection that adapts to your lifestyle without the guesswork.
We agree that your property is unique, particularly if it carries a listed status or involves non-standard construction that standard insurers simply don’t grasp. You shouldn’t have to settle for frustrating automated call centres or policies that leave your global assets exposed. This article will show you how to arrange comprehensive protection that offers a dedicated point of contact and genuinely fits your requirements. We will explore the essential steps to avoiding common underinsurance pitfalls and ensuring your high-value assets receive the expert care they deserve throughout 2026.
Key Takeaways
- Understand why standard policies often trigger the “Average Clause” and how this can significantly reduce your claim payout if your property is underinsured.
- Discover how “Agreed Value” coverage ensures you receive a fair, pre-determined settlement for unique assets rather than a depreciated market value.
- Learn how to secure comprehensive worldwide protection for your possessions, ensuring your jewellery and watches are covered whilst you travel.
- Find out why professional rebuild cost assessments are vital for non-standard or listed buildings to ensure your property protection is accurate and reliable.
- Explore how an independent broker grants you access to exclusive markets for prestige home insurance, providing a dedicated point of contact for all claims.
What is Prestige Home Insurance and Why Does it Matter?
Prestige home insurance isn’t merely a more expensive version of a standard policy; it’s a fundamental shift in how assets are valued and protected. Whilst a basic policy might suffice for a typical suburban semi, it often leaves owners of high-value properties exposed to significant financial loss. This bespoke insurance solution is designed for properties and contents that exceed standard market thresholds, providing a level of security that mass-market products cannot match. It’s a consultative approach to protection that replaces rigid algorithms with expert underwriting.
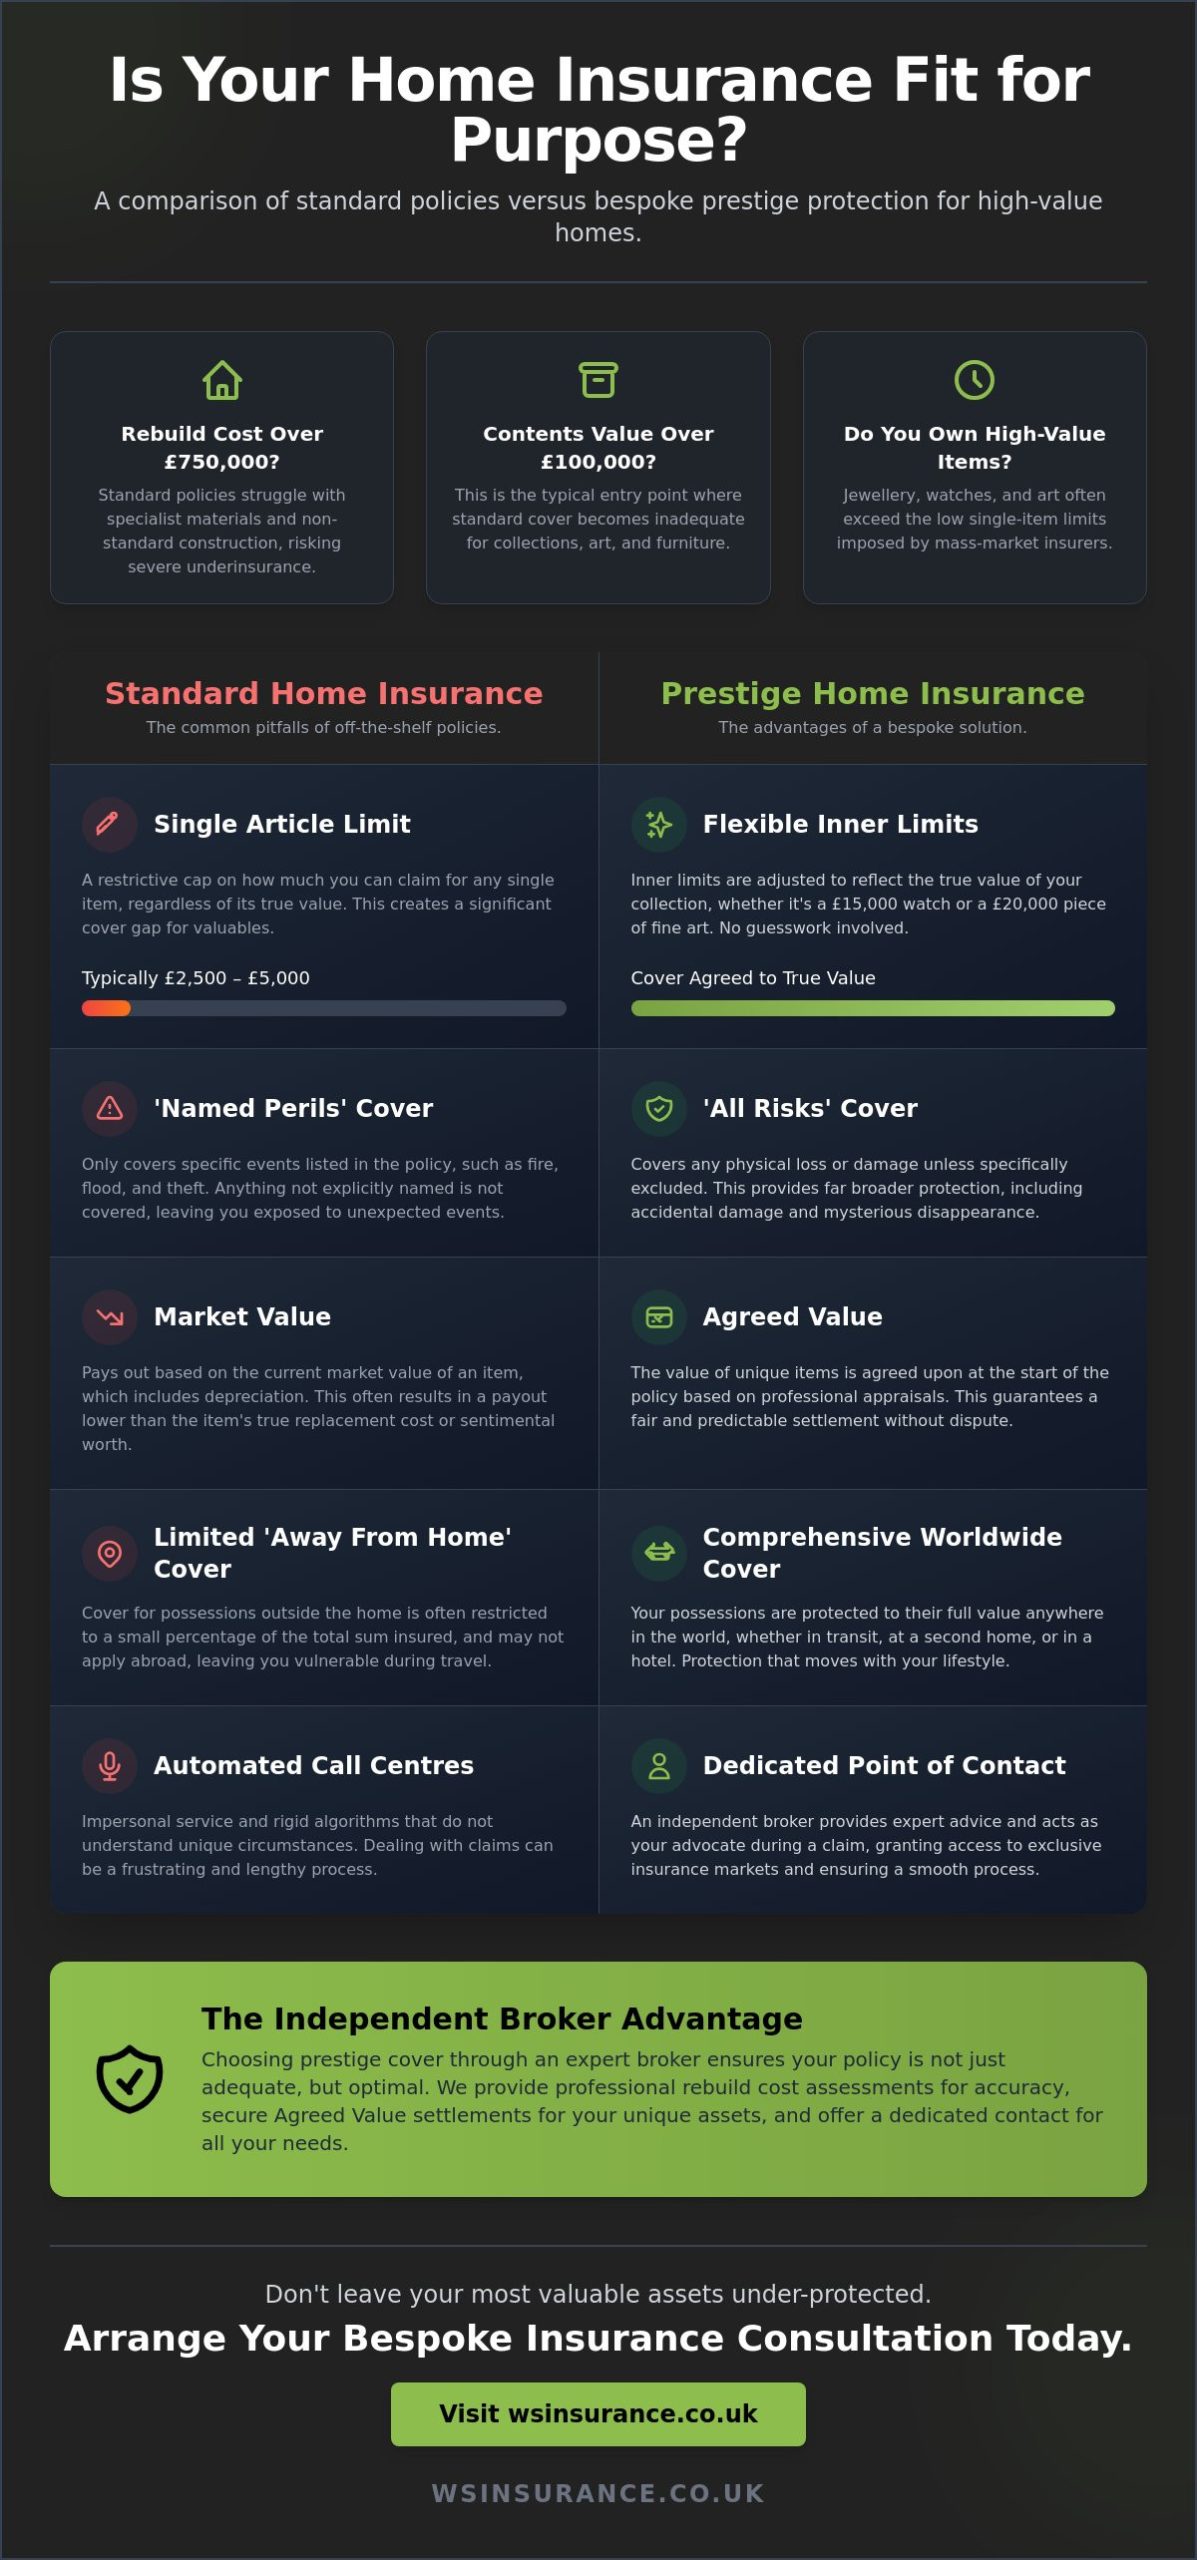
In the UK market, the £100,000 contents threshold is the typical entry point for prestige cover. Once your possessions, including furniture, electronics, and clothing, exceed this value, the risks become too complex for automated systems. A core feature of these policies is ‘All Risks’ cover. Unlike standard home insurance policies that often only cover ‘named perils’ like fire or theft, ‘All Risks’ protection covers any physical loss or damage unless it is specifically excluded. This ensures that accidental damage or the mysterious disappearance of items is handled with the precision your lifestyle requires.
Prestige vs. Standard Home Insurance
The primary failure of standard insurance lies in its rigid ‘sum insured’ limits. Most basic policies have a ‘single article limit’ for valuables, often capped at £2,500 or £5,000. If you own a watch worth £15,000 or a piece of fine art valued at £20,000, these caps create a dangerous gap in your financial security. Prestige policies offer flexible ‘inner limits’ that can be adjusted to reflect the true value of your collection. Prestige home insurance serves as a tailored safety net for complex estates, ensuring that high-value assets are protected without the restrictive caps found in mass-market products.
The Concept of ‘Bespoke’ Protection
A ‘one size fits all’ approach leads to dangerous gaps in your protection, particularly if your life involves multiple properties or frequent international travel. Prestige home insurance is built around your specific lifestyle, often including automatic cover for second homes or possessions whilst you are abroad. This level of detail requires a specialist underwriter to assess unique risks, such as the maintenance requirements of a Grade II listed building or the security needs of a remote estate. We take the time to understand these nuances, arranging cover that genuinely fits your world without the guesswork of a standard application form.
The Essential Components of a Prestige Home Policy
Another pillar of high-end protection is the distinction between Agreed Value and Market Value. For unique items or antiques, market value is often a poor reflection of true worth; it can fluctuate or include depreciation. By contrast, an Agreed Value policy locks in a valuation based on professional appraisals at the start of the term. This ensures you receive a fair, predictable payout without the stress of negotiation during a claim. When researching the best high-value home insurance companies, look for those that offer extended replacement cost. This feature covers the cost of rebuilding your home even if the price of specialist materials or labour exceeds your initial sum insured, a vital safeguard given that UK construction costs rose by approximately 4% in 2025.
Finally, these policies offer enhanced protection for legal expenses and identity theft. High-net-worth individuals are often targets for complex legal disputes or sophisticated fraud. Prestige policies provide significantly higher limits for legal representation, ensuring you have the resources to defend your reputation and assets without draining your personal capital.
Protecting Fine Art, Antiques, and Jewellery
Protecting Fine Art, Antiques, and Jewellery requires more than just a higher limit. Prestige policies include ‘pairs and sets’ clauses; if one earring is lost, the insurer pays for the replacement of the entire set to ensure the value is maintained. You also benefit from automatic cover for new acquisitions, typically for 30 to 60 days, giving you time to inform your broker after an auction or purchase. For those acquiring artwork, defective title cover provides essential protection if it’s later discovered the seller didn’t have the legal right to sell the piece. If you own a significant collection, understanding the full scope of high value jewellery insurance is essential to ensuring each piece is adequately protected. If you are unsure if your current arrangements meet these standards, you can speak to our experts to review your existing schedule.
Liability and Domestic Staff Protection
Liability and Domestic Staff Protection are often overlooked until a crisis occurs. High-limit public liability cover, often reaching £10m or £20m, is standard for clients who may face larger litigation risks. If you employ domestic staff like gardeners, housekeepers, or nannies, your prestige home insurance must include employers’ liability to meet UK legal requirements. Many specialist wordings also extend to more personal risks, such as kidnap and ransom or carjacking, providing a holistic safety net that goes far beyond bricks and mortar.
Why Standard Home Insurance Often Fails High-Net-Worth Clients
Standard home insurance is built for the mass market, relying on high-volume automation and simplified risk profiles. Whilst this works for a typical semi-detached house, it creates significant friction for high-net-worth individuals whose assets don’t fit into a pre-defined box. One of the most dangerous elements of a standard policy is the ‘Average Clause’. If your property is insured for £1m but the true rebuild cost is £2m, you are 50% underinsured. In the event of a £100,000 claim for a kitchen fire, a standard insurer will only pay £50,000, leaving you to find the remaining balance yourself. Prestige home insurance removes this risk by providing accurate valuations and avoiding these proportional reductions.
Security requirements are another area where standard policies often prove too rigid. Mass-market insurers might insist on specific window locks or alarm grades that are physically impossible to install on a Grade II listed property without breaching planning laws. Failure to meet these strict ‘warranties’ can void your cover entirely. By contrast, prestige policies are often ‘warranty-free’. They focus on the overall security of the estate rather than technicalities that could lead to a declined claim. This human-led approach avoids the ‘Computer Says No’ problem, where automated systems reject complex risks because they don’t meet a generic checklist. When looking for the best high-value home insurance companies, the ability to bypass these automated hurdles is often the most valuable feature.
The Underinsurance Crisis in the UK
Current industry data suggests that approximately 80% of high-net-worth homes in the UK are underinsured. This crisis has been exacerbated by the volatile economic conditions of 2026, where specialist construction costs have continued to rise. If your rebuild valuation is more than three years old, it’s likely outdated. We act as your trusted advisor, identifying these hidden vulnerabilities before a loss occurs. By arranging prestige home insurance that includes a professional appraisal, we ensure your protection keeps pace with inflation and rising material costs without the guesswork of online estimators. For a comprehensive overview of how tailored cover addresses these risks, our high net worth home insurance guide for 2026 sets out the full picture of bespoke property protection available to you.
Claims Handling: Reassurance vs. Resistance
The true value of a policy is only revealed at the point of a claim. Standard insurers typically appoint ‘loss adjusters’ whose primary role is to manage the insurer’s costs and minimise the payout. Prestige insurers operate differently, often providing a dedicated claims manager or allowing you to appoint a ‘loss assessor’ to act on your behalf. Perhaps most importantly, these policies offer a ‘choice of repairer’. If your home requires specialist stonemasonry or bespoke joinery, you aren’t forced to use the insurer’s high-volume, budget contractors. You have the freedom to hire the craftsmen who understand the unique requirements of your property.
Navigating the Valuation Process: Ensuring Accurate Cover
Securing prestige home insurance requires a methodical approach to data gathering that goes far beyond a standard online questionnaire. We replace the guesswork of self-estimation with a structured four-step process designed to eliminate the risk of underinsurance. This diligence ensures that if the worst happens, your financial recovery is total and undisputed. Accurate protection begins with a clear understanding of what you truly own and what it would cost to replicate in today’s market.
- Step 1: Professional Rebuild Cost Assessment (RCA). We facilitate a detailed inspection of your main dwelling to determine the exact cost of reconstruction, including debris removal and professional fees.
- Step 2: Specialist Valuations for Valuables. We work with independent experts to catalogue and value jewellery, watches, and fine art, ensuring each item is documented with its specific characteristics and current replacement value. For a deeper understanding of how bespoke cover works for your collection, our guide to high value jewellery insurance explains the key protections available.
- Step 3: Assessing Outbuildings and Leisure Facilities. Your protection must extend to annexes, swimming pools, tennis courts, and equestrian facilities, which often require separate consideration from the main house.
- Step 4: Implementing Index-Linking. We apply a mechanism that automatically adjusts your sum insured throughout the policy term to keep pace with the rising costs of specialist labour and materials.
The Importance of Professional Valuations
A common pitfall for high-net-worth individuals is confusing market value with rebuild cost. Whilst market value fluctuates based on postcode and school catchments, your insurance rebuild cost is strictly tied to the price of raw materials and specialist labour. We recommend updating your valuations every 3 to 5 years to reflect changes in the economic climate. For the main structure, we utilise surveyors accredited by the Royal Institution of Chartered Surveyors (RICS) to provide an RCA that stands up to the most rigorous insurer scrutiny. This authoritative data acts as a shield, preventing insurers from applying the average clause during a claim.
Index-Linking and Future-Proofing
Prestige policies are designed to be dynamic. They automatically adjust for inflation, ensuring that a policy written in January remains adequate in December, even if material costs spike unexpectedly. This is particularly vital for protecting against ‘demand surge’, a phenomenon where local construction prices skyrocket following a major event like a storm or flood. Index-linking removes the guesswork from annual renewals by ensuring your cover remains relevant to real-world costs. To ensure your property is valued with clinical precision, request a professional valuation review from our expert team.
The Independent Broker Advantage: Why WS Insurance?
Choosing a direct-to-consumer platform often means sacrificing choice for the sake of a digital interface. Whilst these portals offer speed, they can only sell their own restricted products, leaving you without an impartial comparison of the wider market. We operate differently. As an independent broker, we have whole-of-market access to exclusive ‘broker-only’ markets that standard comparison sites simply cannot reach. WS Insurance Brokers works for you, not the insurance company, acting as a diligent shield between your assets and the complexities of the market.
Whole-of-Market Access Without the Guesswork
We take the time to understand your specific needs, comparing various specialist high-net-worth underwriters and Managing General Agents (MGAs) to find the most robust wording. This independent approach allows us to negotiate bespoke terms that standard algorithms would reject. We also organise your various requirements into a single, manageable portfolio. This consolidates multiple properties and high-value vehicles under one renewal date, removing the administrative burden and providing clarity across your entire estate. Our “No Extra Cost vs Direct” approach ensures you receive expert advice and bespoke prestige home insurance without paying a premium for the privilege.
Claims advocacy is where our partnership proves its true value. If you experience a loss, we don’t leave you to deal with an automated call centre or a clinical loss adjuster. We act as your expert advocate, managing the process from first notification to final settlement. We ensure the insurer honours the spirit of the bespoke wording we arranged, fighting for a fair outcome so you don’t have to. This level of support is included as standard, providing a consultative atmosphere that prioritises your security over the transaction itself.
A Steady Hand in Complex Times
With over 25 years of broking expertise, we have seen the market evolve and understand how to navigate its volatility. We provide a steady hand, offering professional, reassuring advice that removes the anxiety from the protection process. You will always have a dedicated, human point of contact who understands your history and your assets. This personal connection is the hallmark of a Trusted Advisor, ensuring you receive honest guidance that genuinely fits your world. Secure your prestige home insurance quote with WS Insurance Brokers and experience the peace of mind that comes from expert, independent advocacy.
Securing Your Legacy with Precision and Care
Your home and assets represent a significant lifetime achievement; protecting them shouldn’t be left to a generic algorithm. We’ve explored how prestige home insurance replaces standard market limitations with bespoke wording, such as “Agreed Value” settlements and “All Risks” global cover. By prioritising professional RICS-accredited valuations, you eliminate the guesswork that leads to underinsurance in a volatile economic climate where construction costs rose by 4% in 2025.
As an FCA Authorised and Regulated broker with 25+ years of independent broking expertise, we provide access to exclusive high-net-worth underwriters. We act as your dedicated advocate, ensuring that your protection is as unique as the property it covers. Our whole-of-market status means we work for you, not the insurer, providing a steady hand through complex claims and annual renewals.
Request a Tailored Prestige Home Insurance Review today to ensure your assets are fully protected for 2026 and beyond. We’re here to help you secure your peace of mind with cover that genuinely fits.
Frequently Asked Questions
Is prestige home insurance significantly more expensive than standard cover?
Not necessarily, as the value lies in the breadth of protection rather than just the premium. Standard policies often require multiple expensive add-ons for high-value items or travel, which can quickly inflate the total cost. By consolidating these into one bespoke package, prestige policies often provide a more cost-effective solution for homes with rebuild values exceeding £750,000.
What is the minimum sum insured required for a prestige policy?
Most specialist underwriters set a minimum contents threshold of £100,000 to qualify for this level of cover. This entry point ensures the policy is tailored for those with significant assets that require “All Risks” wording. For buildings, a rebuild cost of £750,000 or more is the typical benchmark for moving away from mass-market products.
Does prestige home insurance cover second homes or holiday lets?
Yes, prestige policies are designed to accommodate multiple properties under a single, manageable portfolio. This includes second homes in the UK or overseas residences. Unlike standard policies that have strict unoccupancy clauses, often limited to 30 days, prestige wording offers more flexibility for properties that aren’t your primary residence throughout the year.
Do I need a professional valuation for every item of jewellery?
You only need individual valuations for items that exceed the policy’s specified “unspecified item limit,” which is often £5,000 or £10,000. For pieces above this value, a professional appraisal from the last 3 years is recommended. This ensures you benefit from “Agreed Value” protection, removing the guesswork and ensuring a fair payout if you need to claim.
Can prestige insurance cover my home office and business equipment?
Yes, most high-end wordings include significant limits for home office equipment, such as computers and professional furniture, as standard. If your home-based business involves high-value stock or frequent client visits, we can arrange specific extensions. This ensures your professional assets are as well-protected as your personal possessions without needing a separate commercial policy.
What happens if I underinsure my home by mistake?
Underinsurance typically triggers the “Average Clause,” which reduces your claim payout by the same percentage you are underinsured. If you are 25% underinsured, you’d only receive 75% of any claim value. However, many prestige home insurance policies waive this clause if you’ve had a professional valuation within the last 3 years, providing a vital financial safety net.
How does the claims process differ with a prestige insurance broker?
The process is defined by personal advocacy rather than automated call centres. We act as your dedicated point of contact, managing the dialogue with the insurer to ensure a fair outcome. You often have access to specialist loss assessors who prioritise restoring your property to its original standard rather than simply finding the cheapest repair route.
Does prestige insurance include cover for listed buildings?
Yes, specialist protection for Grade I, II*, and II listed buildings is a core component of prestige home insurance. Standard insurers often struggle with these risks due to the high cost of heritage materials and specialist craftsmanship. Prestige underwriters understand these requirements, ensuring your rebuild cost accurately reflects the legal obligations of owning a historic property.