
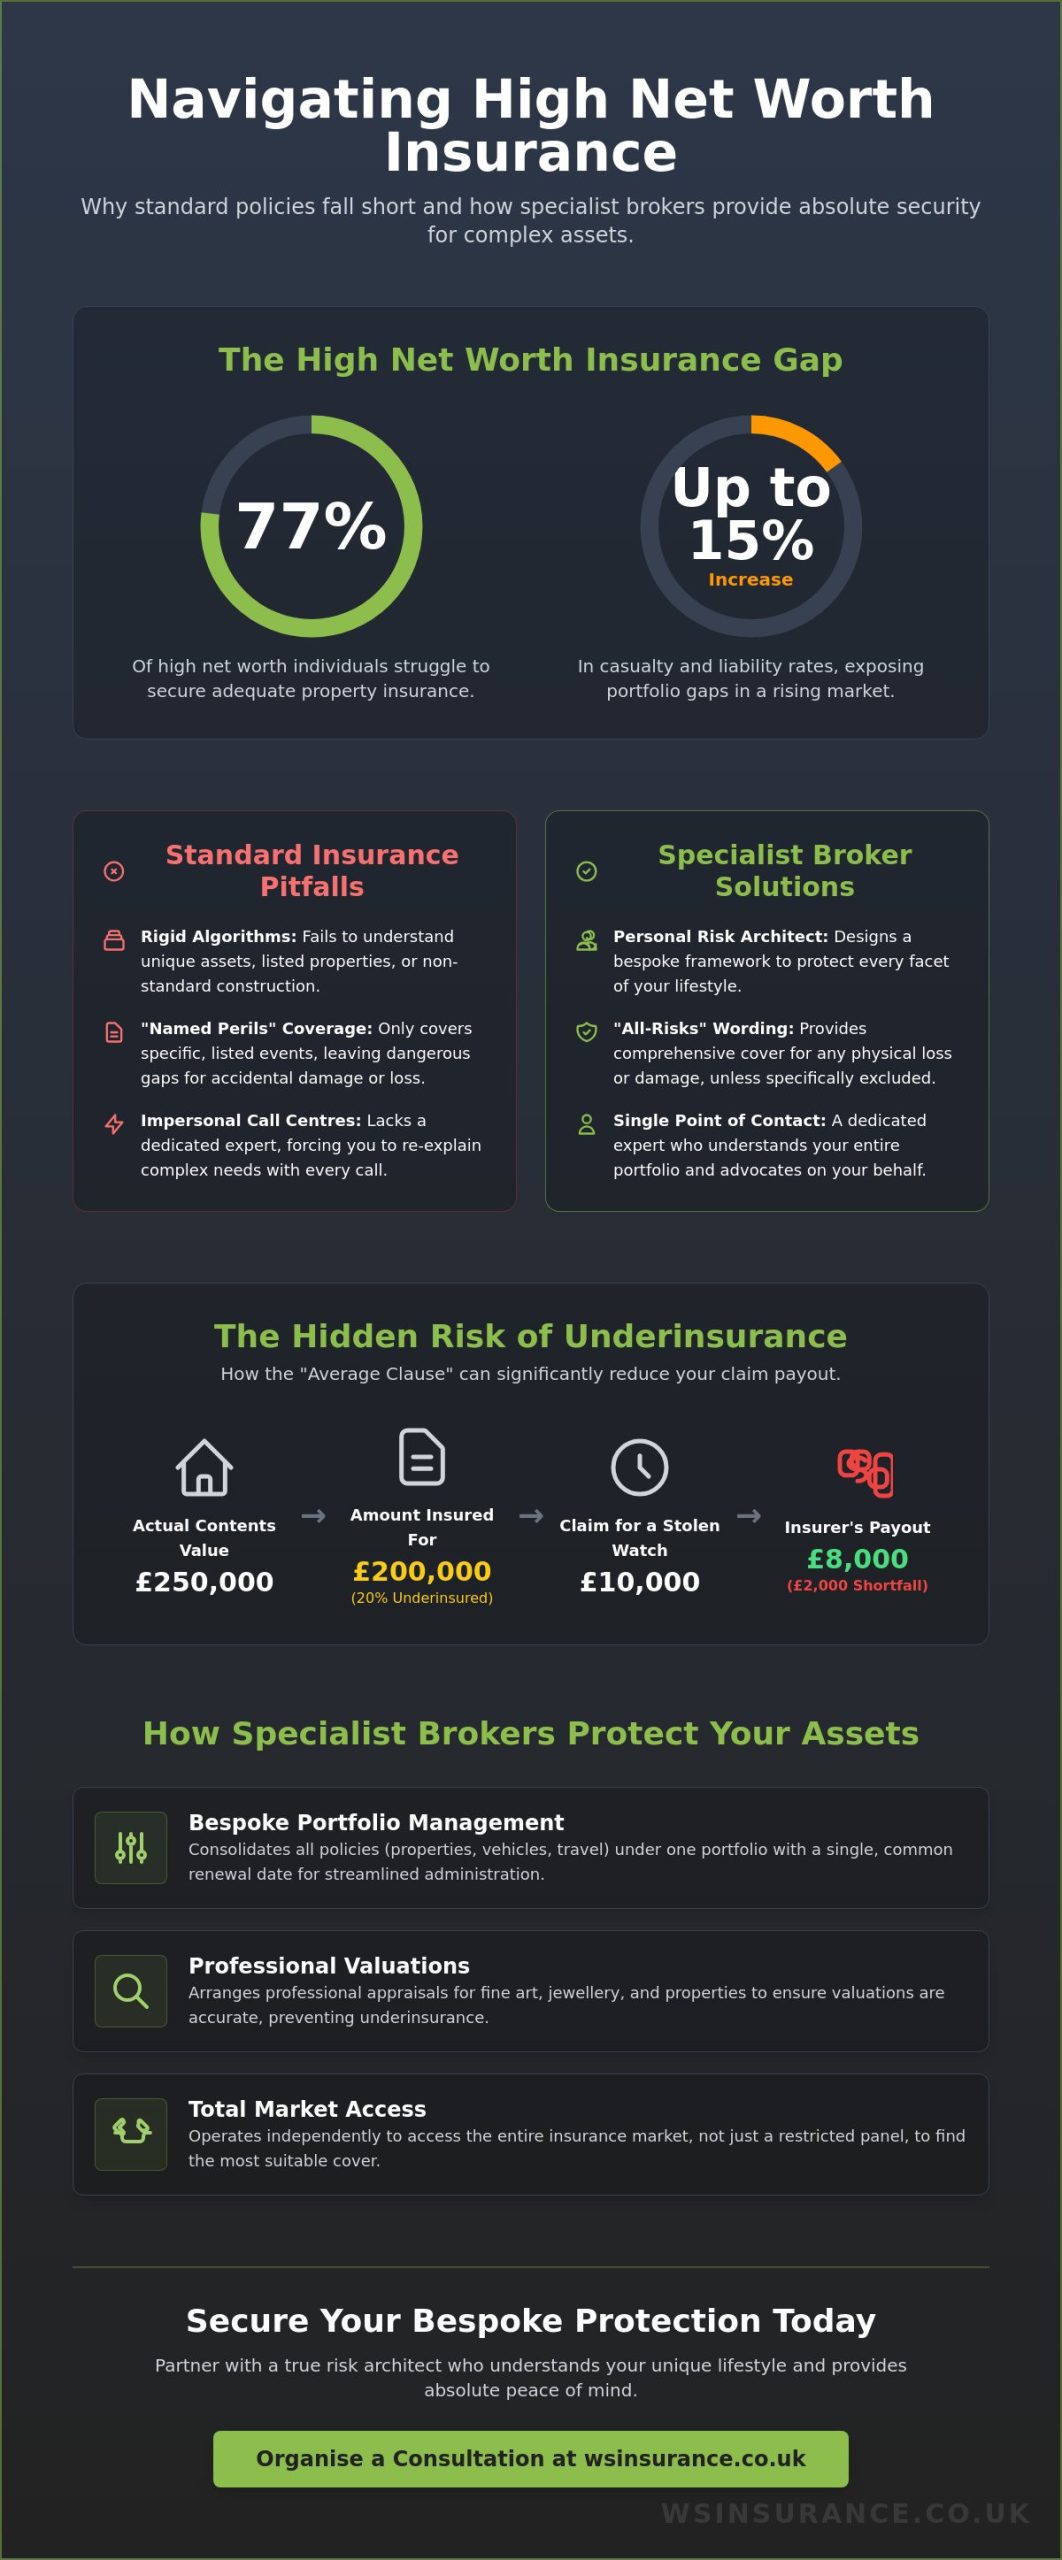
Did you know that 77% of high net worth individuals currently struggle to secure adequate property insurance? This startling figure highlights a growing disconnect between standard market offerings and the intricate realities of a complex asset portfolio. When your lifestyle involves high-value estates, fine art, and international motor collections, the generic “online quote” box isn’t just frustrating; it’s a significant financial risk. Selecting the right high net worth insurance brokers is no longer about simply finding a policy. It’s about appointing a risk architect who understands that your requirements don’t fit a standard mould.
You’ve likely felt the irritation of explaining your unique circumstances to an impersonal call centre or worried that a simple valuation error could leave you underinsured. We understand that you require more than a transaction; you need a steady hand to navigate a bifurcated market where casualty and liability rates are rising by up to 15%. This guide will show you how to identify a broker who provides a single point of contact and bespoke “all-risks” wording tailored to your specific needs. We’ll explore the essential criteria for choosing a partner who prioritises proactive risk management over simple renewals, ensuring your security remains absolute.
Key Takeaways
- Understand why standard automated algorithms fail to protect complex assets and how “average clauses” can trigger significant financial shortfalls.
- Discover how specialist high net worth insurance brokers act as risk architects to secure bespoke policy wording and professional valuations for your most precious items.
- Identify the non-negotiable criteria for evaluating a broker, focusing on their ability to access the entire market rather than a restricted panel of providers.
- Learn how to organise a robust asset register and physical security measures to ensure a seamless and accurate consultation process.
- Gain clarity on the benefits of a single point of contact for your entire portfolio, replacing impersonal call centres with a dedicated, expert guide.
Why Standard Insurance Provision Fails High-Value Lifestyles
Standard insurance providers rely on rigid algorithms designed for the mass market. These automated systems thrive on predictability and uniformity, which is exactly why they fail to protect complex estates. If you are a High-net-worth individual (HNWI), your portfolio likely includes unique assets that don’t fit into a “standard” risk category. High net worth insurance brokers recognise that a square peg cannot be forced into a round hole. Whilst a standard policy might cover basic risks, it often lacks the flexibility to account for non-standard construction or the specific heritage requirements of a listed property. This lack of adaptability creates dangerous gaps in your security.
The distinction between “named perils” and “all-risks” coverage is often the difference between a successful claim and a devastating loss. Mass-market policies typically operate on a named peril basis, meaning you are only covered for specific events like fire or theft. Specialist protection, however, flips this logic on its head. It provides coverage for any physical loss or damage unless a specific exclusion is mentioned. This covers accidental damage to fine art or the loss of a bespoke piece of jewellery whilst travelling, gaps that standard wording frequently leaves wide open.
The Limitations of Price Comparison Sites
Comparison websites are built for speed, not precision. They cannot accurately value a collection of antiques or account for the professional liability risks faced by modern executives. These platforms lack the depth to offer prestige home insurance that includes personal cyber protection or reputation management. Without a broker’s intervention, you’re left with a generic product that treats your unique assets as commodities. Automated platforms simply don’t have the capacity to handle the nuances of a high-value lifestyle.
The Hidden Risks of Underinsurance
Underinsurance is a silent threat that only reveals itself at the point of claim. Many standard policies include an “Average Clause”, a technical term with severe consequences. If you insure your contents for £200,000 but the actual value is £250,000, you are underinsured by 20%. In the event of a claim, the insurer may only pay out 80% of the loss; this applies even if you are only claiming for a single stolen watch. This risk is particularly acute in 2026, as the impact of rising material costs and specialist heritage labour continues to outpace standard index-linking for those requiring listed building home insurance. Specialist high net worth insurance brokers prevent this by arranging professional appraisals, ensuring your valuations remain accurate and your protection remains absolute.
The Essential Services Provided by Specialist High Net Worth Brokers
A specialist broker does not simply sell a product; they provide a comprehensive protective framework. High net worth insurance brokers act as your personal risk architects, ensuring that every facet of your lifestyle is shielded from uncertainty. Unlike standard providers who leave you to navigate complex claims alone, a specialist broker serves as your dedicated advocate amongst insurers and loss adjusters. They possess the industry tenure to negotiate bespoke policy wording that standard algorithms cannot replicate, ensuring that “all-risks” coverage truly means all risks. This consultative approach transforms insurance from a grudging necessity into a strategic asset.
Bespoke Portfolio Management
Managing multiple properties and a collection of prestige vehicles often leads to an administrative burden that high-value individuals simply don’t have time for. Specialist high net worth insurance brokers alleviate this by consolidating your various policies into a single portfolio with a “Common Renewal Date”. This ensures you have one point of contact and one annual review rather than a constant stream of renewals. Whether you are acquiring a new holiday home or adding to a motor fleet, your broker manages the mid-term adjustments with clinical precision. This level of service is essential for streamlining high net worth home insurance across global portfolios, allowing you to focus on your lifestyle whilst we handle the complexities of the market.
Expert Valuation and Risk Assessment
Accurate valuations are the cornerstone of any robust insurance programme. Because market values for precious metals and gemstones fluctuate, high value jewellery insurance requires regular, professional appraisals to prevent the “Average Clause” penalties discussed previously. Your broker will arrange for independent experts to assess your art, jewellery, and antiques, ensuring that “New for Old” coverage applies accurately to irreplaceable items. Beyond valuations, they provide proactive advice on physical risk management. Whilst 70% of high-net-worth individuals conduct risk reviews, only 55% find them to be effective. A specialist broker bridges this gap by identifying “hidden” threats such as escape of water in large estates or recommending sophisticated leak-detection systems and fire prevention measures. By investing in these proactive labours now, you prevent the heartache of a claim later. If you value this level of meticulous care, you might consider how WS Insurance Brokers can tailor a protective strategy for your unique assets.
Ultimately, the value of a specialist lies in their ability to act as a shield. They anticipate risks before they manifest and provide a steady hand when the unexpected occurs. This partnership ensures that your legacy and lifestyle are preserved with the highest degree of integrity and transparency.
Evaluating High Net Worth Insurance Brokers: Key Criteria for 2026
Selecting a partner to protect your legacy requires more than a cursory glance at a website. It demands a rigorous evaluation of their professional standing and market reach. High net worth insurance brokers should act as a shield between you and the complexities of the global market. To ensure you’re receiving the highest standard of care, you must look beyond the glossy brochure and examine the underlying structure of the brokerage. This process removes uncertainty and ensures your assets are managed with clinical precision.
Market Access and Insurer Relationships
Composite insurers, the familiar names on the high street, are designed for the masses. They often lack the technical appetite for complex estates or high-value collections. In contrast, specialist HNW underwriters and Lloyds of London syndicates offer the depth of coverage required for truly bespoke protection. A broker with extensive industry tenure will have cultivated long-standing relationships with these niche providers. These connections are vital; they often lead to more favourable terms and provide the leverage needed to settle “grey area” claims where standard wording might be ambiguous. Your broker’s ability to access the entire breadth of the market is a badge of honour that distinguishes them from restricted competitors.
Access to the entire market is non-negotiable. Some firms operate on restricted panels, meaning they only offer products from a handful of insurers. This limitation can leave you with a policy that is “close enough” rather than “exact.” True independence ensures your broker is fiercely loyal to you, not the provider. Look for firms with Chartered status and FCA regulation. These accreditations serve as a badge of honour, signifying a commitment to ethical practice and clinical precision in every transaction. It’s about finding a steady hand in a complex market.
Personal Accessibility and Claims
Personal accessibility is the hallmark of a premier service. You deserve a dedicated client executive who understands the nuances of your portfolio, not a rotating cast of operators in a call centre. This single point of contact removes anxiety from the process and ensures that your risk management strategy remains consistent. When things go wrong, you need a broker with a proven claims handling reputation. Verify this by asking for case studies or testimonials that demonstrate their performance amongst loss adjusters during complex settlements. High net worth insurance brokers who prioritise direct communication channels offer a level of personal accessibility that large, automated corporations simply cannot replicate.
Transparency and Fee Structures
Transparency in remuneration is the foundation of long-term trust. Whether a broker operates on a commission-based or fee-based model, they should provide a clear, structured breakdown of all professional charges. This eliminates doubt and ensures that the advice you receive is based on your security rather than the broker’s bottom line. A transparent pricing model serves as a pragmatic justification for the high level of service provided. It builds a narrative of partnership where the broker’s proactive labour directly results in your ease and confidence.
How to Organise Your Portfolio for a Broker Consultation
Approaching a consultation with high net worth insurance brokers is the first step in transforming a fragmented collection of policies into a cohesive protective framework. It is a collaborative exercise in precision that moves beyond simply providing a list of addresses. By arriving at your consultation with a structured overview of your assets, you enable your broker to conduct a thorough gap analysis of your current policy schedules. This proactive labour ensures that no stone is left unturned and that your resulting protection is as seamless as it is robust. A well-organised portfolio allows your advisor to act as a shield, identifying potential vulnerabilities before they manifest as claims.
Your broker will need to understand the nuances of your daily life to provide accurate advice. This includes identifying “lifestyle risks” that standard applications often overlook, such as the employment of domestic staff, frequent international travel, or the hosting of large-scale events at your primary residence. Documenting your previous claims history is also vital, as it allows your broker to identify patterns and suggest risk mitigation strategies that could lead to more favourable terms amongst specialist insurers. To begin building your bespoke protective framework, you can contact our specialist advisors today for a confidential review.
The Asset Inventory Checklist
Creating a comprehensive asset register is essential for ensuring that every item is accounted for at its true market value. This register should span from property rebuild costs to niche collections such as fine wine or rare stamps. Categorising your possessions helps distinguish between “General Contents” and “High-Value Specified Items” that require individual listing on your policy. We recommend taking high-resolution photographs of all specified items to maintain a secure digital record for your asset register. This level of detail is particularly important for jewellery and watches, where market fluctuations in 2026 demand regular appraisal updates to avoid underinsurance. For a structured approach to this process, our home insurance high value items protection checklist provides a comprehensive framework for identifying and valuing your most prized possessions.
Security and Lifestyle Assessment
Physical security measures are a primary consideration for underwriters when assessing high-value risks. You should document all existing protections, including NSI-approved intruder alarms, five-lever mortice deadlocks, and the presence of high-grade safes. If you own secondary residences or offer holiday lets, these must be disclosed to ensure the correct liability protections are in place. Furthermore, if you are planning any “Contract Works” or significant renovations, discussing these with your high net worth insurance brokers early is non-negotiable. Major building works alter the risk profile of a property and require specialist oversight to ensure your coverage remains valid throughout the project duration.
Bespoke Protection: Partnering with WS Insurance Brokers
Choosing the right partner to shield your assets is a decision that requires both clinical precision and a relationship built on absolute trust. WS Insurance Brokers operates as a steady hand in a complex market, combining the extensive reach of a national firm with the meticulous, personal touch of a boutique brokerage. Our primary objective is to remove the anxiety often associated with protecting multifaceted asset portfolios. As high net worth insurance brokers, we prioritise your long-term security over the immediate transaction, providing a consultative atmosphere where your needs are heard and understood.
Our independence remains a badge of honour that distinguishes us from restricted competitors. We aren’t bound to a limited panel of providers; instead, we maintain access to the entire breadth of the UK specialist market. This autonomy ensures that our loyalty remains fiercely with you, allowing us to act as a protective shield between your lifestyle and the broader market’s complexities. By choosing a partner with such extensive industry tenure, you gain a seasoned guide who remains accessible, human, and dedicated to your peace of mind.
The WS Insurance Claims Guarantee
The true test of a broker occurs at the point of a claim, where the difference between a generic policy and bespoke protection becomes starkly apparent. We manage the entire process with clinical precision, acting as your representative amongst loss adjusters to ensure a fair and swift settlement. Our commitment to transparency and integrity removes the uncertainty that often surrounds high-value claims, providing you with a narrative of partnership throughout the process. We act as fierce advocates for the client’s interests rather than as agents of the insurance company.
Starting Your Journey to Better Protection
Your journey towards comprehensive security begins with a methodical consultation where we establish the underlying philosophy of your protective needs. We remove doubt by providing comparative value propositions regarding different pricing models and coverage levels, ensuring you have a pragmatic justification for every decision made. This structured approach concludes with a clear path to personal contact and a tailored policy placement that secures your legacy for the years ahead. If you’re ready to move away from impersonal call centres and towards precision-engineered security, contact WS Insurance Brokers today for a confidential review of your portfolio.
Securing Your Legacy with Absolute Precision
Protecting a high-value lifestyle requires a shift from transactional insurance to a partnership based on clinical precision. You’ve seen how standard automated systems often trigger the “Average Clause” and leave significant gaps in coverage for listed buildings or bespoke jewellery collections. By appointing specialist high net worth insurance brokers, you replace impersonal call centres with a dedicated expert guide who understands the nuances of your entire portfolio. This approach ensures that every asset is valued accurately and every risk is mitigated through proactive management rather than reactive claims.
As an FCA Authorised and Regulated firm, we offer independent access to the entire breadth of the UK and specialist insurance market. Our role as your trusted advisor includes dedicated claims advocacy; we act as your shield amongst loss adjusters to ensure your interests are always protected. Secure your assets with a bespoke review from WS Insurance Brokers to remove uncertainty from your insurance programme. We look forward to providing the steady hand and expert guidance your lifestyle deserves.
Frequently Asked Questions
What exactly qualifies as “High Net Worth” for insurance purposes?
High net worth individuals (HNWI) are typically defined as those holding at least $1 million in liquid financial assets. For insurance purposes, this classification often applies to households with property rebuilding costs exceeding £1 million or contents valuations starting at £100,000. Specialist high net worth insurance brokers use these thresholds to identify clients who require more sophisticated protection than standard mass-market policies can provide.
Can a high net worth broker cover my international properties as well?
Yes, specialist brokers can frequently arrange coverage for international residences within a consolidated portfolio. This allows you to manage UK estates and overseas holiday homes under a single management structure with a common renewal date. By using a single point of contact, you ensure that your global assets are protected with consistent wording and clinical precision across different jurisdictions.
How often should I have my jewellery and art professionally valued?
Professional valuations should generally be updated every three to five years to reflect current market trends. Because the value of precious metals, diamonds, and fine art can fluctuate significantly, more frequent reviews may be necessary during periods of high market volatility. Regular appraisals prevent the risk of underinsurance and ensure that “new for old” settlements remain accurate at the point of claim.
Is it more expensive to use a high net worth insurance broker?
Using a broker is a pragmatic investment that often results in better value than buying directly from a high-street brand. Whilst the level of service is premium, high net worth insurance brokers have access to the entire breadth of the market, including niche underwriters not available to the general public. This independence allows them to negotiate more favourable terms and comprehensive coverage that prevents costly shortfalls during a claim.
What is “All-Risks” cover and why is it better for luxury assets?
“All-Risks” cover is a superior form of protection that includes any physical loss or damage unless a specific exclusion is mentioned in the policy. Unlike standard policies that only cover “named perils” like fire or theft, all-risks wording protects you against accidental damage and loss. This is essential for luxury assets like fine art or bespoke jewellery that are frequently moved, displayed, or worn.
Can I include my prestige car collection on the same policy as my home?
Many specialist providers allow you to combine your prestige car collection and home insurance into a single, managed portfolio. This streamlines your administration by providing one renewal date and a single point of contact for all your private motor and property needs. It also ensures that your liability limits and service standards remain consistent across all your high-value assets.
What happens if I need to make a claim on a high-value item whilst abroad?
Most specialist high-net-worth policies provide worldwide coverage for your possessions, meaning you’re protected regardless of your location. If an incident occurs abroad, you simply contact your dedicated broker executive who will initiate the claims process on your behalf. They act as your shield amongst international loss adjusters, ensuring the settlement process remains transparent and efficient whilst you’re away.
Why do I need a broker if I can buy premium insurance from a big brand directly?
Direct brands often rely on restricted panels and rigid algorithms that cannot accommodate unique or complex risks. A broker acts as your “Expert Guide,” providing bespoke policy wording and independent access to the entire market, including Lloyds of London. Most importantly, a broker provides dedicated claims advocacy, representing your interests fiercely rather than prioritising the insurer’s bottom line.