
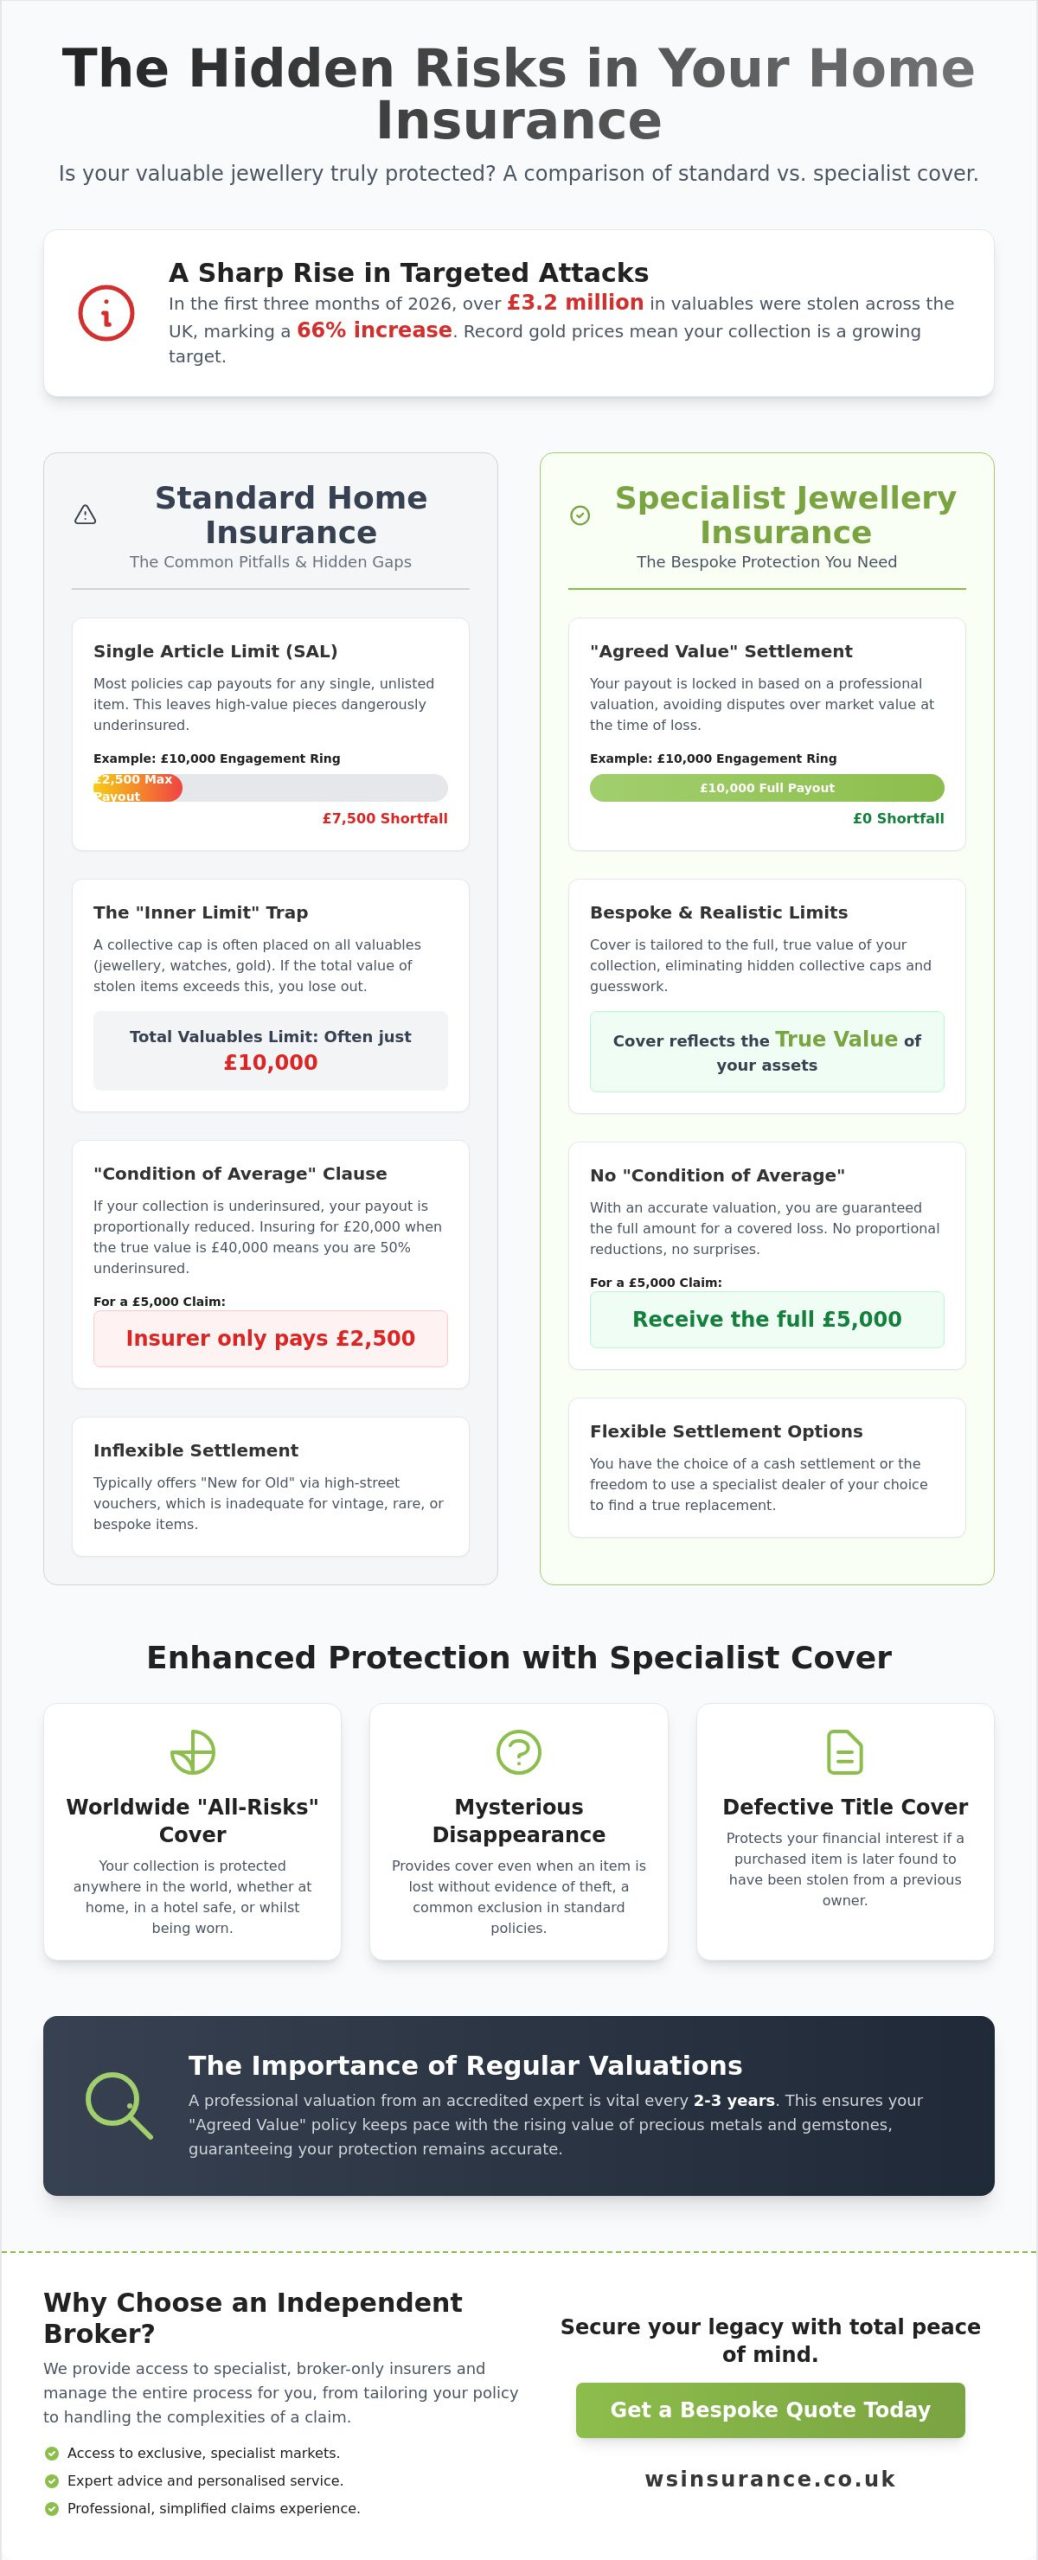
Did you know that in the first three months of 2026, over £3.2 million worth of valuables were stolen across the UK in a sharp 66% rise in targeted attacks? With gold prices reaching record highs this year, your most cherished possessions are likely worth far more than you realise. Most standard home insurance policies cap single-item payouts between £1,000 and £2,500, which leaves a dangerous gap for those who own fine pieces. If you’re relying on a basic policy, you may be facing the reality of underinsurance without even knowing it. This is why securing specialist high value jewellery insurance is no longer just an option for the few, but a necessity for anyone with a significant collection.
We understand that jewellery represents more than just financial capital; it’s a legacy of sentiment and history. This guide will show you how to secure your assets using bespoke protection that offers specialist cover tailored to your specific needs. You’ll learn the critical difference between “Agreed Value” and “Market Value,” why professional valuations are essential every two to three years, and how to ensure you have genuine worldwide cover for your travels. We’re here to help you protect your investment without the guesswork, providing a clear path to total peace of mind and a simplified, professional claims experience.
Key Takeaways
- Identify the critical gaps in standard home insurance that often leave expensive pieces underinsured due to restrictive single-article limits.
- Discover how high value jewellery insurance provides “Agreed Value” protection, ensuring your payout matches a professional valuation rather than fluctuating market rates.
- Learn about the advantages of “All-Risks” worldwide cover, which protects your collection whilst travelling without the typical limitations of standard policies.
- Understand why regular valuations from accredited professionals are vital for maintaining accurate protection as the value of precious metals and gemstones continues to rise.
- Explore how an independent broker provides access to specialist, broker-only markets and manages the complexities of the claims process for you.
The Limitations of Standard Home Insurance for High-Value Jewellery
Relying on a basic policy to protect a significant collection is a risk that often goes unnoticed until a claim is made. Many homeowners assume their Standard Home Insurance covers everything under their roof. In reality, these policies are designed for the “average” household and contain restrictive clauses that can leave luxury collections exposed. Most mass-market insurers apply a Single Article Limit (SAL), which is the maximum amount they’ll pay for any one item that hasn’t been specifically listed. This limit typically sits between £1,500 and £2,500. If your engagement ring is worth £10,000 and you haven’t declared it, you’ll likely face a £7,500 shortfall. This is why high value jewellery insurance is essential for those who’ve moved beyond the limits of standard protection.
Another overlooked danger is the “condition of average” clause. If you’ve underestimated the total value of your collection, insurers can reduce your payout proportionally. For instance, if you insure £20,000 worth of jewellery but the true replacement cost is £40,000, you are 50% underinsured. In the event of a £5,000 claim, the insurer may only pay £2,500. This punitive measure ensures the premium you pay matches the risk they take, but it leaves you carrying half the loss yourself. Standard policies also frequently exclude accidental loss away from the home unless you’ve paid for a specific “personal possessions” add-on, which often still carries low limits and restrictive “days away” conditions.
Understanding the “Inner Limit” Trap
Standard policies often feature an “inner limit” which acts as a collective cap on all “valuables.” In insurance terms, this category usually includes watches, gold, silver, furs, and even certain electronics. You might find a policy has a total valuables limit of £10,000. If a burglary occurs and £15,000 worth of jewellery and watches are stolen, you’ll lose £5,000 regardless of whether individual items were under the Single Article Limit. We work to remove this guesswork by arranging cover that reflects the true scale of your assets, ensuring you aren’t caught out by hidden caps.
The Problem with “New for Old” Settlements for Rare Items
Standard insurers typically settle claims using “New for Old” replacements or vouchers for high-street jewellers. Whilst this is fine for modern, mass-produced items, it’s entirely inadequate for vintage or discontinued luxury watches like a Rolex Submariner or a Patek Philippe. A high-street replacement isn’t a replacement at all if the item is irreplaceable or has unique aesthetic qualities. Specialist policies offer “Agreed Value” or cash settlement options. This allows you to source a genuine replacement from a specialist dealer rather than being forced into a high-street store that doesn’t understand the heritage of your collection.
Defining Bespoke Protection: Key Features of Specialist Jewellery Cover
Whilst we have explored the Limitations of Standard Home Insurance, bespoke protection offers a more robust framework designed for significant assets. Specialist high value jewellery insurance is not merely a policy with higher limits; it is a contract of precision that accounts for the unique nature of fine jewellery and watches. These policies include features that standard insurers often exclude, such as “mysterious disappearance.” This ensures that if an item is lost rather than stolen, your claim is still valid. Additionally, defective title cover protects your financial interest if a piece you purchased is later discovered to have been stolen from a previous owner, a risk that is particularly relevant for those who buy at auction or from private collectors.
The Power of “Agreed Value” Settlements
The most significant advantage of specialist cover is the “Agreed Value” settlement basis. Most standard policies pay out based on the market value at the time of the loss, which can lead to disputes if metal or gemstone prices have fluctuated since your last renewal. In contrast, an Agreed Value policy locks in a specific payout amount based on a professional valuation provided at the start of the policy. This eliminates the guesswork during a claim. For bespoke or commissioned pieces that cannot be easily replaced on the high street, this guarantee is essential. It ensures you receive the full sum required to recreate or replace the item to its exact original specifications. We can help you arrange a professional review of your collection to ensure your schedule reflects these guaranteed values.
Worldwide Protection for the Global Traveller
Evaluating Your Options: Standalone Policy vs High Net Worth Home Insurance
Choosing the right structure for your high value jewellery insurance is just as important as the level of cover itself. Most clients find themselves at a crossroads: do they insure specific pieces on a standalone basis or consolidate everything into a high net worth home insurance portfolio? The decision usually depends on the total value of your assets and how frequently you add to your collection. Whilst standalone cover is excellent for targeted protection, a HNW portfolio offers a level of administrative ease and breadth that mass-market policies simply can’t match. It’s about finding the fit that provides the most security with the least amount of daily friction.
When to Choose a Standalone Jewellery Policy
A standalone policy is often the most pragmatic choice when you want to protect a single, high-value asset without altering your existing household arrangements. This approach effectively ring-fences the item. If you need to make a claim for a lost stone or a damaged clasp, your main home insurance No Claims Bonus remains completely unaffected. These policies are also highly flexible for high-wear items such as luxury watches. Because these items are worn daily, they face a higher risk of accidental damage; standalone providers often have more nuanced terms that cater specifically to the mechanical vulnerabilities of prestige timepieces.
The Advantages of a High Net Worth (HNW) Portfolio
For those with diverse collections including jewellery, fine art, and even prestige vehicles, a HNW portfolio is frequently the superior option. These “Master” policies consolidate multiple risks under a single renewal date, removing the stress of managing various expiry dates throughout the year. One of the most significant benefits is “Pairs and Sets” cover. If you lose one earring from a £10,000 pair, a standard insurer might only pay for the single lost item. A HNW policy recognises that the remaining piece has lost its aesthetic and financial value as a set and will typically pay to replace the entire pair. To ensure these limits are accurate, we recommend following the guidance on Professional Valuations provided by the GIA.
HNW portfolios are designed for those whose needs exceed the scope of basic high value jewellery insurance, offering a comprehensive shield for your entire lifestyle. These policies often include a 60-day automatic cover window for new acquisitions. This means if you purchase a new piece at auction, it’s immediately protected before you’ve even called your broker. Beyond the financial payout, you gain access to specialist lifestyle services, such as home security consultations and private appraisal sessions. It’s a consultative approach that focuses on prevention as much as protection, ensuring your legacy is guarded by experts who understand the true value of what you own. If your home itself is a heritage property, you may also wish to explore listed building home insurance to ensure your property’s unique architectural features receive the same level of specialist protection as your collection.
Professional Valuations and Risk Management: Securing Your Collection
Securing high value jewellery insurance is a proactive step, but the protection is only as reliable as the data behind it. To avoid the heartbreak of a disputed claim, you must ensure your valuations come from a member of the Institute of Registered Valuers (IRV). A common mistake is using a “Resale Value” or “Probate Valuation” for insurance purposes. These figures are typically much lower as they reflect what an item might fetch in a forced sale or for tax assessment. An insurance valuation, however, focuses on the full retail replacement cost, ensuring you can walk into a jeweller and replace the item exactly as it was.
We recommend updating these documents every three to five years. Since 2024, the price of gold has seen significant volatility, and a valuation from 2020 is likely to leave you significantly underinsured today. By maintaining a regular schedule, you remove the guesswork from the process and ensure your cover remains genuine and accurate.
What a Professional Jewellery Valuation Must Include
A professional document must be more than a simple receipt. It should feature high-resolution photography and exhaustive technical descriptions covering the four Cs: carat, cut, colour, and clarity. The valuer will also analyse hallmarks and stone settings to confirm the piece’s integrity. Replacement Value for insurance purposes is the cost to replace an item with a new equivalent in the current retail market. This level of detail acts as a definitive blueprint for your collection, making the claims process smoother and more professional.
Security Requirements: Safes and Alarms
Insurers often set specific physical security conditions based on the total value of your collection. Central to this is the Eurograde safe rating system. Ratings run from Grade 0 to Grade 7, and each determines the maximum value of jewellery the insurer will allow to be stored inside. Generally, the “jewellery limit” is ten times the safe’s “cash rating.” For example, a Grade 1 safe with a £10,000 cash rating is typically suitable for up to £100,000 of jewellery. If your collection exceeds these thresholds, you’ll need to upgrade your hardware to maintain your protection.
You should also be aware of the “unworn jewellery” clause. This requires that any items not being worn must be kept in the locked safe. Simply leaving a necklace on a bedside table can invalidate a claim if a theft occurs. To further bolster your security and potentially lower your premiums, we suggest installing a monitored alarm system, such as DualCom or Digicom, which alerts a central station the moment a breach is detected. If you’re unsure if your current setup meets these standards, you can speak to our specialist team for a bespoke security review.
Choosing WS Insurance Brokers for Your High-Value Jewellery Protection
Selecting the right partner to manage your high value jewellery insurance is the final, most critical step in protecting your legacy. At WS Insurance Brokers, we operate as independent advocates. We aren’t tied to any single provider, which means we work exclusively for you, not the insurance company. We take the time to understand the specific nuances of your collection; then we search the whole of the market to arrange protection that genuinely fits your lifestyle. This consultative approach ensures that your assets are guarded by a policy designed for your needs rather than a generic, mass-market product.
Many of the most robust and flexible policies are not available on comparison websites or directly to the public. We provide our clients with exclusive access to “Broker Only” markets, including those from our panel of leading specialist insurers. These providers specialise in high-net-worth risks and are often the only ones capable of offering the “Agreed Value” and “All-Risks” wording essential for fine jewellery. By leveraging our established relationships with these underwriters, we can secure comprehensive terms that provide total peace of mind at every step.
If the worst happens and you need to make a claim, you won’t be left to deal with an impersonal, automated call centre. We provide dedicated claims advocacy as a standard part of our service. We handle the negotiations, manage the paperwork, and push for a fair settlement on your behalf. We act as a professional shield between you and the complexities of the insurance market, ensuring that the process is as simplified and stress-free as possible.
Our “Whole-of-Market” Independence
With over 25 years of broking expertise, our team has navigated every complexity the High Net Worth sector can present. We remove the guesswork from policy documents that are often dense with technical jargon and hidden exclusions. Our independent, whole-of-market status allows us to compare rates and wordings across the entire industry spectrum. This ensures you receive the most competitive pricing without ever compromising on the quality of your protection.
Getting a Tailored Quote
Every collection has its own history and requirements, which is why we favour a personal consultation over automated online forms. We’ll discuss your specific security arrangements, travel habits, and valuation frequency to build a bespoke risk profile. It’s important to remember that there is no extra cost for using our services compared to going direct; however, you gain the significant advantage of expert advice and a partnership built on genuine trust. We align your jewellery cover with your wider lifestyle needs, providing a seamless portfolio management service.
Speak to our specialist High Net Worth team today for a bespoke jewellery insurance review.
Secure Your Legacy with Expert Protection
Your collection represents a lifetime of achievement and sentiment; it deserves protection that reflects its true worth. We’ve explored how standard home policies often fall short with restrictive single-item limits and why an “Agreed Value” settlement is the only way to remove the guesswork from a claim. Whether you choose a standalone policy or a comprehensive High Net Worth portfolio, the key is to ensure your cover is as bespoke as the items themselves.
As an FCA Authorised and Regulated broker with over 25 years of expertise, WS Insurance Brokers provides the steady hand you need in a complex market. We offer independent advice and direct access to specialist high value jewellery insurance from world-class underwriters. We take the time to understand your needs and arrange tailored protection that genuinely fits your lifestyle.
Don’t leave your most precious assets to chance. Request a Bespoke Jewellery Insurance Review today to ensure your collection is fully protected for the future. We’re here to help you move forward with total peace of mind and the confidence that your assets are in expert hands.
Frequently Asked Questions
Is my jewellery covered for loss or theft outside of the UK?
Yes, provided your policy includes worldwide all-risks cover as a standard feature. While standard home insurance often limits overseas travel to 30 or 60 days per year, specialist high value jewellery insurance typically provides protection for 365 days a year across the globe. You must still adhere to security requirements; for example, many insurers insist that items are kept in a locked hotel safe when they are not being worn.
How often do I need to get my jewellery professionally valued for insurance?
You should arrange a professional valuation every three to five years to ensure your cover remains accurate. With gold prices reaching record highs throughout 2024 and 2025, an outdated valuation could leave you with a significant financial shortfall during a claim. Using an IRV-registered valuer ensures the document is legally robust and accepted by all major High Net Worth underwriters.
What is “Pairs and Sets” cover and why do I need it?
Pairs and sets cover ensures that if you lose one part of a matching set, the insurer pays to replace the entire collection. If you lose a single earring from a £5,000 pair, the remaining item loses its aesthetic and functional purpose. This specialist clause allows the insurer to take the remaining item and pay you the full £5,000 for a completely new pair.
Do I need to keep my jewellery in a safe to be covered?
Most insurers mandate that items exceeding a specific threshold, often £10,000, must be stored in a locked safe when they are not being worn. This is known as the “unworn jewellery” clause. It’s vital that your safe has the correct Eurograde rating to match the total value of your collection; otherwise, the insurer may reject a claim following a theft from the home.
Can I insure an engagement ring before I have proposed?
What happens if the market price of gold or diamonds increases significantly?
If prices spike suddenly, you may be underinsured unless your policy includes a “Market Appreciation” clause. Some specialist High Net Worth policies offer a buffer, paying up to 125% or 150% of the insured value if the market replacement cost has risen since your last valuation. This feature acts as a vital safety net in a volatile precious metals market.
Does jewellery insurance cover accidental damage, like a stone falling out?
Specialist policies provide comprehensive cover for accidental damage, including the loss of a stone from its setting. Standard insurers often dismiss a lost diamond as “wear and tear” or “gradual deterioration,” but bespoke protection recognises this as a sudden and unforeseen event. This ensures you can have the piece professionally repaired or the stone replaced without a complex dispute.
Will my home insurance premium go up if I make a claim on a standalone jewellery policy?
No, a claim on a standalone policy generally has no impact on your main home insurance No Claims Bonus. This is one of the primary advantages of ring-fencing your most valuable assets. It allows you to protect your jewellery collection independently, ensuring that a lost watch or ring doesn’t result in higher premiums for your entire household buildings and contents cover.