
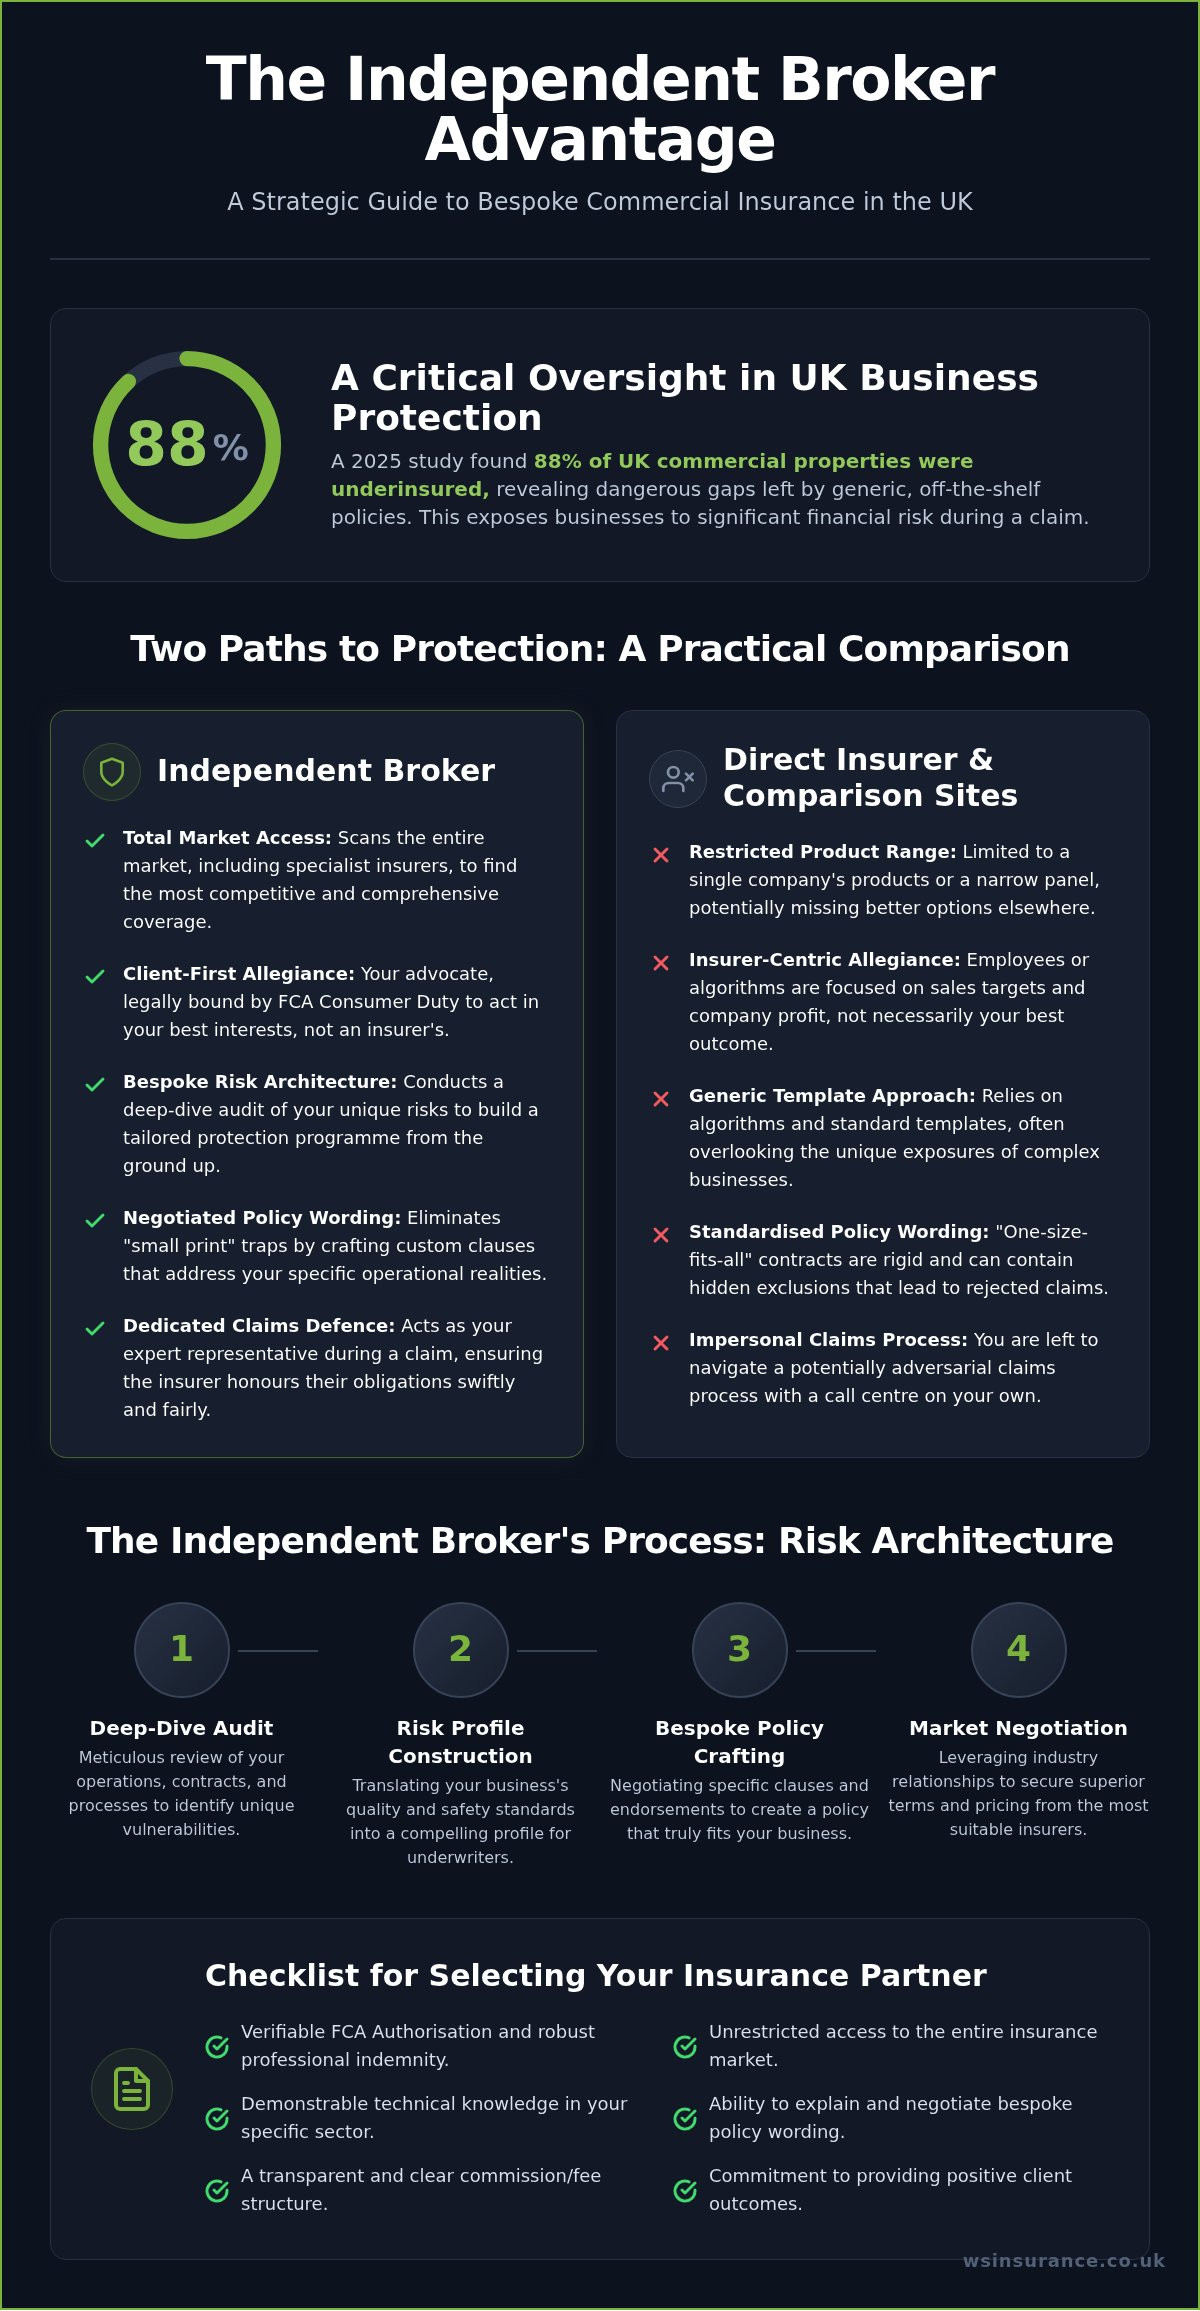
Did you know that 88% of UK commercial properties were found to be underinsured in a 2025 study by Charterfields? It’s a sobering statistic that reveals the dangerous gaps often left by generic, off-the-shelf policies. If you’ve felt the sting of rising premiums without clear justification or the frustration of impersonal service from automated call centres, you aren’t alone. Engaging a dedicated independent commercial insurance broker UK is the most effective way to move beyond standard templates. This partnership transforms insurance from a confusing overhead into a strategic asset that actually protects your bottom line.
You’ve worked hard to build your business, and you deserve a protection programme that reflects that effort. We’ll show you how to navigate the 2026 insurance market to secure superior coverage and unbiased advocacy. This guide explains the benefits of accessing the entire market for competitive rates, the impact of intensified FCA Consumer Duty standards on your service, and how a dedicated advisor removes the anxiety of “small print” exclusions. By the end, you’ll have a clear roadmap to bespoke business protection that leaves nothing to chance.
Key Takeaways
- Understand why partnering with an independent commercial insurance broker UK provides access to the entire market rather than being restricted to a single provider’s limited products.
- Discover the methodology of “risk architecture” and how a deep-dive assessment identifies unique exposures that standard policies often overlook.
- Learn why direct insurers and comparison sites often fail complex businesses by relying on generic data that can lead to gaps in your protection.
- Gain a practical checklist for evaluating potential partners, including how to verify FCA authorisation and assess sector-specific technical knowledge.
- Explore how bespoke policy wording eliminates the uncertainty of “small print” traps, ensuring your coverage acts as a reliable shield during a claim.
Defining the Role of an Independent Commercial Insurance Broker in the UK
An independent commercial insurance broker UK functions as your professional intermediary, bridging the gap between your specific business needs and the vast landscape of the British insurance market. Unlike “tied” agents who are contractually bound to a single provider, or direct insurers who only sell their own products, independent brokers operate with total autonomy. Their primary loyalty lies with you, the client, rather than the insurance company. This ensures that every recommendation is driven by your security requirements rather than corporate sales targets. An independent broker is a professional risk architect with access to the entire market, dedicated to designing a safety net that fits your unique operational profile.
The Legal and Regulatory Framework
Security is the foundation of any insurance partnership. In 2026, the Financial Conduct Authority (FCA) has intensified its supervision of the Consumer Duty, moving beyond simple compliance to actively testing whether brokers deliver positive outcomes for their clients. This regulatory environment ensures that an What is an Insurance Broker? is defined by their duty to provide clear, transparent advice. Quality brokers maintain robust professional indemnity insurance, which acts as a secondary shield for your business if professional advice ever falls short. Transparency regarding commissions and management fees is not just a preference; it’s a hallmark of a partner committed to integrity and long-term trust.
Why Independence Matters in 2026
The 2026 market presents a complex picture for UK business owners. Whilst general conditions are often described as a “soft market” with intense price competition, many sectors still face the pressure of rising premiums and stricter underwriting. Independence allows your broker to “cherry-pick” the most favourable terms from a vast panel of insurers, rather than forcing your business into a pre-packaged policy. This flexibility is vital for several reasons:
- Market Breadth: Accessing a wide panel ensures you aren’t missing out on specialist providers who don’t advertise to the general public.
- Bespoke Wording: Independent brokers can negotiate specific clauses that address your unique risks, avoiding the “small print” traps of standard contracts.
- Strategic Advocacy: In the event of a claim, your broker acts as your dedicated defender, using their industry standing to ensure the insurer meets their obligations.
The shift from buying insurance as a simple commodity to treating it as a strategic asset is now complete. In our post-digital landscape, the value of a human expert who understands your specific trade cannot be overstated. By choosing an independent commercial insurance broker UK, you’re securing a steady hand to guide you through market volatility with clarity and confidence.
The Strategic Advantage of Independent Risk Architecture
Risk architecture is the technical engine behind superior protection. It begins with a meticulous audit of your operational vulnerabilities, allowing an independent commercial insurance broker UK to construct a risk profile that commands respect from underwriters. Rather than simply requesting quotes, your broker acts as a translator. They frame your safety protocols and management standards in a language that insurers value, positioning your firm as a “preferred risk”. This proactive labour results in more than just lower premiums; it secures access to capacity that restricted agents simply cannot reach.
Generic, off-the-shelf policies frequently harbour “small print” traps. These exclusions often emerge at the worst possible moment: during a claim. Standard templates often fail to provide adequate business interruption cover or address niche liabilities, such as the 230% increase in cyber claim payouts seen recently in the UK market. By crafting bespoke policy wording, your broker removes these uncertainties. You gain a contract built for your specific reality, ensuring that the protection you pay for actually performs when tested. The FCA guidance for businesses provides a useful framework for understanding what you should expect from this professional relationship.
Bespoke Coverage for Specialist Industries
Sectors like recruitment, technology, and construction require more than a “one size fits all” approach. Tailoring business insurance for these industries involves sourcing “non-standard” cover from specialist markets. For instance, a technology firm might need specific intellectual property protection that a high-street insurer won’t touch. Similarly, an integrated commercial property insurance programme must account for complex rebuild costs and specialised equipment. If you’re concerned about gaps in your current arrangements, requesting a professional policy review can provide much-needed clarity.
Proactive Claims Advocacy
The true value of an independent partner becomes clear during a loss. Your broker acts as a shield between your business and the insurer’s claims department. Unlike automated call centres that follow rigid scripts, a dedicated advocate challenges insurer decisions and negotiates on your behalf. They understand the technicalities of the policy wording they helped create, which allows them to expedite settlements whilst you focus on running your operations. Having a dedicated independent commercial insurance broker UK in your corner ensures that you’re never just a policy number in a database; you’re a client with a powerful ally.
Independent Brokers vs. Direct Insurers: A Practical Comparison
Direct insurers operate as the sales arm of a single provider, which naturally limits your choice to their specific risk appetite and pricing. If your business doesn’t fit their standard mould, you may find yourself paying a premium for a policy that isn’t quite right. By contrast, an independent commercial insurance broker UK scours the entire market to find the best fit. Comparison sites often exacerbate this issue by using “lowest common denominator” data sets. These platforms are designed for high-volume, simple risks and frequently ignore the nuances that define a modern business. A professional broker provides a thorough audit of your operations, identifying gaps that an automated algorithm would miss. If you’re seeking an independent commercial insurance broker UK, the focus should always be on the depth of their market access and their ability to provide bespoke advice.
The focus on volume in the direct market often comes at the expense of the client relationship. Whilst a direct insurer prioritises the transaction, an independent broker focuses on longevity. They act as a steady hand, ensuring your protection evolves as your business grows. This consultative approach creates a narrative of partnership where the broker’s actions directly result in your ease and confidence. You aren’t just another policy number in a database; you are a client whose specific risks are understood and managed with precision.
Cost vs. Value: The Fee Transparency Debate
Many business owners worry that using a broker adds an unnecessary layer of cost. In reality, broker fees are often offset by the significant premium savings achieved through wider market access. A quality broker will be entirely transparent about their pricing model, justifying their value through the technical labour they perform on your behalf. It’s a pragmatic investment; the “cheapest” quote often becomes the most expensive during a catastrophic loss if the cover is found wanting. Learning how to identify business risks to insure against is a vital step in this process, helping you avoid the trap of over-insuring whilst ensuring your core assets remain protected. This ensures your budget is allocated where it matters most.
The “Small Print” Trap
Standard commercial policies are often riddled with exclusions that can catch out the unwary. Independent insurance brokers possess the technical expertise to read every line of a contract, identifying and negotiating away clauses that could lead to a declined claim. They translate complex legal jargon into actionable business advice, removing the uncertainty that often surrounds financial products. According to MoneyHelper, there are clear Advantages of using an insurance broker, especially when navigating the intricacies of specialist cover. This level of diligence provides a sense of security that a call-centre script simply cannot match. It’s about having a professional who is fiercely loyal to your interests.
How to Evaluate and Select Your Commercial Insurance Partner
Selecting the right independent commercial insurance broker UK is a decision that impacts your business’s resilience for years to come. Your first step must always be to verify their FCA authorisation. A clean regulatory record is non-negotiable; it’s the baseline for your financial security. Beyond compliance, you should assess their sector-specific experience. Ask for case studies or evidence of their industry knowledge. If they don’t understand the specific risks of your trade, they can’t effectively protect them.
The quality of a broker is often revealed during the claims process. You need to know whether claims are handled by an in-house team of advocates or outsourced to a generic third party. An in-house team ensures that the person fighting your corner understands your business history. Finally, test their responsiveness. The seniority of the person managing your day-to-day account matters. You want a seasoned professional who is accessible, not a junior staff member who lacks the authority to negotiate with underwriters.
Key Questions to Ask a Potential Broker
During your initial consultation, use these targeted questions to peel back the layers of their service:
- “Which insurers are on your panel and do you have any exclusive facilities?” This reveals the true extent of their market reach and whether they have access to specialist schemes.
- “How do you handle mid-term adjustments and policy renewals?” You need a partner who is proactive throughout the year, not just when the premium is due.
- “Can you demonstrate how you have reduced risks for similar organisations?” A quality partner should provide tangible examples of risk mitigation and premium management.
The Onboarding and Audit Process
A professional onboarding process typically begins with a comprehensive risk assessment. This isn’t a “tick-box” exercise; it’s a deep-dive audit of your current documents and operational procedures. One of the most critical parts of this review is identifying “under-insurance”. A 2025 Charterfields study found that 88% of commercial sites were underinsured on building values. If your valuations are inaccurate, you could trigger the “Average Clause” during a claim, which significantly reduces your payout.
The timeline from your initial enquiry to a fully placed insurance programme should be clear and methodical. A structured approach ensures that no detail is overlooked whilst moving at a pace that respects your operational needs. If you’re ready to secure a more resilient future, you can book a professional risk audit today to ensure your business is fully protected and compliant with 2026 standards.
Securing Your Business Future with WS Insurance Brokers
WS Insurance Brokers operates with a singular focus: your long-term security. As an independent commercial insurance broker UK, our autonomy is our most significant asset. It allows us to act as a shield between your business and the complexities of the broader market. We don’t answer to insurance company shareholders or restricted panels. We answer to you. This fierce loyalty ensures that when we scour the UK market, we’re looking for the most robust protection at the most competitive rates, without bias or restriction. Our independence is our badge of honour, and we wear it to your advantage.
Our technical expertise spans the full spectrum of business needs. Whether you require specialist commercial vehicle insurance UK for a growing fleet or complex professional indemnity for a technology startup, we provide a steady hand. We eliminate doubt by providing transparent advice and dedicated claims advocacy every step of the way. Our proactive labour results in your ease and confidence, ensuring that your insurance programme is a strategic asset rather than a confusing overhead.
A Consultative Approach to Risk
We prioritise your long-term security over simple, one-off transactions. This philosophy is rooted in our role as your “Expert Guide.” By acting as a single point of contact for all your commercial and personal insurance needs, we eliminate the fragmentation that often leads to dangerous coverage gaps. We stay ahead of emerging 2026 risks, from evolving cyber threats to shifting regulatory requirements, to keep your organisation protected. This consultative, supportive atmosphere allows you to focus on your core operations, knowing your risk profile is managed by seasoned professionals who understand your specific trade.
Taking the Next Step
Securing your business future begins with a conversation. We invite you to request a comprehensive insurance audit to identify any vulnerabilities in your current arrangements. Our process is methodical and structured:
- Initial Consultation: A deep-dive discussion to understand your unique business exposures.
- Market Scouring: We use our extensive panel access to find the most suitable coverage terms.
- Jargon-Free Proposal: You’ll receive a clear, transparent recommendation within your required timeframe.
- Dedicated Support: Ongoing policy management and claims advocacy whenever you need it.
We don’t use high-pressure tactics. Instead, we offer a steady hand in a complex market. Contact our expert team today to experience the difference that true independence makes. Let us build a bespoke protection programme that reflects the hard work you’ve put into your business.
Building Your Path to Bespoke Protection
Protecting your organisation in 2026 requires more than a standard policy; it demands a strategic partnership built on transparency and technical precision. By moving away from generic templates and embracing bespoke risk architecture, you eliminate the uncertainty of hidden exclusions and ensure your coverage performs when it matters most. Partnering with a dedicated independent commercial insurance broker UK provides the market-wide access and unbiased advocacy necessary to navigate today’s complex financial landscape with total clarity.
At WS Insurance Brokers, we take our role as your expert guide seriously. As an FCA Authorised and Regulated firm, we provide access to major UK insurer panels and deliver dedicated claims advocacy to ensure you’re never left to face a loss alone. It’s time to replace anxiety with security and obtain the long-term protection your hard work deserves. You can request a bespoke commercial insurance audit from WS Insurance Brokers today to begin your journey towards a more resilient future. We look forward to acting as your steady hand in an ever-changing market.
Frequently Asked Questions
What is the difference between an independent broker and an insurance agent?
An independent commercial insurance broker UK acts as your professional advocate, whereas an agent typically represents the interests of a specific insurance company. Brokers are not restricted to one provider’s products; they scour the entire UK market to find the most suitable protection for your business. This autonomy ensures that recommendations are based solely on your unique risk profile rather than a corporate sales quota, providing a level of transparency that tied agents cannot match.
Do independent commercial insurance brokers charge a fee for their services?
Yes, professional brokers typically charge Insurance Placement and Policy Management Fees for the technical labour involved in assessing your risk. These fees cover the meticulous sourcing of bespoke coverage from a vast panel of insurers and the ongoing administration of your programme. This transparent pricing model ensures you receive expert advice that isn’t solely dependent on insurer commissions, aligning the broker’s success directly with your long-term financial security and policy performance.
How many insurance companies does an independent broker typically work with?
A high-quality independent broker typically provides access to a vast panel of major UK insurers, including specialist providers not available to the general public. This broad market reach allows them to compare terms across dozens of carriers to secure the most competitive rates and robust wording. By accessing the entire breadth of the market, your broker can identify niche insurers who have a specific appetite for your industry, ensuring your protection is never compromised.
Can an independent broker help me if I need to make a claim?
Providing dedicated advocacy during the claims handling process is one of the most critical functions of an independent commercial insurance broker UK. Your broker acts as a professional shield, negotiating directly with the insurer to ensure settlements are fair and expedited. They understand the technicalities of your policy wording and use this expertise to challenge insurer decisions, allowing you to focus on your operations whilst your advocate manages the complex recovery process.
Is it more expensive to use a broker than buying insurance direct?
Using a broker is often more cost-effective because they prevent the expensive consequences of underinsurance or inadequate policy wording. Whilst direct insurers might offer lower initial premiums for generic products, they often lack the bespoke protection needed for complex risks. A broker’s ability to scour the wider market frequently results in premium savings that offset their professional fees, providing significantly better value through superior coverage and the removal of dangerous “small print” traps.
How often should my independent broker review my business insurance programme?
Your insurance programme should be formally reviewed at least once a year during the renewal process. However, a proactive broker will also suggest mid-term adjustments if your business undergoes significant changes, such as acquiring new property, increasing staff numbers, or expanding into new markets. These regular audits are essential to ensure your valuations remain accurate and that your coverage continues to reflect your current risk profile in an ever-evolving economic landscape.
Can a broker help with specialist cover like Cyber or Directors and Officers insurance?
Yes, independent brokers specialise in sourcing complex protection such as Cyber & Data Breach Insurance and Directors & Officers Insurance. These lines require a deep understanding of technical liabilities and regulatory requirements that standard policies often overlook. Your broker will assess your specific exposures to digital threats and management risks, crafting bespoke wording that protects your leadership team and digital assets from increasingly sophisticated 2026 threats that could otherwise cripple your organisation.
What information do I need to provide for a commercial insurance quote?
To secure an accurate quote, you’ll need to provide details regarding your business turnover, staff numbers, and a comprehensive claims history. If you’re seeking Commercial Property Insurance, you must also provide accurate rebuild valuations and details of your premises’ construction and security measures. Providing thorough information allows your broker to present your business as a “preferred risk” to underwriters, which is essential for securing the most favourable terms and removing uncertainty during placement.