
With global insolvencies projected to rise by up to 6% throughout 2026, the risk of an overseas buyer collapsing before an invoice is settled has become a tangible threat to UK balance sheets. It’s a daunting reality for many business leaders; the anxiety of navigating foreign insolvency where UK law doesn’t apply can often stifle international ambitions. You’ve likely felt the pressure of wanting to offer competitive credit terms whilst worrying that one major default could compromise your entire cash flow, which is why securing the right trade credit insurance for exporters has become a strategic priority.
We believe that exporting shouldn’t feel like a gamble. This guide demonstrates how these bespoke policies act as a steady hand, removing the uncertainty of non-payment and political instability. By securing your revenue, you don’t just protect what you’ve earned; you also improve your standing with banks who favour insured receivables when providing growth finance. We’ll explore how to eliminate bad debt risk, the benefits of independent market-wide advice, and the methodical steps to winning more business with the confidence of a fully protected ledger.
Key Takeaways
- Understand how trade credit insurance for exporters shields your revenue from buyer insolvency and unpredictable political events beyond your control.
- Learn how to win more international business by confidently offering open account terms without risking your vital cash flow.
- Discover how an insured ledger can improve your standing with lenders and unlock more favourable access to trade finance.
- Explore why an independent broker serves as your dedicated advocate, providing access to the entire market and expert support during the claims process.
- Master the essential steps to organising a bespoke policy, including how to conduct a thorough risk assessment of your current export ledger.
What is Trade Credit Insurance for Exporters?
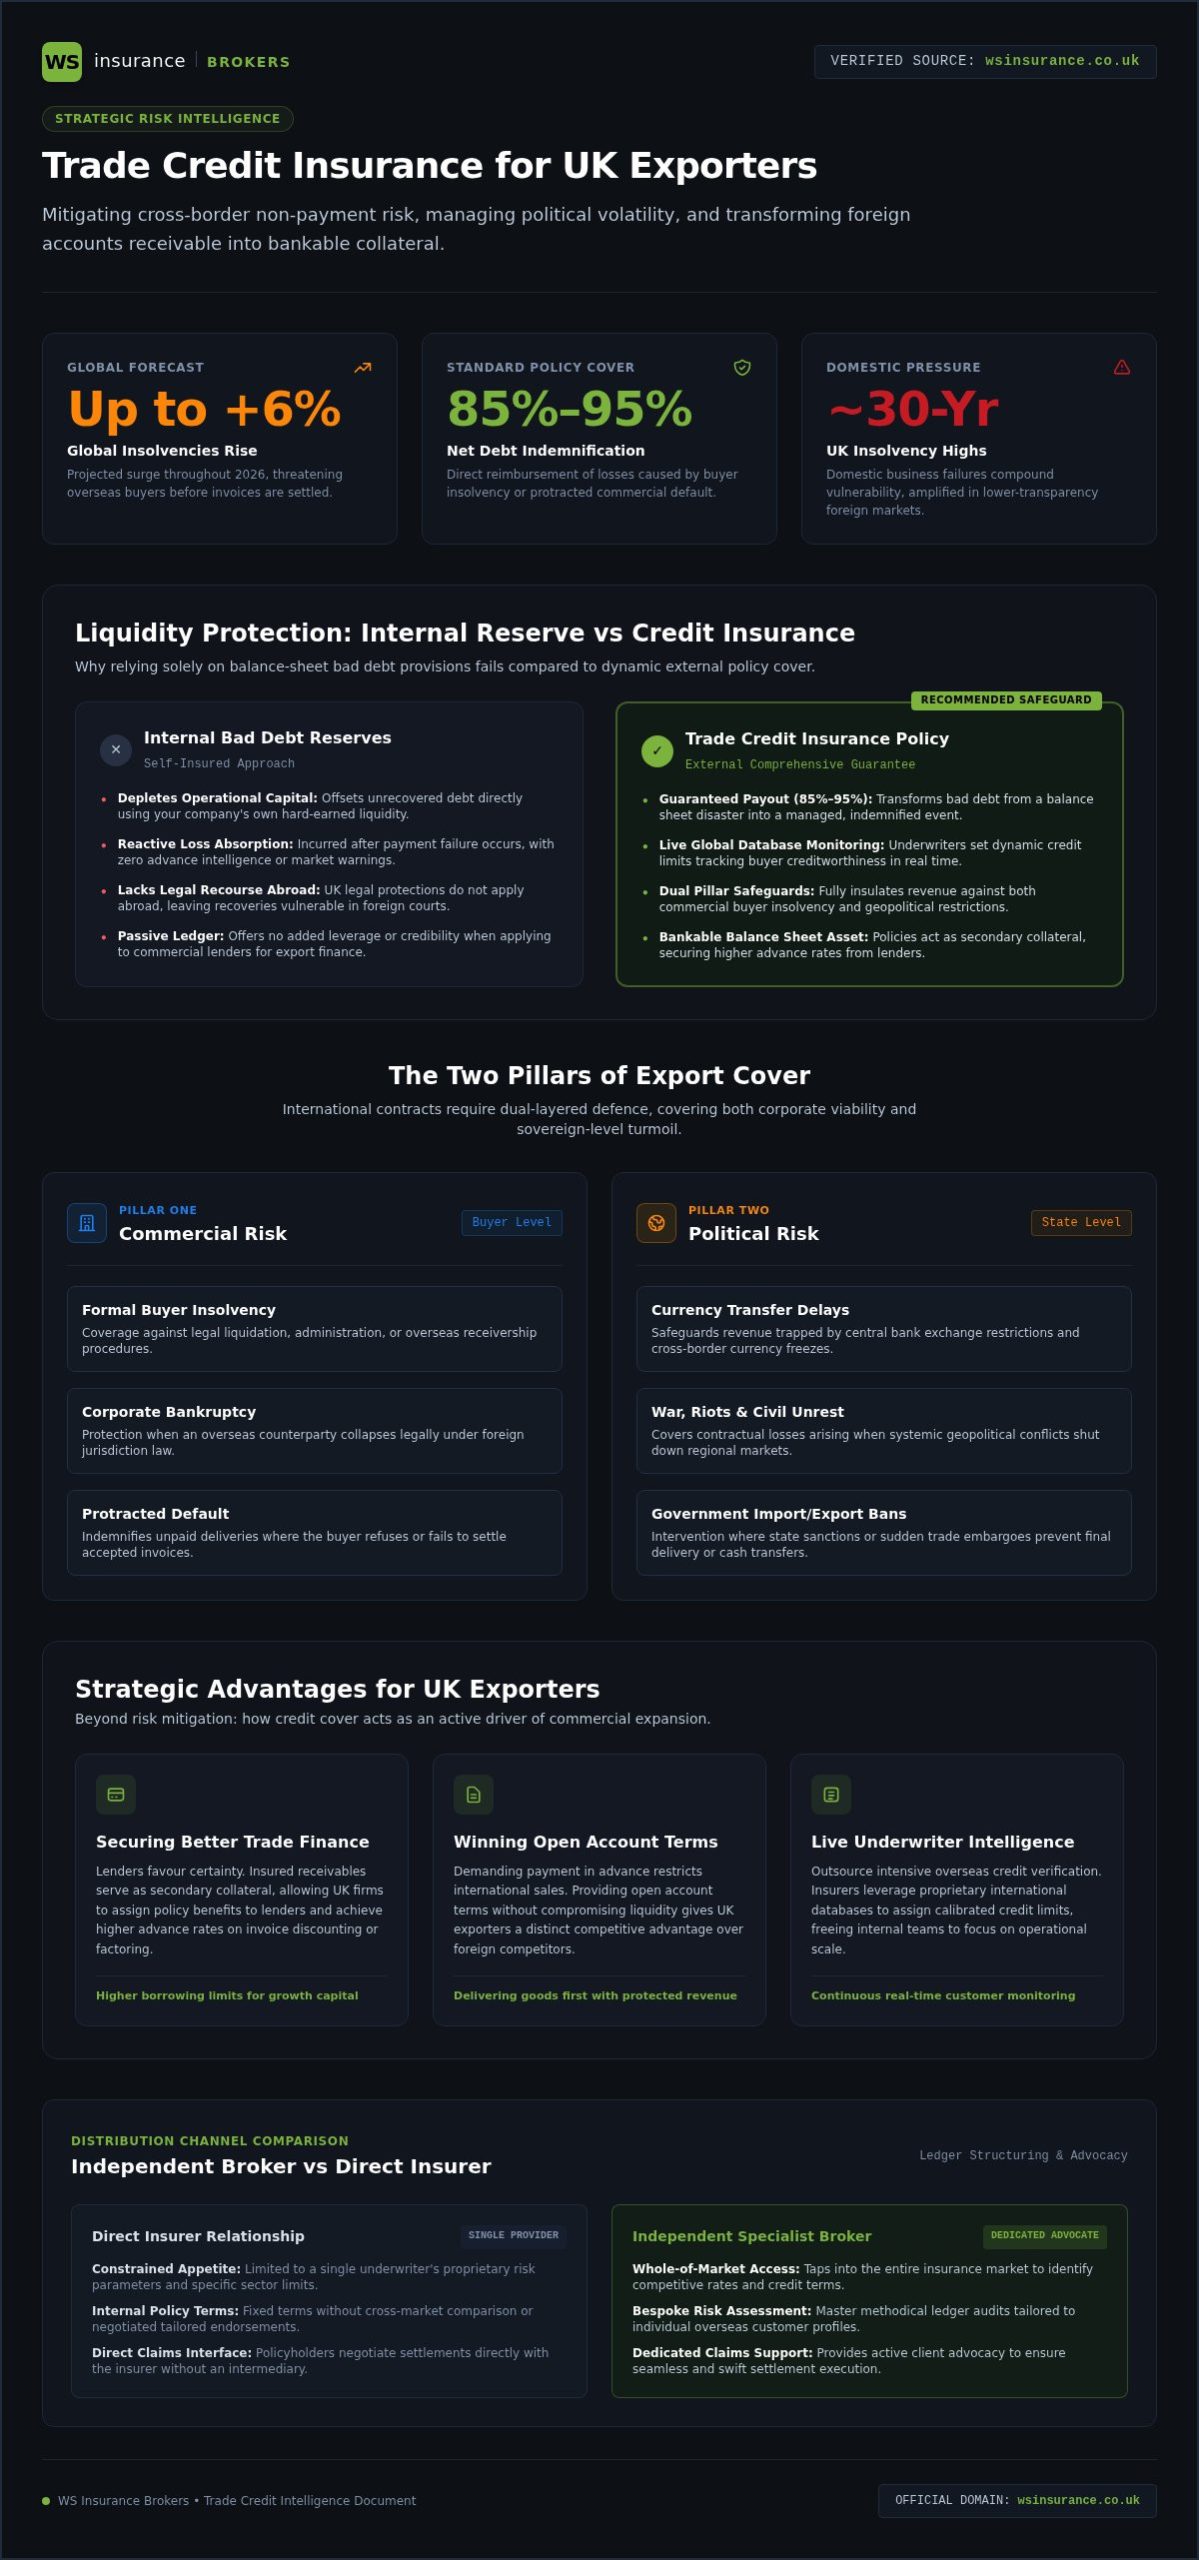
Trade credit insurance for exporters is a specialised financial safeguard designed to protect your turnover from the risk of non-payment by international buyers. It’s specifically tailored for businesses trading on “open account” terms, where you deliver goods or services before receiving payment. Instead of leaving your balance sheet exposed to the whims of a foreign jurisdiction, this policy transforms your accounts receivable into a secure, bankable asset. If a buyer fails to pay due to insolvency or protracted default, the insurer steps in to cover the loss, typically indemnifying between 85% and 95% of the net debt.
This protection is essential because it removes the vulnerability associated with international trade. When you’re dealing with buyers across borders, you don’t always have the same legal recourse as you do in the UK. A policy acts as a safety net, ensuring that your business remains liquid even if a major customer collapses. It’s the difference between a catastrophic loss and a managed, insured event.
The Core Function of Export Credit Cover
A policy does more than just pay out after a default; it proactively monitors the financial health of your international customers. Insurers use vast global databases to assign specific “credit limits” to each of your buyers. These limits represent the maximum amount of debt the insurer is willing to cover for that specific customer. Relying on this live intelligence is far more effective than maintaining simple bad debt reserves on your balance sheet. While a reserve fund only offsets a loss with your own cash, trade credit insurance for exporters provides an external guarantee, preserving your liquidity when it’s needed most.
Commercial vs. Political Risk: The Two Pillars of Protection
Exporting in 2026 requires a dual-layered approach to risk management. Commercial risk focuses on the buyer’s direct ability to pay, covering scenarios such as formal insolvency, bankruptcy, or simple non-payment. With UK company insolvencies tracking near 30-year highs, the risk of a buyer failing is significant, and that risk is often amplified in foreign markets where financial transparency may be lower.
Political risk addresses broader environmental factors beyond a buyer’s control. This includes currency transfer delays, war, riots, or government-imposed import and export bans that prevent payment from reaching the UK. For modern exporters, having protection against both pillars is vital. Whilst commercial defaults are common, political instability can freeze entire markets overnight. A robust policy ensures that whether the failure is at a corporate or state level, your business remains resilient and secure.
The Strategic Benefits of Insuring Your Export Debt
The true value of trade credit insurance for exporters lies in its ability to transform your business from a cautious participant into a confident global competitor. Beyond the immediate protection against bad debt, a policy acts as a sophisticated growth tool. By outsourcing the intensive credit-checking process to an insurer, you gain access to vast proprietary databases that track the real-time financial health of buyers across the globe. This allows your internal teams to focus on sales and operations rather than manual risk assessments, whilst providing directors and stakeholders with the long-term security they need to approve ambitious expansion plans.
Confidence is the currency of international trade. When your ledger is insured, you can explore new territories with the knowledge that your revenue is protected against both commercial defaults and the rising tide of political instability. It removes the hesitation often associated with high-value contracts in unfamiliar jurisdictions. For many firms, partnering with an independent specialist to manage these risks is the final step in professionalising their export strategy.
Securing Better Trade Finance Terms
Lenders favour certainty. When you present an accounts receivable ledger backed by a global insurer, you’re no longer asking for a loan based on hope, but on guaranteed assets. Banks and alternative lenders are far more likely to offer competitive rates for invoice discounting or factoring when the risk of non-payment is mitigated. Trade credit insurance acts as a form of secondary collateral, allowing UK businesses to assign policy benefits to their lender to secure higher advance rates on growth capital. This improved standing with financial institutions often results in higher borrowing limits, providing the liquidity necessary to fulfil larger international orders.
Winning More Contracts with Open Account Terms
Independent Broker vs. Direct Insurer: Making the Right Choice
Choosing how to source your cover is as critical as the protection itself. Direct underwriters, such as Allianz or Atradius, only offer their proprietary products. They are bound by their own internal risk appetites and data sets, which means their perspective on a specific market is often final. An independent broker, however, acts as your dedicated advocate. We scan the entire market to find the best fit for your specific sector and export destinations. This ensures you aren’t restricted to a single provider’s view of a particular country or industry, which is vital when arranging trade credit insurance for exporters in a volatile global economy.
Bespoke policies are typically more cost-effective than generic, off-the-shelf solutions. Generic products often include premiums for risks you don’t actually face, whereas a specialist broker negotiates terms based on your unique trading history. By working with a professional who understands the nuances of UK export regulations and shifting global trade flows, you ensure your policy is lean, effective, and tailored to your actual exposure. This methodical approach removes the “fat” from your insurance costs whilst maximising your protection.
The Value of Market-Wide Access
Not all insurers view the world through the same lens. One underwriter might have a high appetite for exports to South America, whilst another may be pulling back from that region due to internal exposure limits. By comparing multiple providers, a broker identifies the underwriters with the highest appetite for your specific target markets. We also leverage our industry relationships to secure higher credit limits for your key customers; limits that a direct insurer might have refused without our intervention. You can learn more about how we manage this by reading our Insurance Brokers: The Complete 2026 Guide.
Dedicated Claims Advocacy
International debt recovery is notoriously complex. When a foreign buyer fails to pay, the administrative burden on your finance team can be overwhelming. A broker acts as a shield between you and the insurer’s claims department. We manage the entire process, ensuring you meet all strict policy obligations and advocating for the maximum payout allowed under your terms. This expert guidance is vital during stressful non-payment events, as we navigate the nuances of policy wording to ensure your claim is settled promptly. Having a steady hand to manage these disputes allows your team to stay focused on running the business rather than chasing distant debts.
How to Organise and Manage Your Export Credit Policy
Securing a policy is only the first stage of a robust strategy. To ensure your protection remains effective, you must actively manage it. This begins with conducting a thorough risk assessment of your current export ledger to identify which buyers or territories carry the highest potential for default. Once established, you’ll need to set realistic credit limits for each buyer. These aren’t arbitrary figures; they’re calculated based on real-time insurer data and your own trading history. We recommend establishing a clear internal process for reporting overdue payments immediately, as failing to do so can jeopardise your ability to claim.
Your export destinations will likely evolve throughout the year. As you enter new markets, your policy must adapt to reflect these changes. Regularly reviewing your coverage with a specialist ensures you aren’t paying for protection you no longer need or, conversely, leaving new contracts exposed. If you’re ready to secure your ledger, you can request a bespoke market review from our team today.
The Application and Underwriting Process
Underwriters require a detailed snapshot of your business to provide accurate terms. You’ll need to provide your annual export turnover, a history of any bad debt losses over the last three to five years, and specific details for your largest buyers. In 2026, underwriters are particularly focused on geopolitical stability and sector-specific inflation when assessing risk. You’ll also need to decide between “Whole Turnover” cover, which protects your entire export ledger, and “Specific Account” cover, which targets only your largest or riskiest contracts. While Whole Turnover provides the most comprehensive security, Specific Account policies can be useful for one-off, high-value projects.
Maintaining Compliance and Maximising Cover
Policy compliance is non-negotiable. You must adhere strictly to the “maximum credit period” defined in your terms, which is the total time allowed from the invoice date to the final payment deadline. If a buyer misses this window, you must stop further shipments and notify the insurer within the specified timeframe. Most insurers now provide digital portals where you can request limit increases as your contracts grow. Using these tools effectively, whilst maintaining proactive communication with your broker, prevents the risk of “voiding” your cover during a claim event. We act as your shield, ensuring that administrative errors don’t stand in the way of your financial security when managing trade credit insurance for exporters.
Securing Your Global Future with WS Insurance Brokers
WS Insurance Brokers acts as a steady hand in the complex world of international trade. We understand that the fear of non-payment can be a significant barrier to growth; therefore, our approach focuses on removing anxiety through transparent, methodical advice. By combining clinical professional precision with a warm, client-centric focus, we ensure your business remains protected against the unpredictable. Our expertise across the full spectrum of business insurance allows us to view your export strategy as part of a wider, secure framework. We don’t just sell policies. Instead, we build a narrative of partnership where our proactive labour directly results in your ease and confidence.
We believe that every exporter deserves a protective shield between their balance sheet and the complexities of the broader market. Our role as your trusted advisor is to offer a consultative, supportive atmosphere that prioritises your long-term security over any immediate transaction. By providing a clear path from uncertainty to absolute clarity, we empower you to make bold decisions for your company’s future.
Why UK Exporters Trust Our Expertise
The 2026 market presents unique challenges that require a seasoned professional’s touch. We navigate the entire breadth of the UK insurance landscape to find competitive rates and robust coverage that match your unique export profile. Unlike large, automated corporations, we offer direct access to experienced brokers who act as your protective shield in the global market. This long-term partnership prioritises your security over a simple transaction, ensuring you have a loyal advocate who remains accessible whenever you need clarity. Our independence is our badge of honour. It allows us to remain fiercely loyal to your interests rather than those of the underwriters, providing a consultative atmosphere that puts your business first.
Take the First Step Toward Risk-Free Exporting
Transitioning from an uninsured to a fully protected status doesn’t have to be a daunting or complex journey. We simplify the entire process, starting with a comprehensive consultation to review your current credit management strategy and identify hidden vulnerabilities in your ledger. We’ll help you arrange trade credit insurance for exporters that fits your business like a glove, removing the uncertainty that holds many firms back from entering high-potential emerging markets. Our goal is to provide the absolute peace of mind required to offer competitive terms and win more business. If you’re ready to eliminate the doubt from your international sales and secure your cash flow, speak with a trade credit specialist today to begin your journey toward secure global growth.
Empowering Your International Ambition
Exporting remains a vital engine for growth, yet success in 2026 requires more than just a quality product; it demands financial resilience. By integrating trade credit insurance for exporters into your operations, you transform your international ledger from a source of anxiety into a strategic asset. You’ve seen how these policies shield your revenue from insolvency and political risk whilst simultaneously improving your standing with lenders. This methodical approach to risk management allows you to offer the competitive terms necessary to win global contracts with absolute confidence.
As an FCA Authorised and Regulated broker, we provide independent market-wide access and specialist claims advocacy support to act as your shield in a complex market. Our role is to remove the uncertainty from your trade cycles, ensuring you can focus on expansion while we manage the granular details of your protection. We invite you to secure your export revenue with a bespoke trade credit policy from WS Insurance Brokers today. Let’s work together to turn your global ambitions into a secure, predictable reality.
Frequently Asked Questions
Does trade credit insurance cover 100% of the loss?
No, trade credit insurance typically covers between 85% and 95% of the net debt. This indemnity level ensures that the exporter maintains a vested interest in the credit management process. It doesn’t eliminate 100% of the loss. However, it effectively removes the catastrophic financial impact that a major default would otherwise have on your business’s cash flow and long-term stability.
Can I insure just one single high-value export contract?
Yes, you can secure cover for a single high-value export contract through what is known as “Specific Account” or “Single Buyer” insurance. This is useful for businesses delivering one-off capital projects or dealing with a single dominant international client. It allows you to protect a specific revenue stream. You don’t need to insure your entire turnover. This provides targeted security for your most significant exposures.
What is the difference between trade credit insurance and a Letter of Credit?
A Letter of Credit is a bank-led payment mechanism. It’s often administratively heavy and expensive for your buyer. In contrast, trade credit insurance for exporters allows you to offer flexible “open account” terms while maintaining protection. This makes your business more competitive. It removes the friction of bank guarantees, allowing goods to flow more freely while your revenue remains protected.
How much does trade credit insurance for exporters cost?
The cost of a policy is determined by several factors. These include your annual export turnover, your historic loss record, and the specific risk profiles of your target countries. Premiums are typically calculated as a small percentage of the insured volume. Because every business has a unique risk profile, we focus on sourcing bespoke quotes. These reflect your actual trading patterns rather than applying generic, one-size-fits-all pricing models.
What happens if my overseas customer becomes insolvent?
If an overseas customer becomes insolvent, you should immediately notify your broker to begin the claims process. We act as your dedicated advocate, handling the technical communication with the insurer and ensuring all policy obligations are met. Once the claim is verified, the insurer pays out the agreed indemnity percentage. This effectively replaces the lost revenue and protects your company’s vital working capital from the default.
Is political risk cover included as standard in export policies?
Political risk cover is a standard component of most dedicated export credit policies, though the specific breadth of cover can vary. It protects your business against losses arising from events beyond the buyer’s control. These include war, civil unrest, or government-imposed currency transfer restrictions. Having this protection is essential for 2026 exporters. It allows you to navigate a volatile global landscape with absolute financial certainty and confidence.
How does trade credit insurance help me get a bank loan?
Trade credit insurance acts as a form of secondary collateral that makes your ledger more “bankable.” Lenders are often willing to advance higher percentages against your invoices, sometimes up to 90%, when they know the debt is insured. This improved risk profile can lead to more favourable interest rates. It also increases borrowing limits, providing the liquidity you need to fund large-scale international growth and new contract fulfilment.
Can I get cover for customers in emerging markets or developing countries?
You can certainly obtain cover for buyers in emerging markets, although underwriters will assess these risks with greater scrutiny. Independent brokers have access to specialist insurers who have a higher appetite for developing jurisdictions. We can help you secure trade credit insurance for exporters that covers these regions. This provides the credit limits necessary to expand into high-growth markets without exposing your business to unmanageable risks.