
Did you know that private medical insurance has officially overtaken flexible working as the most requested employee benefit in 2026? For many directors, securing small business private medical insurance London is no longer a luxury; it’s a vital defensive strategy against the mounting pressure on public health services. You’ve likely seen how rising NHS waiting times can stall projects and dampen team morale when key staff are absent or unwell. It’s a common concern, yet the path to providing high-quality care often feels obscured by complex jargon and shifting tax regulations.
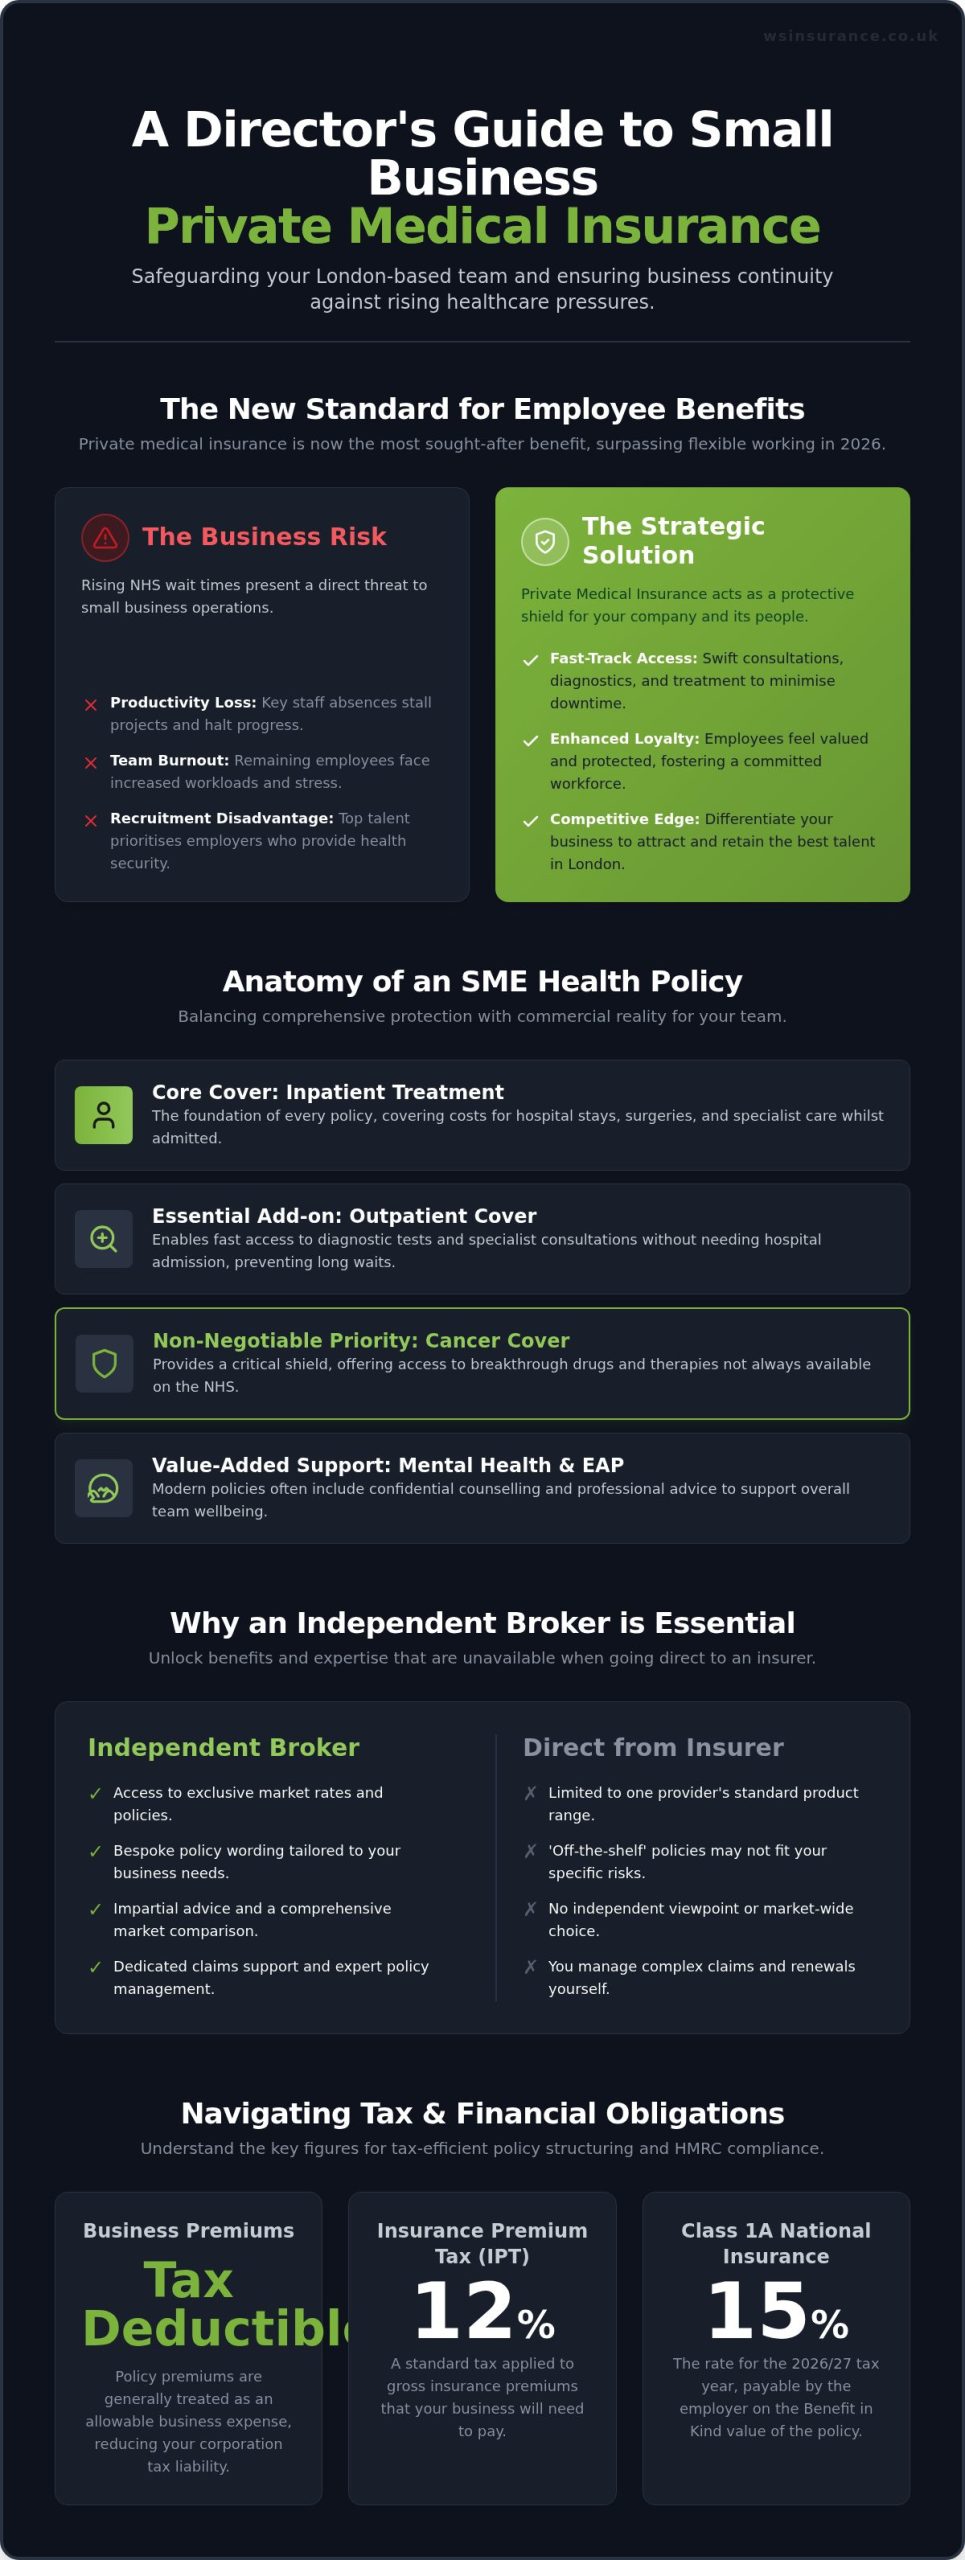
We believe that protecting your workforce shouldn’t be a source of stress. This strategic guide will help you secure bespoke, tax-efficient health cover that safeguards both your employees and your bottom line. You’ll learn how to navigate the 12% Insurance Premium Tax and prepare for the 15% Class 1A National Insurance rate for the 2026/27 tax year. We’ll also explore how fast access to private consultants can foster a healthier, more loyal team, ensuring your business remains a steady hand in a competitive market.
Key Takeaways
- Understand why rising NHS waiting times represent a significant risk to your business continuity and how private access mitigates this.
- Discover how to structure small business private medical insurance London to balance comprehensive cancer cover with sustainable premium costs.
- Learn why independent brokers can access exclusive market rates and bespoke policy wordings that aren’t available when buying directly from insurers.
- Gain clarity on the tax-deductible nature of premiums and how to manage Benefit in Kind obligations whilst ensuring HMRC compliance.
- Identify the proactive steps needed to secure a healthier, more loyal workforce through expert policy management and dedicated claims support.
Why Small Business Private Medical Insurance in London and the UK is Essential
Private Medical Insurance (PMI) isn’t just an optional perk; it’s a proactive commitment to your team’s health and your company’s operational stability. For an SME, PMI functions as a collective safety net that provides your staff with private access to specialists, diagnostic tests, and hospital treatment. Whilst a sole director might opt for an individual policy, a group scheme allows a company to cover multiple employees under one umbrella, often unlocking more favourable rates and broader coverage options. The UK Private Healthcare System operates as a vital secondary layer to the NHS, offering a route to bypass the queues that can otherwise paralyse a small team.
Securing small business private medical insurance London helps you act as a shield for your staff. It ensures they aren’t left waiting for critical consultations whilst your business’s productivity suffers. In a city where the pace of commerce is relentless, the ability to fast-track a diagnosis can be the difference between a minor disruption and a significant commercial setback.
The Impact of Healthcare Wait Times on Small Business Productivity
Delayed treatment is a silent productivity killer. In a large corporation, one person’s absence is often just a statistic. In a small London team, it’s a crisis. When a key employee is sidelined by a long NHS waiting list, the remaining staff must shoulder the extra burden, which often leads to burnout and a drop in overall output. We find that fast-track diagnostic services are the most valued feature for SMEs. Getting an answer in days rather than months allows for quicker treatment and a predictable return to work. The cost of a monthly premium is almost always lower than the cost of long-term absenteeism or the expense of hiring temporary contractors to fill a sudden gap.
PMI as a Strategic Recruitment Tool
Attracting top-tier talent in the capital requires more than just a competitive salary. Candidates now prioritise security and well-being. Since private medical insurance was listed by the Rewards and Employee Benefits Association (REBA) as the number one requested benefit in 2026, it’s clear that health is a primary concern for the modern workforce. Providing small business private medical insurance London allows you to differentiate your firm from larger, more impersonal competitors. It creates a psychological bond of loyalty. Your employees feel protected and valued, which fosters a culture of commitment that’s hard to break. You aren’t just buying an insurance product; you’re investing in a healthier, more dedicated team.
Understanding the Core Components of SME Health Cover
Building a policy for a small team requires a steady hand to balance comprehensive protection with commercial reality. At its heart, small business private medical insurance London consists of inpatient cover, which handles hospital stays and surgeries. Most firms then layer on outpatient cover to ensure employees can access specialists and diagnostic tests without delay. We strongly advise that cancer cover remains a non-negotiable priority. It provides access to breakthrough treatments and biological therapies that might not be readily accessible elsewhere, offering a vital shield for your staff during their most vulnerable moments.
Beyond the clinical essentials, modern policies often include mental health support and Employee Assistance Programmes (EAPs). These services provide confidential counselling and professional advice, helping your team manage the unique pressures of the London business environment. Whilst dental and optical options are available as add-ons, they’re often secondary to the core mission of protecting against significant health risks.
Essential vs. Optional Cover for Small Teams
For micro-businesses with two to ten employees, every penny of the premium must work hard. You can manage costs by adjusting the ‘excess’, which is the amount an employee pays towards their first claim. Increasing this figure often results in a lower annual premium. Another lever is the choice of hospital list. Whilst a ‘London’ list provides access to prestigious facilities in the capital, opting for a standard national list can reduce costs if your team is happy to travel slightly further for care. It’s also vital to understand the Tax Implications of Medical Benefits, as these choices affect your P11D reporting and National Insurance liabilities. If you’re unsure which options fit your specific needs, speaking with an expert at WS Insurance can help remove the guesswork.
The Rise of Digital Health Services
Modern policies have evolved far beyond simple hospital cover. 24/7 virtual GP access is now a standard feature that has become a game-changer for busy entrepreneurs. It allows staff to book video consultations during lunch breaks, reducing the need for half-day absences for routine appointments. Many insurers also include mental health apps and proactive wellness tools as part of their core offering. These tools provide support for stress and anxiety, catching issues before they escalate into long-term sick leave. Digital-first providers are streamlining the claims process too, using intuitive apps to authorise treatment in minutes. This level of transparency and speed ensures your team feels supported at every stage of their recovery journey.
Comparing Direct Providers vs. Independent Broker Placement
When you approach a single insurer directly, you’re only seeing one slice of the market. It’s a restricted view that often prioritises the provider’s bottom line over your specific requirements. Choosing small business private medical insurance London through an independent broker like WS Insurance Brokers changes this dynamic entirely. We act as a shield, filtering out unsuitable products and focusing on bespoke solutions that offer genuine value. Independent brokers often secure “broker-only” rates and enhanced policy wordings that aren’t visible on public websites. This ensures your coverage is as precise as your business operations, removing the uncertainty that comes with generic, off-the-shelf products.
Beyond the initial placement, the true value of a broker lies in ongoing advocacy. If a claim becomes complex or a provider disputes a particular treatment, you have a professional on your side to navigate the technicalities. This level of support is essential when PMI is a cornerstone of your wider benefits package. It transforms the insurance from a simple commodity into a managed service that protects your team’s health and your company’s interests with equal diligence.
Why One Size Does Not Fit All in SME Insurance
Every small business has a unique risk profile that a computer algorithm can’t fully grasp. A niche technology firm has different needs compared to a traditional professional services consultancy. A broker takes the time to understand these nuances before approaching the market. They assess your specific sector risks and employee demographics to ensure the policy wordings actually fit. For a deeper look at how this professional placement works, you can explore our Insurance Brokers: The Complete 2026 Guide. This consultative approach eliminates the danger of paying for cover you don’t need whilst leaving critical gaps in your protection.
The Renewal Process: Avoiding the “Loyalty Tax”
It’s a common industry practice for insurers to offer enticing introductory discounts to win new business. For instance, AXA Health offered a 25% discount for new customers between May and September 2026. However, these rates can shift significantly at the first renewal. Without a broker, many businesses fall victim to a “loyalty tax” where premiums climb simply because the owner is too busy to shop around. We manage this process by re-marketing your policy annually. We compare your current performance against the entire breadth of the market to ensure your small business private medical insurance London remains competitively priced. Switching providers is often much simpler than business owners think, especially when a broker handles the administrative transition on your behalf.
Navigating Tax Efficiency and Policy Structuring
Understanding the fiscal landscape is essential when you’re looking to secure small business private medical insurance London. For a limited company, HMRC generally treats these premiums as an allowable business expense. This allows you to offset the cost against your corporation tax, effectively reducing the net price of the policy. It’s a pragmatic way to protect your workforce whilst managing your tax liabilities. However, it’s vital to remember that the taxman views this cover as a “benefit in kind” (BIK) for the employee. Whilst the business gains a deduction, the individual staff member, including directors, will be liable for income tax based on the value of the premium. This is a core component of a broader Business Insurance in the UK strategy that balances protection with financial efficiency.
HMRC Rules for Small Business Health Schemes
Choosing the right underwriting method is a critical decision that affects both the cost and the clarity of your cover. Most small London teams opt for Moratorium underwriting. This approach simplifies the application by excluding any medical conditions the employee has sought advice or treatment for in the last five years. It’s a quick way to get a scheme started without lengthy health questionnaires. Alternatively, Full Medical Underwriting (FMU) requires a detailed health declaration from each staff member at the outset. Whilst this takes more effort, it provides absolute certainty about what’s covered from day one. You can also choose to include family members on the policy. This is a powerful retention tool, though you should communicate clearly that this will increase the employee’s personal BIK tax liability. If you’re ready to build a scheme that fits your team’s specific needs, you can request a bespoke consultation with our expert advisors.
Securing Bespoke Private Medical Insurance through WS Insurance
We position ourselves as your expert guide, removing the uncertainty that often clouds health cover decisions. Our role is to act as a shield, ensuring you’re never exposed to the complexities of the broader market without professional protection. By choosing WS Insurance, you gain access to a wide panel of leading UK insurers, including Bupa, AXA Health, and Vitality. This independence ensures that our recommendations are based solely on your requirements rather than biased quotas. When you seek small business private medical insurance London, you deserve a partner who understands the local landscape whilst providing national coverage from our offices in London, Bristol, and Exeter.
Our approach is built on transparency and integrity. We avoid high-pressure sales tactics in favour of a consultative, supportive atmosphere that prioritises your long-term security. We believe that professional advice should be accessible and human, which is why we offer direct communication channels that contrast with the impersonal nature of automated corporations. We do the heavy lifting, comparing pricing models and policy wordings to provide a pragmatic justification for every recommendation we make.
Our Process: From Risk Assessment to Policy Placement
We follow a methodical, three-step rhythm to ensure your policy is a perfect fit for your team. First, we conduct a thorough consultation to understand your specific business goals and the unique demographics of your workforce. Second, we perform a market-wide search for the most competitive bespoke cover, utilizing our industry tenure to find rates and terms that are often restricted to the broker market. Finally, we provide a clear, jargon-free presentation of your options. This structured transition from high-level identity to granular service details allows you to make an informed decision with absolute confidence.
Dedicated Claims Support and Ongoing Advocacy
Our commitment to your security begins, not ends, when the policy is signed. We believe in a narrative of partnership where our proactive labour directly results in your ease of mind. If your business grows or your requirements shift mid-term, we handle the adjustments with clinical precision. Should you ever face a complex claim or a dispute with a provider, our team acts as your dedicated advocate. We navigate the technicalities on your behalf, ensuring your staff receive the care they were promised without you having to battle through administrative red tape. It’s time to remove the doubt from your employee benefits strategy. Contact WS Insurance Brokers today for a bespoke PMI consultation and secure the steady hand your business needs.
Securing Your Team’s Future with Strategic Health Cover
We’ve explored how a tailored health scheme acts as a vital shield for your workforce, mitigating the risks of rising treatment wait times whilst significantly enhancing your recruitment appeal. You now understand the importance of balancing inpatient essentials with digital health tools and navigating the specific HMRC reporting requirements for 2026. Choosing the right partner for small business private medical insurance London ensures your policy remains tax-efficient and commercially sustainable throughout the year.
As an independent, FCA authorised and regulated brokerage, we provide access to the whole of the market and offer a dedicated claims support team to manage every detail on your behalf. Our autonomy allows us to remove the uncertainty from the selection process, acting as a steady hand in a complex marketplace. We do the heavy lifting so you can focus on growing your business with a healthy, protected team. Taking these proactive steps today will foster a more resilient and loyal workforce for years to come.
Get a Bespoke Private Medical Insurance Quote from WS Insurance
Frequently Asked Questions
Is private medical insurance a taxable benefit for employees?
Can a small business with only two employees get group health insurance?
You can certainly secure a group health insurance scheme with just two employees. Most major UK insurers offer “micro-group” policies specifically designed for businesses with two to ten staff members. These schemes often provide more comprehensive cover and more stable pricing than individual policies. It’s an excellent way for small firms to provide high-level protection whilst benefiting from the administrative simplicity and potential tax advantages associated with a corporate health scheme.
How much does small business private medical insurance cost on average in 2026?
The cost of small business private medical insurance London varies significantly based on your team’s unique profile. Factors such as the average age of your employees, the specific level of outpatient cover you select, and the breadth of your hospital list all influence the final premium. Instead of relying on generic estimates, we conduct a market-wide search to find the most competitive pricing for your specific needs, ensuring your protection remains commercially sustainable.
What is the difference between moratorium and full medical underwriting?
Moratorium underwriting excludes any medical conditions your employees have sought advice or treatment for during the past five years. It’s a faster setup process with no initial health forms. Full medical underwriting requires each staff member to complete a detailed health declaration at the outset. Whilst this takes more time, it provides absolute clarity on exactly what is covered from day one, removing any uncertainty regarding pre-existing conditions when a claim is eventually made.
Does small business health insurance cover pre-existing conditions?
Standard policies generally exclude pre-existing conditions that were present in the years immediately preceding the policy’s start date. However, larger small businesses with fifteen or more employees might be eligible for “Medical History Disregarded” (MHD) underwriting. This premium option allows the scheme to cover pre-existing conditions without individual health checks. For smaller teams, we focus on structuring policies that provide the broadest possible protection whilst being transparent about any necessary clinical exclusions.
Can I include my family on my small business health insurance policy?
Most group schemes allow you to add family members, including partners and children, to the policy. This is a highly valued benefit that can significantly boost employee loyalty and peace of mind. You’ll need to decide whether the business pays the full premium or if the employee contributes. It’s important to note that adding family members will increase the total premium and the individual’s personal Benefit in Kind tax liability reported to HMRC.
How long does it take to set up a new group health insurance scheme?
Setting up a new scheme usually takes between one and two weeks from the initial consultation to the policy going live. The process involves assessing your team’s requirements, conducting a market-wide search, and finalising the employee data. We handle the administrative heavy lifting to ensure a smooth transition. Once the documentation is processed and the first premium is paid, your staff can begin accessing private consultations and diagnostic services almost immediately.
Why should I use an insurance broker instead of a comparison site?
A comparison site provides a generic list of prices, but it can’t offer the bespoke advice or claims advocacy we provide. As independent brokers, we access the entire market to find “broker-only” rates and tailored policy wordings that aren’t available on public platforms. We act as your trusted advisor, removing the stress of selecting small business private medical insurance London and standing as a shield between you and the insurers during complex claims.