
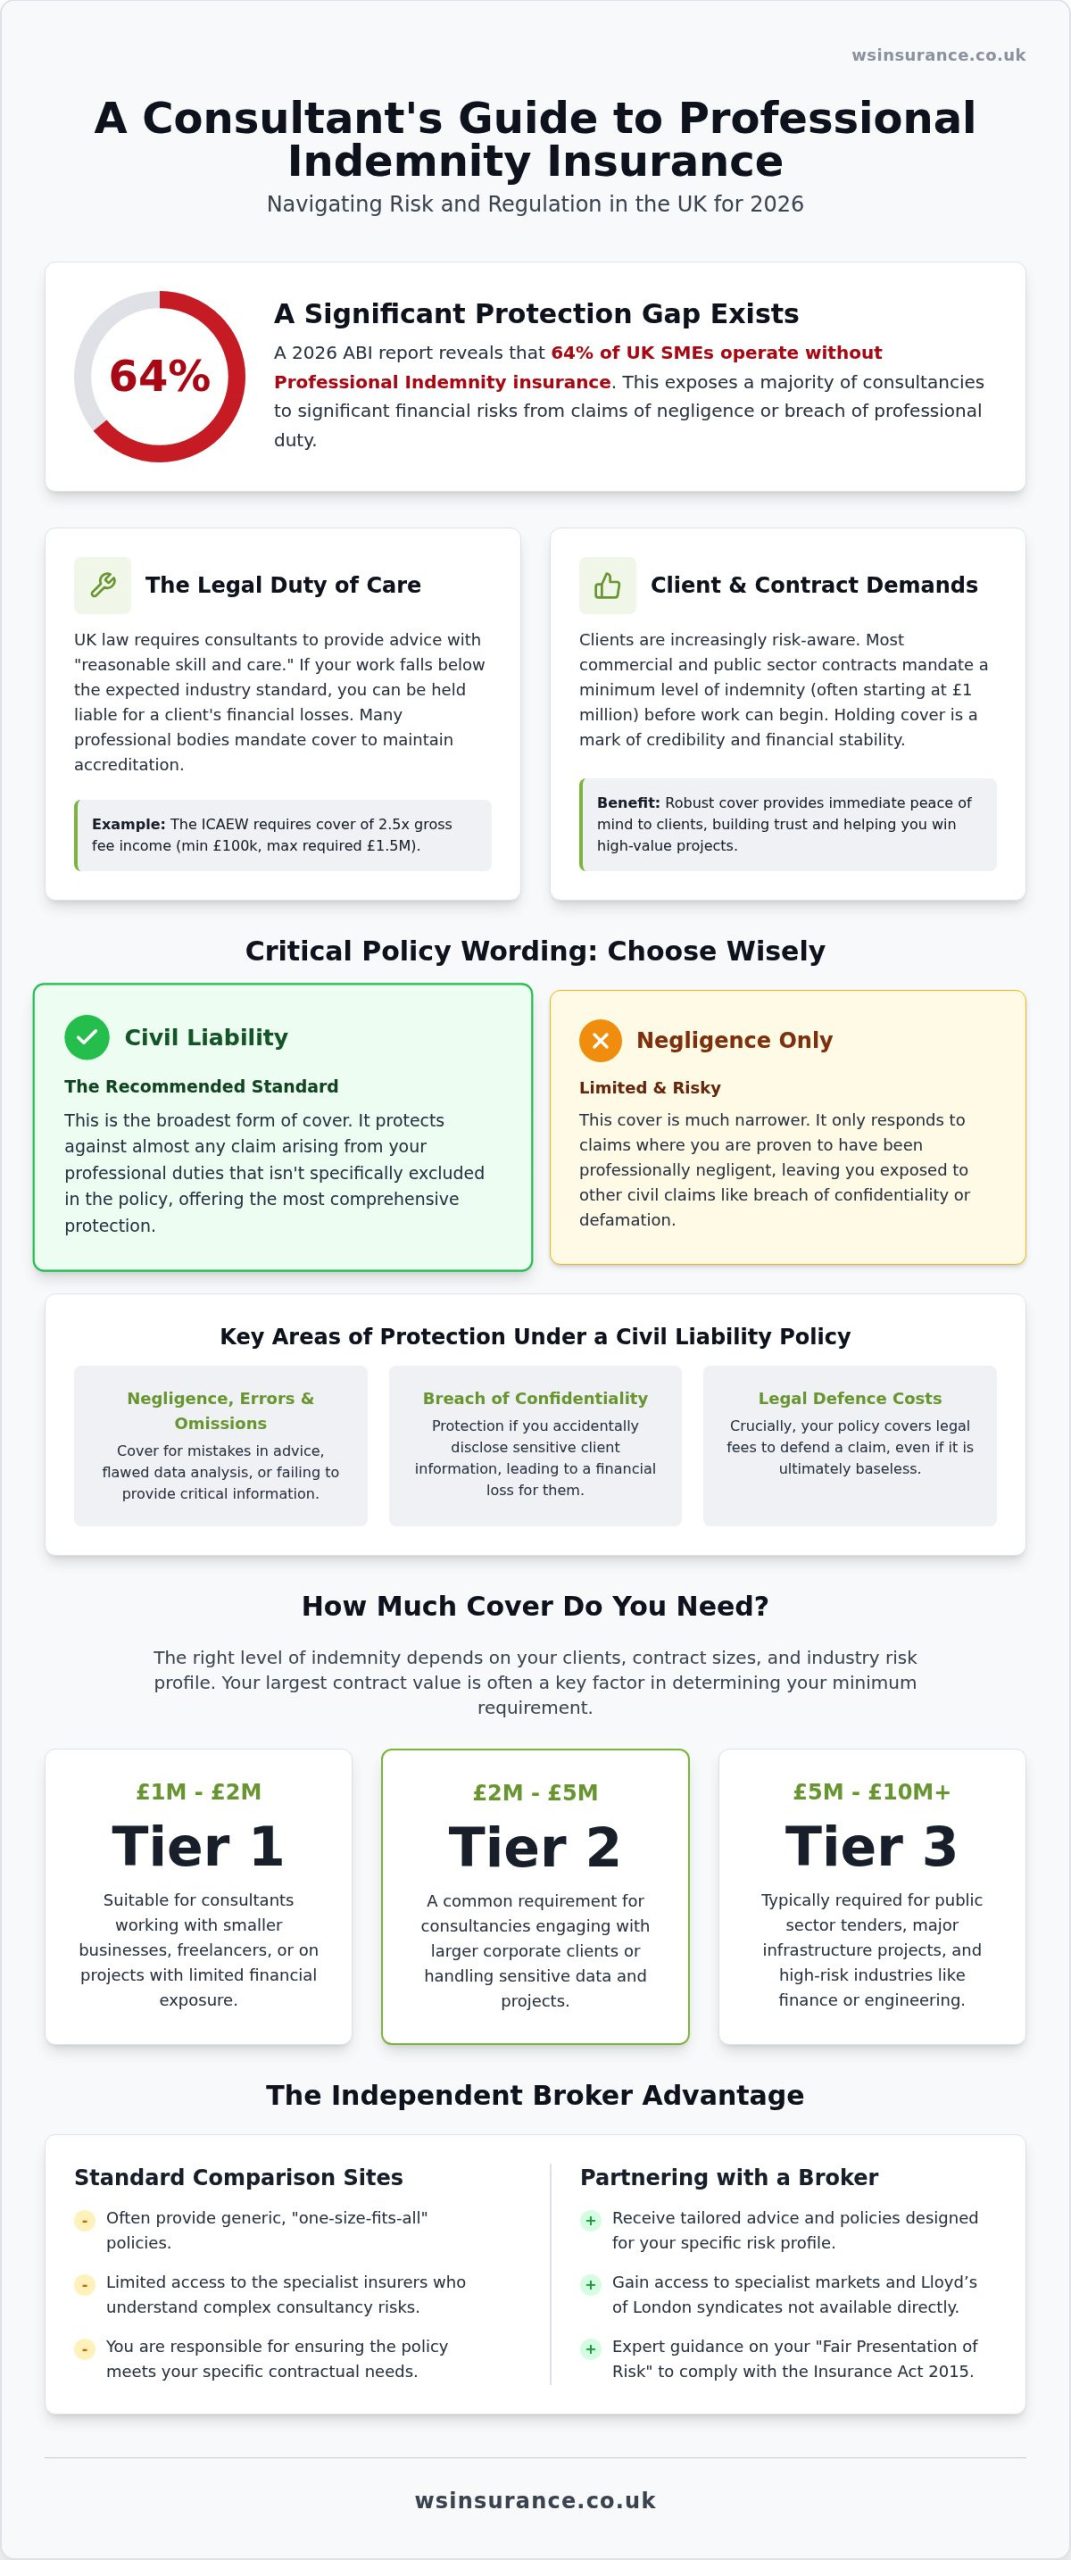
A 2026 report from the Association of British Insurers (ABI) revealed that 64% of UK SMEs still lack professional indemnity insurance, despite the increasing complexity of professional liability. For those seeking professional indemnity insurance for consultants UK, this gap highlights a significant risk to long-term stability. You likely feel the weight of delivering expert advice whilst managing the quiet anxiety of a potential negligence claim. It’s frustrating to face vague contract requirements or dense insurance jargon that seems to obscure the very protection you need to work with confidence.
We believe that securing the right cover should be a transparent process that empowers your business rather than complicates it. This guide is designed to act as your expert pathfinder, showing you how to obtain tailored solutions that meet both regulatory standards and your specific risk profile. We’ll look at the shift in 2026 premiums, the convergence of cyber risks, and the vital role of “claims-made” policy structures. By the end, you’ll have a clear roadmap to robust protection, allowing you to focus on your clients whilst we help manage the risks behind the scenes.
Key Takeaways
- Understand why consultants are held to a higher standard of care and how to navigate the professional indemnity insurance for consultants UK market in 2026.
- Learn the critical distinction between “negligence only” and “civil liability” wording to ensure your policy covers a broader range of professional risks.
- Discover how to calculate the correct level of indemnity, ranging from £1 million to over £10 million; your largest contract often dictates your minimum requirements.
- Master the “Fair Presentation of Risk” to streamline your application and ensure your consultancy remains compliant with the Insurance Act 2015.
- Find out how partnering with an independent broker provides access to specialist Lloyd’s syndicates that simply aren’t available on standard comparison sites.
What is Professional Indemnity Insurance for Consultants?
Professional indemnity insurance for consultants UK is a specialised policy designed to protect your business when your expert advice doesn’t go to plan. Professional indemnity insurance serves as the ultimate shield against claims of professional negligence or breach of duty. For a consultant, the “product” isn’t a physical structure or a tangible item; it’s the intellectual value and strategic guidance you provide. This distinction is vital because professional risks are often invisible until a client suffers a financial loss based on your recommendations. To understand the broader context of What is Professional Indemnity Insurance?, one must recognise it as the primary defence for any knowledge-based business.
Unlike a contractor providing a physical service, such as a plumber or electrician, your liability stems from what you say or write. A miscalculated projection or a flawed strategy can lead to significant financial ruin for your client, even if no physical harm occurs. This intellectual liability is why standard business insurance often falls short, necessitating a bespoke policy that addresses the specific nuances of your sector whilst removing the uncertainty that comes with professional practice.
The Legal Duty of Care for UK Professionals
UK law holds professionals to a benchmark known as “reasonable skill and care.” If your work falls below the standard expected of a competent peer in your field, you could be held liable for the resulting damages. Many professional bodies mandate specific levels of cover to maintain your accreditation. For instance, the ICAEW requires members to hold cover equal to 2.5 times their gross fee income, with a minimum of £100,000 and a maximum required limit of £1.5 million. Without this protection, the financial burden of a negligence claim falls entirely on your consultancy. This includes not just the compensation itself, but also the potentially crippling legal fees required to defend your reputation.
Contractual Requirements and Client Expectations
What Does Professional Indemnity Cover for Consultancy Businesses?
Professional indemnity insurance for consultants UK provides more than just a safety net for professional mistakes; it offers a structured defence against a range of civil liabilities. When selecting a policy, it’s vital to look for “civil liability” wording. This is significantly broader than “negligence only” cover, as it encompasses almost any claim arising from your professional duties that isn’t specifically excluded. By choosing this wider scope, you’re effectively removing the uncertainty that often surrounds complex legal disputes.
One often overlooked benefit is the coverage of legal defence costs. In many cases, the cost of expert legal representation and court fees far exceeds the actual settlement or compensation awarded. Even if a claim is entirely groundless, the financial burden of proving your innocence can be devastating without a robust policy in place. Your insurer acts as a shield, managing the litigation process whilst you focus on delivering your expertise to other clients.
Negligence, Errors, and Omissions
Professional negligence occurs when your advice fails to meet the expected industry standard, leading to a client’s financial loss. However, “omissions” are just as critical. This involves failing to provide essential information or neglecting to take a necessary action. For example, a management consultant might overlook a key regulatory requirement in a strategic report, leading to a significant fine for their client. Errors in complex data analysis or simple calculation mistakes are also covered, ensuring that a single oversight doesn’t result in business closure.
Breach of Confidentiality and Defamation
As a consultant, you handle sensitive corporate data daily. Accidental disclosure of this information can lead to severe legal action. PI insurance protects you against these breaches and also covers unintentional defamation, such as libel or slander, whilst you represent a client’s interests. This protection often works in tandem with cyber and data breach insurance to provide a comprehensive shield against modern digital risks. It’s about protecting your reputation as much as your bank balance.
Loss of Documents and Data
Whether it’s physical files or digital records, losing client documents can halt a project and incur massive restoration costs. This policy extension covers the expenses involved in replacing or restoring lost or damaged records. In the 2026 landscape, where data is a primary asset, this support is essential for maintaining business continuity after a loss. Selecting the right extensions requires a deep understanding of your specific consultancy niche. You might find it beneficial to consult an independent broker who can identify these subtle risks and tailor a policy that removes all doubt from your professional protection.
Calculating the Correct Level of Cover: Limits and Indemnity Types
Selecting the right limit for professional indemnity insurance for consultants UK requires more than just picking a round number. In 2026, the cost of litigation and professional settlements has seen a steady rise, driven by inflationary pressures on legal fees and expert witness costs. A limit that seemed robust two years ago might now leave your consultancy exposed. Your largest single contract should always serve as the absolute floor for your cover level. If you’re advising on a project worth £2 million, a £1 million policy is fundamentally inadequate; it fails to meet the basic expectations of most commercial clients and leaves your personal or business assets at risk.
This calculation must also account for the potential “consequential loss” your client might suffer. This isn’t just the cost of fixing your mistake, but the financial ripple effect it has on their entire operation. We help you look beyond the immediate fee to understand the true scale of your professional exposure, ensuring that your shield is thick enough to withstand a worst-case scenario.
Any One Claim vs. Aggregate Limits
The structure of your policy payout is as critical as the total amount. You’ll typically choose between two main types of limits:
- Any One Claim: This provides the full limit of indemnity for every individual claim made during the policy year. If you hold a £2 million policy and face three separate, unrelated claims, you have £2 million available for each.
- Aggregate: This acts as a single “pot” of money for the entire year. Once the total cost of all claims reaches the limit, the cover is exhausted.
Consultants managing multiple high-value clients should prioritise Any One Claim wording. It removes the anxiety of a single large dispute draining the resources needed to defend against a second, unrelated issue later in the year. While aggregate policies can sometimes be cheaper, the peace of mind offered by per-claim limits is often worth the modest increase in premium.
Assessing Your Maximum Possible Loss
Estimating potential damage requires a methodical look at your client base and the nature of your advice. A small error in a data migration strategy or a flawed financial projection can lead to losses that far exceed your annual turnover. By working with experienced insurance brokers, you can benchmark your cover against industry peers and ensure your protection matches the actual scale of your risk. This consultative approach eliminates the guesswork, allowing you to deliver expert advice whilst knowing your consultancy’s future is secure.
Navigating the Application: Essential Risk Management for Consultants
Securing professional indemnity insurance for consultants UK requires a methodical approach to risk disclosure. Under the Insurance Act 2015, you have a legal duty to make a “Fair Presentation of Risk.” This means providing every material circumstance that would influence an underwriter’s decision. It’s not merely about filling in a form; it’s about building a transparent narrative of your consultancy’s operations. Providing thorough, accurate data ensures that your policy remains a reliable shield when a dispute arises, removing any doubt about your cover’s validity.
Insurers look for evidence that you understand your own professional exposures. By presenting a clear picture of your client base, contract values, and historical claims, you position yourself as a diligent professional. This transparency is the foundation of a partnership where the insurer’s protection matches your actual operational needs.
Retroactive Dates and Claims Made Basis
Professional indemnity is unique because it’s written on a “claims-made” basis. This means the policy in force at the time a claim is brought against you is the one that responds, regardless of when the actual work was performed. To protect against errors in your past projects, your policy schedule will include a “Retroactive Date.” This is the date from which your continuous cover began. If you switch insurers, you must ensure this date is maintained. Failing to do so creates a “coverage gap,” leaving you personally liable for work completed before the new policy started.
The Necessity of Run-off Cover
Your liability doesn’t vanish the moment you stop trading or enter retirement. In the UK, the standard limitation period for professional negligence claims is six years. Consequently, you should maintain “run-off” cover for at least this duration after your consultancy closes. This protection acts as a final safeguard for your legacy and personal assets. While it represents an ongoing cost, the alternative is facing a high-value litigation claim without any corporate protection or legal support during your retirement.
Reducing Premiums through Risk Mitigation
Insurers reward consultants who demonstrate robust internal quality controls. Using clear engagement letters and detailed terms of business reduces the likelihood of misunderstandings that lead to claims. Implementing peer review processes for high-stakes advice shows underwriters that you’re a lower-risk prospect. Often, integrating your PI into broader business insurance packages can offer superior value compared to standalone products. If you’re ready to secure a policy that reflects your commitment to excellence, you can request a bespoke consultancy quote today to begin your application with confidence.
Why Partnering with an Independent Broker Secures Your Consultancy
Choosing the right professional indemnity insurance for consultants UK is rarely as simple as clicking a button on a comparison site. While direct insurers offer convenience, they’re restricted to their own products, which may not align with the complex reality of your specific consultancy. WS Insurance Brokers acts as your expert guide, searching the entire breadth of the market to find a policy that fits you perfectly. We provide access to “broker-only” markets and specialist Lloyd’s syndicates that remain invisible to automated algorithms. This autonomy ensures that our loyalty remains with you, the client, rather than any single insurance provider.
A generic online questionnaire often fails to capture the nuances of your professional risk. It might overlook a specific contract requirement or apply a broad exclusion that leaves you vulnerable. By building a tailored risk profile, we remove the uncertainty of “off-the-shelf” cover. Our role is to act as a shield, ensuring that the precision required for your financial security is balanced with a consultative approach that prioritises your long-term safety.
Bespoke Placement vs. Off-the-Shelf Policies
Standardised policies often contain hidden traps in the form of dangerous exclusions. For example, a basic policy might exclude vicarious liability or fail to address specific IR35 implications mentioned in your contracts. WS Insurance Brokers identifies these gaps by meticulously reviewing your specific engagement letters and matching them with the right policy wording. This level of customisation is what distinguishes a professional placement from a simple commodity purchase. By tailoring the wording to your unique consultancy, we eliminate the doubt that can arise when a generic policy is tested by a complex claim.
Ongoing Advocacy and Claims Support
The true value of a broker is most visible when things go wrong. If a client makes a notification against you, you won’t be left to deal with an impersonal call centre. We provide dedicated claims advocacy, acting as your steady hand during a potentially stressful dispute. Our team manages the communication with the insurer, ensuring your reputation is protected whilst pushing for a fair and efficient resolution. This ongoing support is a core part of our commitment to your business’s resilience. If you’re looking to strengthen your entire risk strategy, consider requesting a review of your broader commercial protection to ensure every aspect of your operation is equally secure.
Securing Your Consultancy’s Future in 2026
Securing robust professional indemnity insurance for consultants UK is a strategic investment in your professional reputation. We’ve explored how “Any One Claim” structures provide superior protection for high-value portfolios and why maintaining run-off cover is essential for your long-term peace of mind. By focusing on “civil liability” wording and precise retroactive dates, you can eliminate the gaps that often plague generic, off-the-shelf policies.
Our role as an independent broker is to act as your shield, providing transparent access to the entire market including specialist Lloyd’s syndicates. As an FCA authorised and regulated firm, we prioritise your security through diligent risk placement and dedicated UK-based claims support. You don’t have to navigate these complexities alone.
Request a bespoke Professional Indemnity quote from our expert brokers today to ensure your consultancy is protected by a policy as professional as the advice you deliver. We look forward to helping you build a resilient future with absolute confidence.
Frequently Asked Questions
Is professional indemnity insurance a legal requirement for UK consultants?
Professional indemnity insurance isn’t a universal legal mandate for every consultant, but it’s a regulatory requirement for professions like solicitors and architects. For others, it’s almost always a contractual necessity. Clients and professional bodies often set minimum limits, such as the ICAEW’s requirement of 2.5 times gross fee income. Failing to maintain cover can result in a breach of contract or loss of professional accreditation, even if the law doesn’t strictly demand it.
How much does professional indemnity insurance cost for a consultant in 2026?
Premiums for professional indemnity insurance for consultants UK vary based on your specific risk profile, fee income, and required indemnity limit. Factors such as your industry niche and claims history significantly influence the final cost. While some low-risk professionals might find entry-level cover affordable, those in high-stakes sectors like management or IT consultancy typically pay more to reflect their potential exposure. We recommend a bespoke assessment to determine an accurate premium for your consultancy.
What is the difference between public liability and professional indemnity?
Public liability covers physical risks, such as a client tripping over a cable in your office or you damaging their property during a visit. In contrast, professional indemnity protects against financial losses resulting from your professional advice or services. If your strategy leads to a client’s loss of revenue, PI responds. Most consultants need both to ensure comprehensive protection against the full spectrum of operational risks they face daily.
Does professional indemnity insurance cover work done for international clients?
Forgetting to renew creates a dangerous coverage gap because PI insurance operates on a “claims-made” basis. If your policy lapses, you have no protection for any claims brought against you during that uninsured period, even for work completed years ago. This can also reset your retroactive date, effectively erasing your cover for all past projects. We provide dedicated renewal support to help prevent these oversights and maintain your continuous security.
Can I get professional indemnity insurance if I am a new start-up consultant?
Yes, new start-up consultants can secure cover by providing details of their professional experience and projected fee income. Insurers look at your background in previous roles to assess your risk level. While you won’t have a trading history for the new entity, your personal track record and robust terms of business can help secure competitive terms. Starting with professional indemnity insurance for consultants UK from day one is essential for building trust with your first clients.
What is “Run-off” cover and do I really need it when I retire?
Run-off cover protects you against claims made after your consultancy has stopped trading or you have retired. Since professional negligence claims can be brought up to six years after the work was completed, this protection is vital. It ensures that your personal assets and retirement savings aren’t drained by legal disputes arising from your past professional life. For many, it’s a non-negotiable part of a responsible exit strategy.