
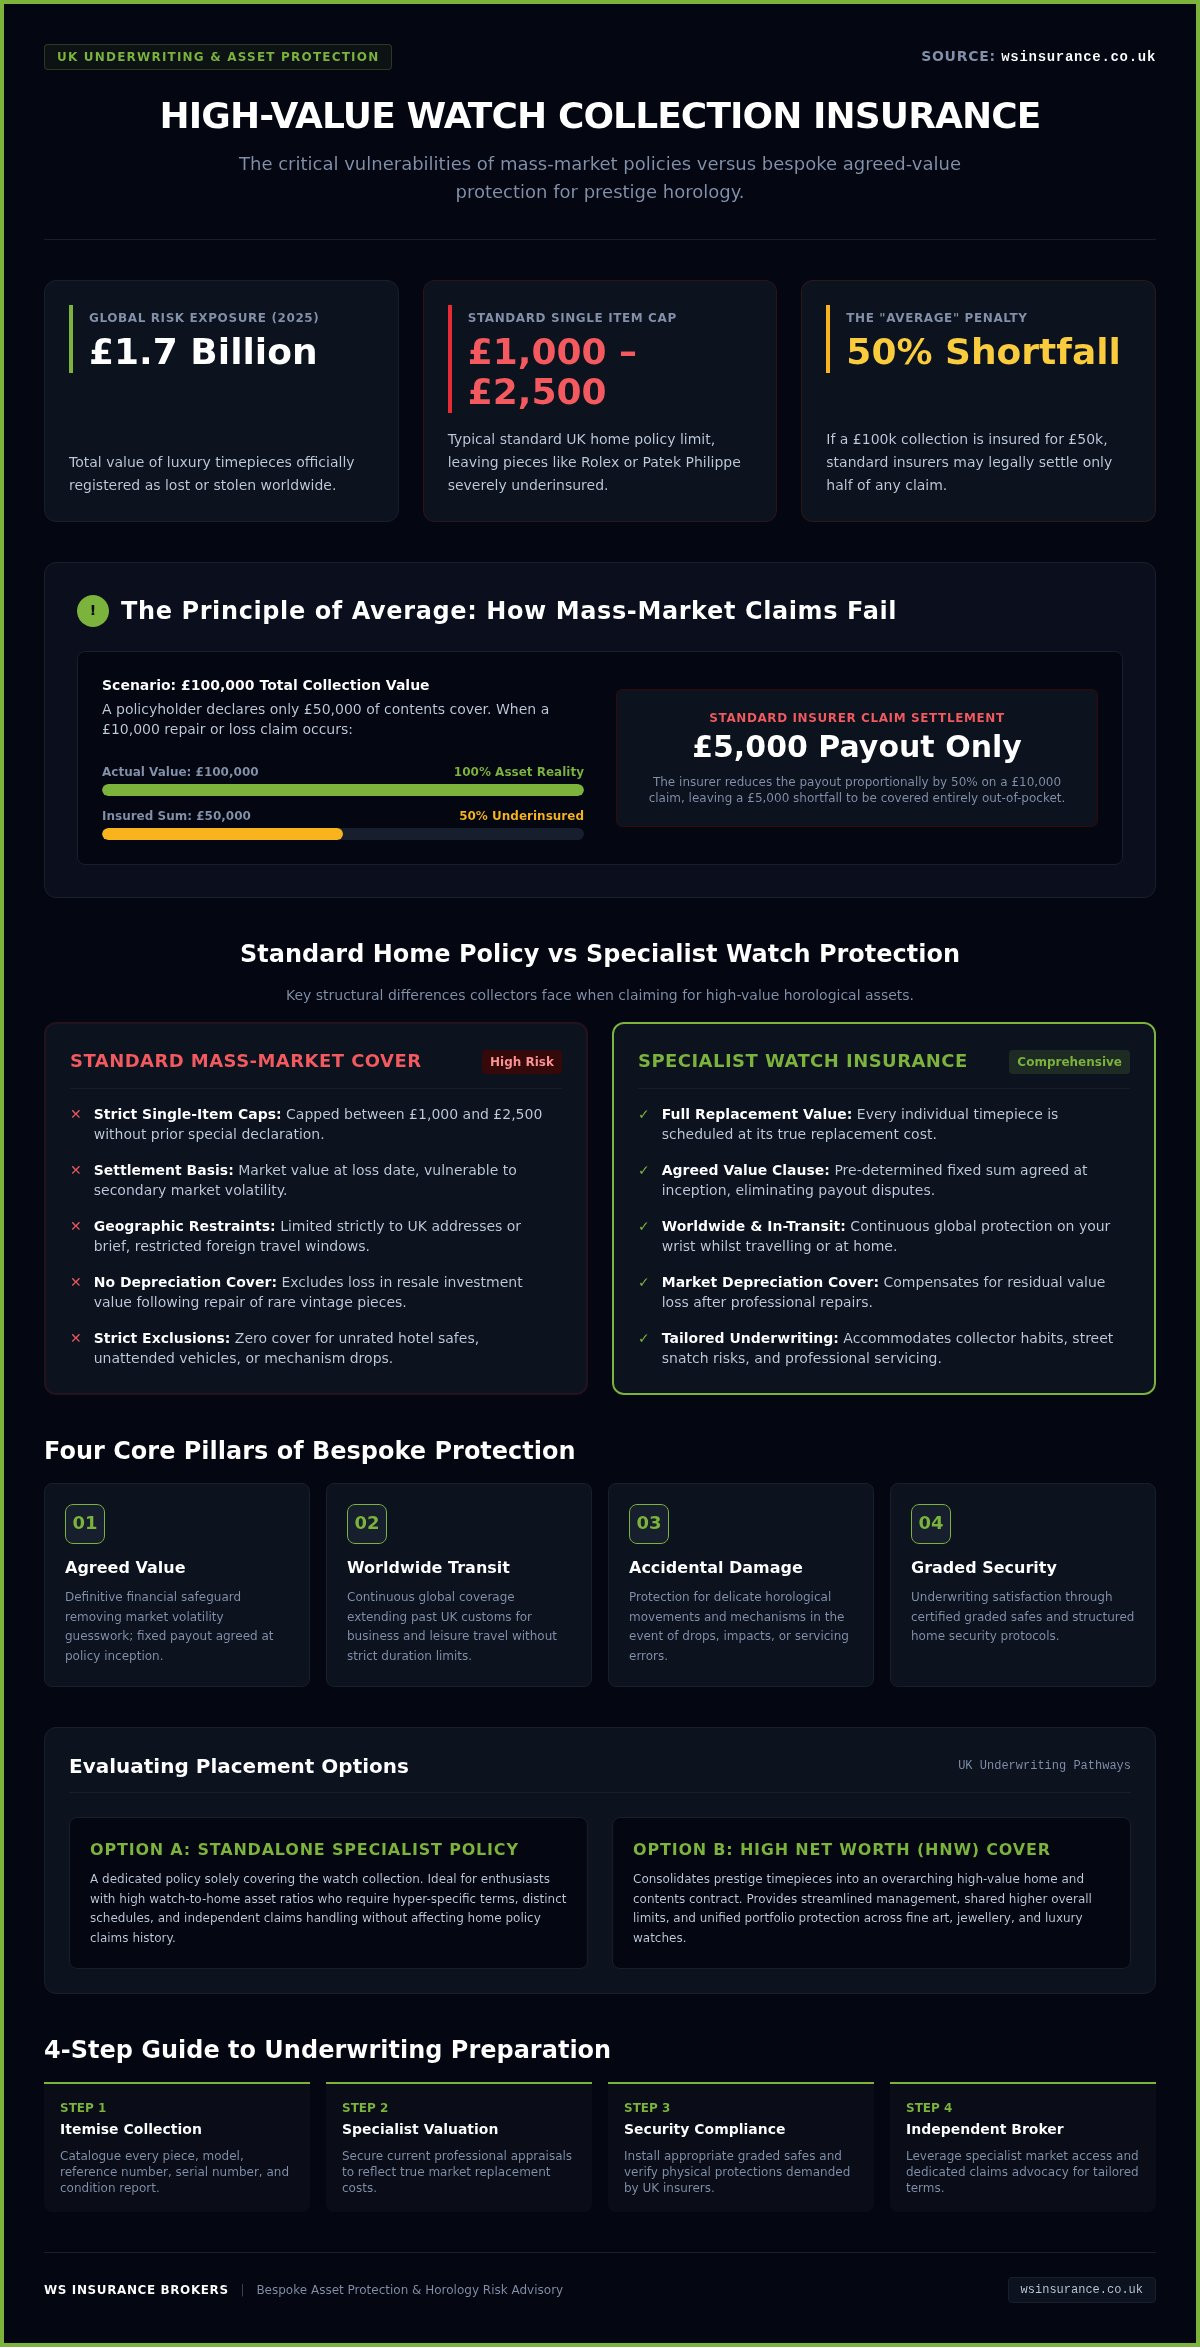
Did you know that the total value of luxury watches registered as lost or stolen globally reached a staggering £1.7 billion in 2025? For UK collectors, this statistic isn’t just a number; it’s a sobering reminder of the rising risks associated with owning prestigious timepieces. You’ve likely spent years curating your portfolio, only to discover that standard home insurance policies often cap single-item limits far below the actual market value of a Rolex or Patek Philippe. It’s frustrating to realise that the protection you thought was sufficient might leave you significantly out of pocket if the worst happens.
This 2026 guide will show you how to secure accurate, comprehensive insurance for a collection of high-value watches whilst avoiding the common pitfalls that trip up many owners. We’ll provide the clarity you need to move from uncertainty to absolute confidence. You’ll learn about the specialist appraisal process, the necessity of agreed value cover, and how an independent broker acts as your expert guide to navigate strict security requirements. By the end, you’ll understand exactly how to build a tailored asset protection strategy that keeps your collection safe, whether it’s in a home safe or worn anywhere in the world.
Key Takeaways
- Understand why standard home contents policies often leave luxury timepieces exposed and how to identify the specific single-item limits that lead to significant underinsurance.
- Discover the essential pillars of specialist insurance for a collection of high-value watches, including the vital importance of agreed value clauses and worldwide accidental damage cover.
- Compare the benefits of standalone specialist policies against High Net Worth Home Insurance to determine which route offers the most comprehensive protection for your total asset portfolio.
- Learn how to satisfy rigorous UK underwriting requirements by organising professional valuations and implementing the specific security measures, such as graded safes, that insurers demand.
- Find out how an independent broker acts as your expert guide, providing access to specialist markets and dedicated advocacy to ensure a seamless claims process if the worst happens.
The Vulnerability of Standard Policies for Luxury Watch Collections
Standard home contents policies are built for the general public, providing broad coverage for everyday furniture and electronics. They aren’t designed for the specific needs of a horology enthusiast. If you rely on a mass-market policy, you’ll likely find significant gaps in your protection that only become apparent when you attempt to make a claim. Many of these policies include a “principle of average” clause. If your total collection is worth £100,000 but you’ve only insured it for £50,000, the insurer might only pay 50% of any claim, even for a minor repair. This leaves you with a substantial financial shortfall that could have been avoided with precise valuation.
Geographical boundaries in standard certificates often restrict coverage to the UK or offer very limited windows for foreign travel. This creates immense risk when you travel abroad with a high-value timepiece on your wrist. Without dedicated Specialist Underwriting to assess the specific risks of your lifestyle, you may find yourself without cover the moment you clear customs at Heathrow. Relying on a standard policy for a collection of high-value watches is a gamble that rarely pays off for the serious collector.
The Pitfalls of Standard Single Item Limits
Most standard UK home insurance policies cap individual item payouts at low thresholds, typically between £1,000 and £2,500. A single premium timepiece, such as a modern Rolex or a Patek Philippe, instantly breaches these mass-market limits. Without declaring each piece individually, you’re essentially self-insuring the majority of your asset’s value. Failing to declare the true total value of your collection doesn’t just limit your payout; it can invalidate your entire policy if the insurer deems the non-disclosure to be a material fact. We work to eliminate this uncertainty, ensuring every piece is listed at its true market replacement cost.
Common Exclusions in Mass-Market Home Insurance
Mass-market policies are riddled with exclusions that don’t suit a collector’s behaviour. Many lack accidental damage cover for delicate horological mechanisms, meaning a dropped watch could result in a total financial loss. You’ll also find strict exclusions regarding watches left in unattended vehicles or even hotel safes that don’t meet specific security ratings. Perhaps most critically, standard policies rarely cover market value depreciation. If a rare vintage piece is damaged and repaired, its resale value often drops significantly. Standard insurance only covers the repair cost, whereas bespoke insurance for a collection of high-value watches can account for the loss in investment value, providing the comprehensive shield your assets deserve.
Essential Features of Insurance for a Collection of High-Value Watches
Specialist policies function as a precise instrument, mirroring the complexity of the timepieces they protect. When you invest in insurance for a collection of high-value watches, you’re buying certainty rather than just a certificate. These bespoke contracts are built on pillars of transparency, ensuring that every scenario, from a snatched watch on the street to a mechanical failure during a professional service, is accounted for. Tailored underwriting removes the anxiety of the unknown by aligning policy terms with your actual lifestyle and collector behaviour.
Agreed Value vs Market Value Protection
Standard policies often settle claims based on the market value at the time of loss. This creates immense anxiety because luxury watch prices are notoriously volatile. Agreed value cover provides a pre-determined payout fixed at the policy’s inception, removing the guesswork from the claims process. Agreed value protection acts as a definitive financial safeguard against the sharp fluctuations of the secondary horological market. This ensures you receive the full sum required to replace a rare piece, regardless of temporary market dips.
Worldwide Cover and Transit Protection
Luxury watches are meant to be worn, not just stored. Specialist policies provide continuous global coverage, meaning your assets are protected whilst you’re travelling for business or leisure. These policies also include specific transit clauses that cover your watches during professional servicing or transport between residences. It’s important to understand safe-keeping requirements; underwriters often mandate that watches are kept in a specific grade of safe when not being worn, even within luxury hotels. If a claim is ever disputed or handled unfairly, you have the right to contact the Financial Ombudsman Service for a free, independent review of your case.
Pairs, Sets, and Parts Depreciation Clauses
The value of a high-end watch often relies on its original components. If a bespoke strap is damaged or a limited-edition box is lost, the overall asset value can plummet. Specialist pairs and sets clauses compensate for this lost total value, going beyond the simple cost of a replacement part. Similarly, depreciation cover protects you against the diminished market value that often follows significant repairs. By working with a broker to tailor your asset protection strategy with WS Insurance Brokers, you ensure these technical nuances are clearly defined before a loss occurs.
Evaluating Your Options: Standalone Policies vs High Net Worth Cover
Choosing the right framework for insurance for a collection of high-value watches depends on the scale of your assets and how you manage your portfolio. You face a strategic choice between a standalone specialist policy and a comprehensive High Net Worth (HNW) solution. Each path offers distinct advantages; the decision ultimately hinges on whether you want to ring-fence your timepieces or integrate them into a broader protective shield. Understanding how a claim on a single watch impacts your wider profile is vital for long-term security.
When to Choose a Standalone Specialist Policy
Specialist standalone insurance for a collection of high-value watches is particularly effective for those whose primary focus is horology. These policies are ideal for collectors with highly active portfolios who frequently buy, sell, or trade. They offer extreme flexibility, allowing for rapid updates to the schedule without impacting other insurance arrangements. If you make a claim on a standalone policy, it won’t affect the no-claims discount on your main home insurance. However, you should be aware that standalone cover is often less efficient regarding premium costs. You aren’t benefiting from the economies of scale that typically accompany portfolio consolidation.
The Advantages of High Net Worth Home Insurance
For many collectors, incorporating timepieces into high net worth home insurance is the most efficient strategy. This approach simplifies asset management by placing buildings, fine art, jewellery, and watches under a single premium and a unified renewal date. By consolidating these items, you often secure more competitive rates and broader worldwide coverage than multiple individual policies could provide. It removes the administrative burden of managing disparate certificates and ensures there are no gaps in protection across your various assets. This integrated method creates a narrative of partnership where your entire lifestyle is protected by a single, steady hand.
We believe in removing uncertainty from this selection process. Whether you choose to isolate your collection or blend it into a wider portfolio, our role is to act as your expert guide. We help you weigh the premium efficiency of a HNW policy against the specific flexibility of standalone terms. This ensures your protection strategy isn’t just a commodity, but a tailored outcome that reflects the true value of your assets. By analysing your specific risk profile, we provide the clarity needed to make a choice that prioritises your long-term financial security over immediate transaction ease.
How to Organise and Prepare Your Collection for Specialist Underwriting
Securing insurance for a collection of high-value watches requires a methodical approach to documentation and risk management. Underwriters don’t just look at the value of your assets; they assess the diligence of the owner. By taking proactive steps to organise your collection, you satisfy rigorous UK underwriting criteria and ensure a smoother path during the placement and claims processes. Impeccable record-keeping acts as a shield between you and the complexities of the market, removing uncertainty before you even sign a policy.
Specialist underwriters look for evidence of thoroughness. A recent report indicates that nearly 35% of luxury watch owners in the UK are underinsured because they haven’t updated their valuations since 2023. We help you avoid this pitfall by identifying the specific documentation required to satisfy the entire breadth of the specialist market. This preparation results in a protective outcome where your long-term security is prioritised over a simple transaction.
Securing Professional Horological Valuations
Original purchase receipts are often insufficient for older luxury timepieces or those bought on the secondary market. Whilst a receipt proves what you paid, it doesn’t reflect the current replacement cost in a volatile economic landscape. Insurers typically require an updated valuation for high-value watches every 2 to 3 years to ensure adequate coverage. These appraisals must come from accredited UK horological valuation specialists who understand the nuances of brands like Rolex or Patek Philippe. Maintaining these regular updates prevents the risk of underinsurance and ensures your agreed value remains accurate.
Meeting Home Security and Safe Requirements
Physical security is a cornerstone of specialist underwriting. Insurers use the Eurograde safe rating system to assess how much cash or jewellery value a safe can protect. A Grade 0 safe, for example, is typically rated for £6,000 in cash or £60,000 in valuables, whereas higher grades are required for more substantial collections. Beyond physical safes, underwriters often mandate professionally installed, monitored alarm systems linked to central stations. You must also adhere to specific safe-keeping clauses; these dictate that watches must reside within the safe whenever they aren’t being worn. If you want to ensure your security measures meet these strict standards, speak with a specialist broker today to review your current arrangements.
Designing Bespoke Protection via an Independent Insurance Broker
Partnering with a professional broker eliminates the friction and uncertainty often associated with luxury asset protection. Automated online comparison engines are designed for standardized, mass-market products; they cannot interpret the specific risks of a high-value horological portfolio. A broker acts as an expert guide, building a tailored risk profile that accommodates your unique collector lifestyle. This consultative relationship ensures that your insurance for a collection of high-value watches functions as an accurate shield rather than a generic commodity.
The true value of a broker becomes evident when navigating the complexities of the broader market. Instead of pushing you toward a restricted panel of providers, an independent brokerage leverages its autonomy to find the precise cover your assets require. This proactive labour directly results in your peace of mind, knowing that your security is backed by deep industry expertise.
Navigating the Whole of Market for Collectors
Accessing specialist, broker-only syndicates allows you to unlock superior policy wording that direct consumers cannot reach easily. These niche underwriters understand horology and are willing to offer flexible terms that accommodate real collector behaviour. By working with independent insurance brokers, you avoid the generic, restrictive policies that leave luxury timepieces exposed. Your risk placement strategy is customized to your exact needs, ensuring that rare references and appreciating assets are fully protected globally.
Proactive Policy Management and Claims Advocacy
Your collection isn’t static; it grows and changes as you acquire new pieces or capitalise on market opportunities. Brokers manage these mid-term adjustments seamlessly, ensuring new purchases are covered instantly without administrative delays. If you ever need to make a claim, your broker acts as your personal advocate, standing between you and the insurer to guide you through the sensitive process. This dedicated advocacy ensures a fair settlement, allowing you to focus on preserving your horological legacy. If you’re ready to remove doubt from your asset protection strategy, contact WS Insurance Brokers today to secure your collection with absolute certainty.
Securing Your Horological Legacy for the Future
Standard home insurance isn’t built for the precision and fluctuating value of luxury timepieces. We’ve explored how moving beyond mass-market caps toward agreed value protection ensures your assets are shielded against secondary market volatility. By organising professional valuations and meeting Eurograde safe requirements, you transition from a position of risk to one of absolute certainty regarding your insurance for a collection of high-value watches.
As an independent broker, we provide whole-of-market access to specialist underwriters, ensuring your unique lifestyle is fully accommodated. WS Insurance Brokers is authorised and regulated by the Financial Conduct Authority (FCA), offering you a steady hand and dedicated personal advocacy during the claims process. You don’t have to navigate these complexities alone. Remove uncertainty from your asset protection strategy by contacting us for a bespoke consultation today. We’re here to ensure your collection remains protected for the long term.
Frequently Asked Questions
Will my standard home insurance cover a luxury watch worth over five thousand pounds?
Standard home insurance usually won’t cover a luxury watch worth over five thousand pounds unless you’ve specifically declared it as a named item. Most mass-market policies have a single-item limit between £1,000 and £2,500 for valuables. If you haven’t listed the watch individually, you’ll likely face a significant shortfall if you need to claim. We recommend checking your policy schedule to ensure your high-value assets aren’t underinsured.
What is an agreed value clause in watch collection insurance?
An agreed value clause establishes a fixed payout amount at the start of your policy, removing the uncertainty of market fluctuations. Unlike standard “market value” settlements that vary based on secondary market prices, this clause guarantees you’ll receive the specific sum stated on your certificate. It’s a cornerstone of specialist insurance for a collection of high-value watches, providing collectors with absolute certainty that they can replace rare pieces without financial loss.
How often should I have my luxury watch collection valued for insurance purposes?
You should have your luxury watch collection professionally valued every two to three years to maintain accurate protection. The secondary market for brands like Rolex and Patek Philippe is notoriously volatile, often resulting in rapid price changes that outpace standard inflation. Regular appraisals from accredited UK horological specialists ensure your policy reflects the current replacement cost. This proactive approach prevents underinsurance and ensures your agreed value remains aligned with true market conditions.
Am I covered if my high-value watch is stolen whilst I am abroad?
You’re typically covered for theft abroad if your policy includes “all-risks” worldwide protection, which is standard in specialist and high-net-worth certificates. Unlike basic home insurance that might restrict cover to the UK, these tailored policies protect your timepieces whilst you’re travelling for business or leisure. It’s vital to review any safe-keeping requirements, as insurers often mandate that watches are kept in a hotel safe when you aren’t wearing them.
What security measures do UK insurers require for high-value watch collections?
UK insurers typically require a combination of physical and electronic security for high-value collections. This usually involves a professionally installed Eurograde safe, with the specific grade determined by the total value of your assets. Additionally, you’ll likely need an intruder alarm system that’s monitored by a central station and maintained under a professional contract. These measures help mitigate risk, which can lead to more favourable premium terms and lower excess amounts.
Can I insure my watches alongside my fine art and high-value property?
You can certainly insure your watches alongside fine art and high-value property through a comprehensive High Net Worth Home Insurance policy. This integrated approach simplifies your asset management by consolidating all your prestigious possessions under a single premium and renewal date. It often proves more cost-effective than managing multiple standalone certificates. Our role is to source a portfolio solution that provides seamless protection across your entire collection of assets.
What happens if only one part of a rare watch set is damaged or lost?
If only one part of a rare watch set is damaged or lost, a specialist “pairs and sets” clause ensures you’re compensated for the loss in total value. For instance, losing a bespoke limited-edition strap or a unique presentation box can significantly diminish the market value of the entire asset. Instead of just paying for a replacement part, the insurer acknowledges the depreciation of the set, providing a payout that reflects the collective loss.