
What if the centrepiece of your collection, a work of art you’ve curated over decades, was suddenly valued at just £2,000 by your insurer because of a hidden single article limit? This is a sobering discovery that often comes far too late. You’ve spent years meticulously building a legacy, and it’s only natural to feel anxious about whether a standard home policy truly understands the nuances of the 2026 art market. Fluctuating valuations and the complexities of the claims process for unique items can leave even the most seasoned collectors feeling exposed and underinsured.
This guide will show you how to secure your private assets with specialist art collection insurance UK that provides comprehensive protection for the full market value. We’ll explore how expert guidance on restoration, defective title, and bespoke risk placement ensures your masterpieces remain a secure part of your family’s future. You’ll discover how the right professional partnership removes the uncertainty of the selection process, providing the steady hand you need to protect your collection’s financial and cultural value for the long term.
Key Takeaways
- Learn why standard home contents policies often fail collectors due to restrictive single article limits and why specialist art collection insurance UK is essential for high-value pieces.
- Understand the critical distinction between Market Value and Agreed Value. This ensures your settlement is fixed and undisputed should you need to claim.
- Explore specialist protection features like Defective Title cover and “Death of the Artist” clauses that account for sudden market fluctuations.
- Identify the environmental and physical security standards, such as humidity controls and specialist hanging systems, necessary to safeguard your collection’s physical condition.
- Discover the benefit of using an independent broker to access a broad panel of specialist insurers and secure bespoke advocacy throughout the life of your policy.
The Limitations of Standard Home Insurance for UK Art Collections
Whilst a standard residential home insurance policy provides a necessary safety net for general household contents, it often lacks the precision required for high-value assets. Most off-the-shelf policies are designed for replaceable commodities rather than unique masterpieces. For a collector in 2026, relying on basic cover creates a significant risk of underinsurance as market values fluctuate. Specialist art collection insurance UK is designed to bridge this gap, offering protection that respects the unique nature of your acquisitions.
The “Single Article Limit” Trap
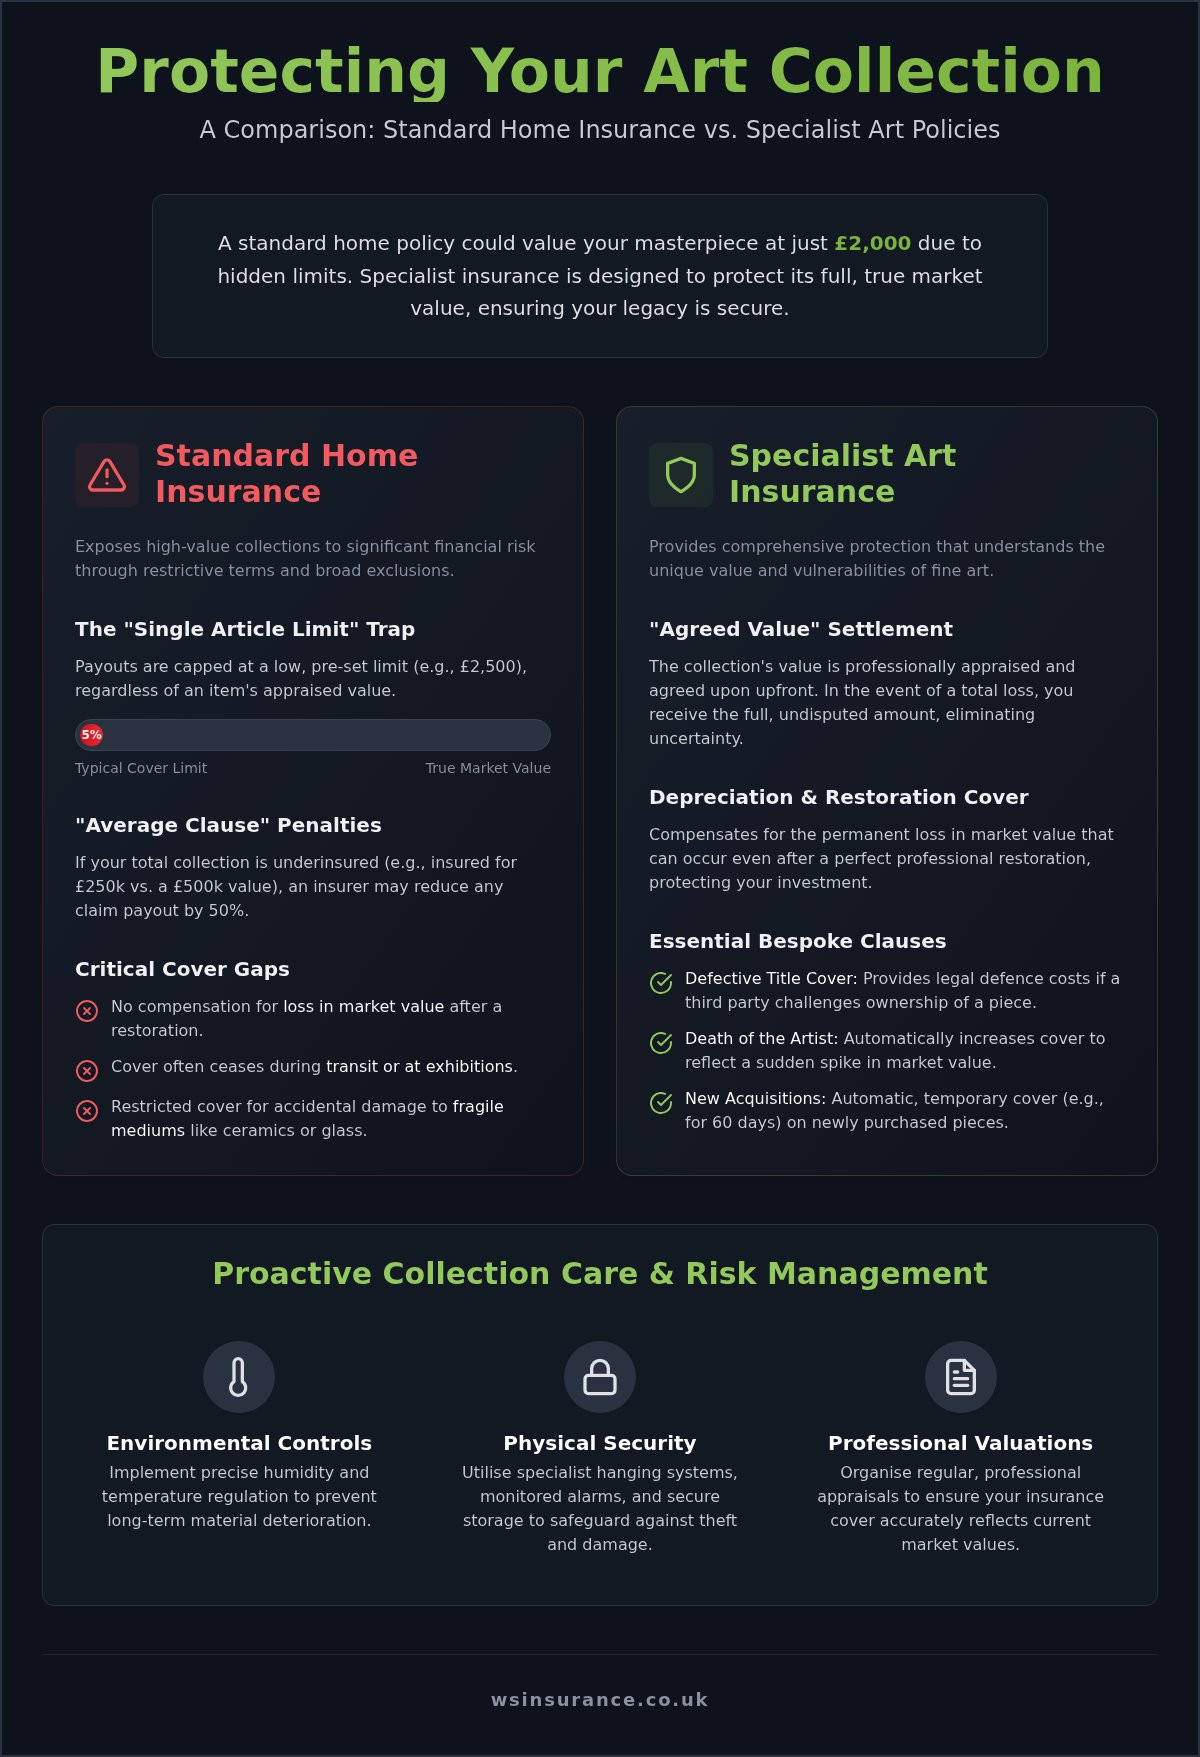
Many standard providers impose a restrictive “single article limit”, typically ranging between £2,500 and £5,000. Any item exceeding this value must be specifically declared; otherwise, the payout is capped at that limit regardless of the item’s true worth. This is particularly dangerous when combined with “average clauses”. If your total collection is valued at £500,000 but you’ve only insured your contents for £250,000, an insurer may reduce any claim by 50% to reflect the underinsurance. Understanding Art valuation principles is vital here. Without professional appraisals and specific declarations, you might unknowingly leave your legacy exposed to financial shortfalls.
Exclusions You Need to Know
General policies often contain broad exclusions that leave fragile mediums vulnerable. For instance, damage occurring during professional cleaning or restoration is rarely covered. If a restorer accidentally damages a canvas, a standard policy will likely reject the claim. Specialist art collection insurance UK acts as a shield against these vulnerabilities by providing bespoke terms that standard policies overlook.
- Lack of depreciation cover: Standard insurers pay for the physical repair but won’t compensate you for the resulting loss in market value after a restoration.
- Transit gaps: Cover often stops at your front door, leaving items unprotected whilst moving between residences or to an exhibition.
- Fragile medium restrictions: Accidental damage cover for glass, ceramics, or delicate installations is frequently omitted or heavily restricted in basic policies.
A specialist policy ensures that the cultural and financial legacy of your collection isn’t compromised by fine-print exclusions designed for mass-produced goods. It provides the steady hand needed to manage the complexities of a modern collection with confidence.
Specialist Art Insurance: Features That Protect Your Legacy
Moving beyond the basic coverage discussed previously, art collection insurance UK offers sophisticated clauses designed for the complexities of the 2026 market. These features don’t just protect the canvas; they protect your financial interest in the asset. One such essential feature is “Restoration and Loss of Value” cover. If a sculpture is chipped or a painting is torn, a standard policy pays for the physical repair. A specialist policy goes further. It compensates you for the permanent depreciation in market value that inevitably follows even the finest professional restoration work.
Active collectors also benefit from “New Acquisitions” cover. This provides a 60-day grace period where newly purchased items are automatically insured, typically for up to 25% of the total sum insured. It allows you to bid at auction with the confidence that your new masterpiece is protected from the moment the hammer falls. Staying informed through Specialist art insurance news reveals how often sudden market shifts or legal challenges can impact private collections, making these bespoke features indispensable.
Defective Title and Legal Advocacy
Provenance disputes can emerge years after a purchase, even when you have performed rigorous due diligence. Defective Title cover acts as a shield, providing legal defence costs if a third party claims ownership of a piece in your collection. If the claim is successful, the policy reimburses the purchase price. As your independent advisor, we act as a steady hand during these high-stakes negotiations. We coordinate with legal experts and insurers to resolve the dispute, removing the uncertainty and financial strain from your shoulders.
The “Death of the Artist” Clause
The market for contemporary British art often sees a sharp spike in prices immediately following an artist’s passing. Specialist UK insurers include a clause that provides a significant uplift in the sum insured, often 100% to 200%, for a set period after the death. This ensures you aren’t left underinsured during a period of rapid market appreciation. Our role as your broker is to ensure this clause is triggered correctly. We provide the insurer with the necessary market data and revised valuations to reflect the new reality. This proactive advocacy ensures your legacy remains secure without you needing to monitor daily market fluctuations.
Navigating Art Valuations: Market Value vs. Agreed Value
The valuation of a masterpiece is not a one-time event; it is a continuous process that underpins the integrity of your art collection insurance UK. In a market as dynamic as 2026, the method you choose to value your assets determines the ease of your claims process. Whilst the UK Government Indemnity Scheme provides a non-commercial alternative for works on loan to public institutions, private collections require a commercial policy based on precise, professional appraisals. Relying on an outdated purchase price or an informal estimate creates a gap that insurers may exploit during a loss.
Why “Agreed Value” is the Collector’s Choice
Specialist appraisers, who often charge between £120 and £180 per hour for experienced professionals, provide the documented evidence needed to satisfy both insurers and HMRC. For those managing a diverse portfolio of assets, our High Net Worth Home Insurance guide offers further insights into how these valuations integrate into a broader strategy of bespoke property protection. We act as your expert guide, coordinating with top-tier valuers to ensure your documentation is robust, transparent, and current.
Risk Management and Security for Private Collections
Effective risk management for a private collection involves more than just a sturdy lock. It requires a holistic approach that addresses the subtle, silent threats to your assets. Whilst physical theft is a primary concern, environmental factors often pose a greater risk to the long-term viability of your art collection insurance UK. A comprehensive strategy ensures that you meet the stringent underwriting requirements of specialist providers whilst preserving the cultural legacy of your pieces. It acts as a shield between your collection and the complexities of environmental degradation.
Climate and Light Control
Gradual deterioration is a standard exclusion in almost every policy. This means that damage caused by fluctuating humidity or excessive UV exposure isn’t covered. For delicate works on paper or organic sculptures, maintaining a stable relative humidity, typically between 40% and 60%, is essential to prevent warping or mould growth. Light damage is cumulative and irreversible. Utilising UV-filtering glass and controlled LED lighting isn’t just a best practice; it’s a method of claim prevention that keeps your collection in pristine condition. By controlling these variables, you eliminate the doubt that your pieces will retain their physical and financial integrity over decades.
Physical Security and Theft Prevention
Specialist insurers often include “minimum security requirements” in the fine print. These may mandate specific alarm grades, dual-path monitoring, or specialist hanging systems that prevent the “snatch and grab” of smaller works. Meeting these benchmarks is a core component of a robust art collection insurance UK strategy. A digital inventory with high-resolution photographs and provenance records serves as your ultimate backup. It allows for rapid identification and recovery efforts should the unthinkable happen, ensuring that the claims process remains as smooth as possible.
Fire prevention is equally critical, especially as climate change increases the frequency of extreme weather events that can impact property safety. Recent trends in 2026 show insurers applying stricter underwriting and higher deductibles for homes in high-risk zones. We recommend installing aspirating smoke detection systems that can detect a fire in its earliest stages. As your expert guide, we conduct site visits to identify vulnerabilities that automated systems might miss. This proactive labor results in a tailored security profile that removes the anxiety of the selection process and secures your legacy.
To ensure your property meets the highest standards of protection, contact us for a bespoke risk assessment.
Why Consult an Independent Broker for Your Art Insurance?
In a market where many providers are restricted to a single set of products, the value of independence cannot be overstated. An independent broker acts as a shield between you and the complexities of the broader insurance market. By accessing a wide panel of specialist UK insurers, we ensure that your art collection insurance UK is placed based on merit rather than a limited inventory. This autonomy allows us to be fiercely loyal to your interests. We identify hidden risks in your current arrangements, such as inadequate limits or overlooked transit requirements, ensuring that your protection is as robust as it is transparent.
The Advantage of Autonomy
The distinction between a restricted agent and an independent broker is fundamental to your long-term security. A restricted agent is bound to a single provider’s appetite and pricing models; conversely, our status as an independent brokerage allows us to survey the entire breadth of the market. This creates a narrative of partnership where our proactive labor results in your ease and confidence. We scrutinise policy wording with clinical precision to eliminate the doubt often found in generic contracts. This diligent approach ensures that your legacy is protected by the most appropriate specialist terms available in 2026.
A Personal Approach to Professional Protection
Managing a significant collection requires more than just a policy; it requires a relationship with a professional who understands the evolution of your assets. Having a single point of contact removes the anxiety of repeating complex histories to automated systems. We organise your cover to evolve alongside your collection, adjusting values and terms as you acquire new pieces or loan items to institutions. This methodical flow of communication mirrors a professional consultation, moving from high-level strategy to granular service descriptions.
Our role as a trusted advisor is to provide bespoke advocacy during the claims process. Should a loss occur, we act as your steady hand, managing the interactions with adjusters and restorers on your behalf. This level of personal accessibility contrasts with the impersonal nature of large, automated corporations. It provides the peace of mind that your cultural and financial investments are secure. To begin this partnership, speak with a specialist broker today to secure your collection with the thoroughness it deserves.
Securing the Future of Your Private Collection
Protecting a masterpiece in 2026 requires more than a simple policy; it demands a strategic partnership. You’ve seen how standard home insurance often falls short with restrictive limits and how specialist features like Agreed Value and Defective Title cover provide the only real safety net for high-value assets. By prioritising environmental controls and professional valuations, you ensure your legacy remains physically and financially intact. The right art collection insurance UK removes the anxiety of the selection process through expert, market-wide guidance.
As an independent and FCA regulated broker, WS Insurance Brokers acts as your shield in a complex market. We provide access to the entire UK specialist insurance market, ensuring you receive unbiased advice tailored to your specific needs. Our dedicated claims advocacy means we’re a steady hand when you need us most. We’re committed to eliminating doubt at every stage of your journey and ensuring your policy wording is as precise as your collection is unique.
Request a Bespoke Art Insurance Consultation today to secure your masterpieces for generations to come. Your collection is a testament to your vision, and it deserves the highest standard of professional protection.
Frequently Asked Questions
Is my art covered under the contents section of my home insurance policy?
Most standard home policies provide basic contents cover, but they frequently impose restrictive single-item limits. These limits often range from £2,500 to £5,000, which is insufficient for many masterpieces. A specialist policy avoids this trap by allowing you to declare each item’s full worth. This removes the risk of underinsurance and ensures that your settlement reflects the true financial value of your assets rather than being capped by a generic household limit.
Do I need to inform my insurer every time I buy a new piece of art?
Active collectors don’t necessarily need to call their broker immediately after every purchase if their policy includes “New Acquisitions” cover. This feature typically provides a 60-day grace period for newly acquired works, often covering up to 25% of the total sum insured. It’s essential to declare the new piece within this timeframe to maintain continuous protection and ensure your art collection insurance UK reflects the increased value of your portfolio.
How often should I have my art collection valued for insurance purposes?
We recommend updating your professional valuations at least every three years to keep pace with the 2026 market. Relying on an old purchase price or a five-year-old appraisal creates a significant risk of underinsurance. Frequent reviews ensure that your “Agreed Value” remains accurate. This proactive approach eliminates doubt during the claims process, as the insurer has already accepted the documented market value provided by a RICS-qualified specialist.
Does art insurance cover pieces whilst they are in transit or on loan?
Yes, specialist policies typically offer worldwide “all-risks” protection, which includes transit and temporary loans to public institutions. Unlike standard policies that may only cover items within your home, specialist art collection insurance UK follows your assets. It provides security during professional packing, shipping, and exhibition. This is vital for collectors who loan pieces to galleries or move works between different properties, as it covers the unique risks of travel.
What happens if a piece of art is damaged but can be restored?
If a piece is restorable, a specialist policy pays for the expert restoration work and the resulting “loss of value”. Most standard insurers only cover the physical repair cost, ignoring the fact that a restored work is often worth less than an untouched original. This depreciation cover is a critical feature for maintaining the financial integrity of your collection. It ensures you are compensated for the permanent drop in market value.
Can I insure a collection that is kept in more than one UK property?
You can certainly insure a collection distributed across multiple UK residences under a single, unified policy. This approach simplifies your administration and ensures that every piece receives the same high level of protection regardless of its location. We assess the physical security and environmental controls at each property to create a tailored risk profile. This methodical structure provides a steady hand in managing the complexities of a multi-site portfolio.
What is defective title insurance and why is it important for art?
Defective title insurance provides financial protection if a work you purchased is later claimed by a previous owner or heir. Provenance disputes can be incredibly complex and expensive to resolve. This cover pays for your legal defence and reimburses the purchase price if you lose the piece. It acts as a shield against the uncertainty of historical ownership issues, providing peace of mind that your financial investment remains secure.
How does an independent insurance broker differ from an online comparison site?
Comparison sites focus on price-driven commodities, whilst an independent broker acts as a trusted advisor with access to the entire specialist market. We provide bespoke placement and dedicated claims advocacy that automated platforms cannot replicate. Our role is to remove the anxiety of the selection process by identifying hidden risks and negotiating tailored terms. We remain fiercely loyal to the client, acting as a steady hand throughout the life of the policy.