
By April 2026, the legal ground beneath your recruitment consultancy will have shifted significantly, making your choice of professional indemnity insurance for recruitment agencies much more than a simple box-ticking exercise. You likely feel the mounting pressure of vetting candidates in a tightening regulatory environment; the anxiety of being held liable for a candidate’s mistake is a burden no business owner should carry alone. It’s understandable to feel confused by the complex contractual requirements demanded by high-value clients, especially with the introduction of joint and several liability for umbrella companies on 6 April 2026.
We’re here to help you turn that uncertainty into a strategic advantage. This guide will show you how to shield your agency from negligence claims and contractual disputes using bespoke cover that fits your specific needs. You’ll gain a clear understanding of vicarious liability and learn how to satisfy even the most stringent contract requirements. We will walk through the essential steps to secure your firm’s future, ensuring you have the robust legal defence and peace of mind necessary to thrive in this evolving market.
Key Takeaways
- Understand why blue-chip clients now view professional indemnity insurance for recruitment agencies as a vital contractual prerequisite for high-value partnerships.
- Identify how this cover shields your consultancy from the crippling legal costs associated with defending professional negligence claims, even when allegations are baseless.
- Examine real-world scenarios where vetting oversights led to significant breach of contract disputes and learn the protective measures to avoid similar pitfalls.
- Determine the most suitable indemnity limits for your specific turnover and client base whilst clarifying the necessity of vicarious liability protection.
- Learn how a bespoke risk assessment from an independent broker provides access to a broader range of insurers than restricted, automated online platforms.
The Evolving Risk Landscape for UK Recruitment Agencies in 2026
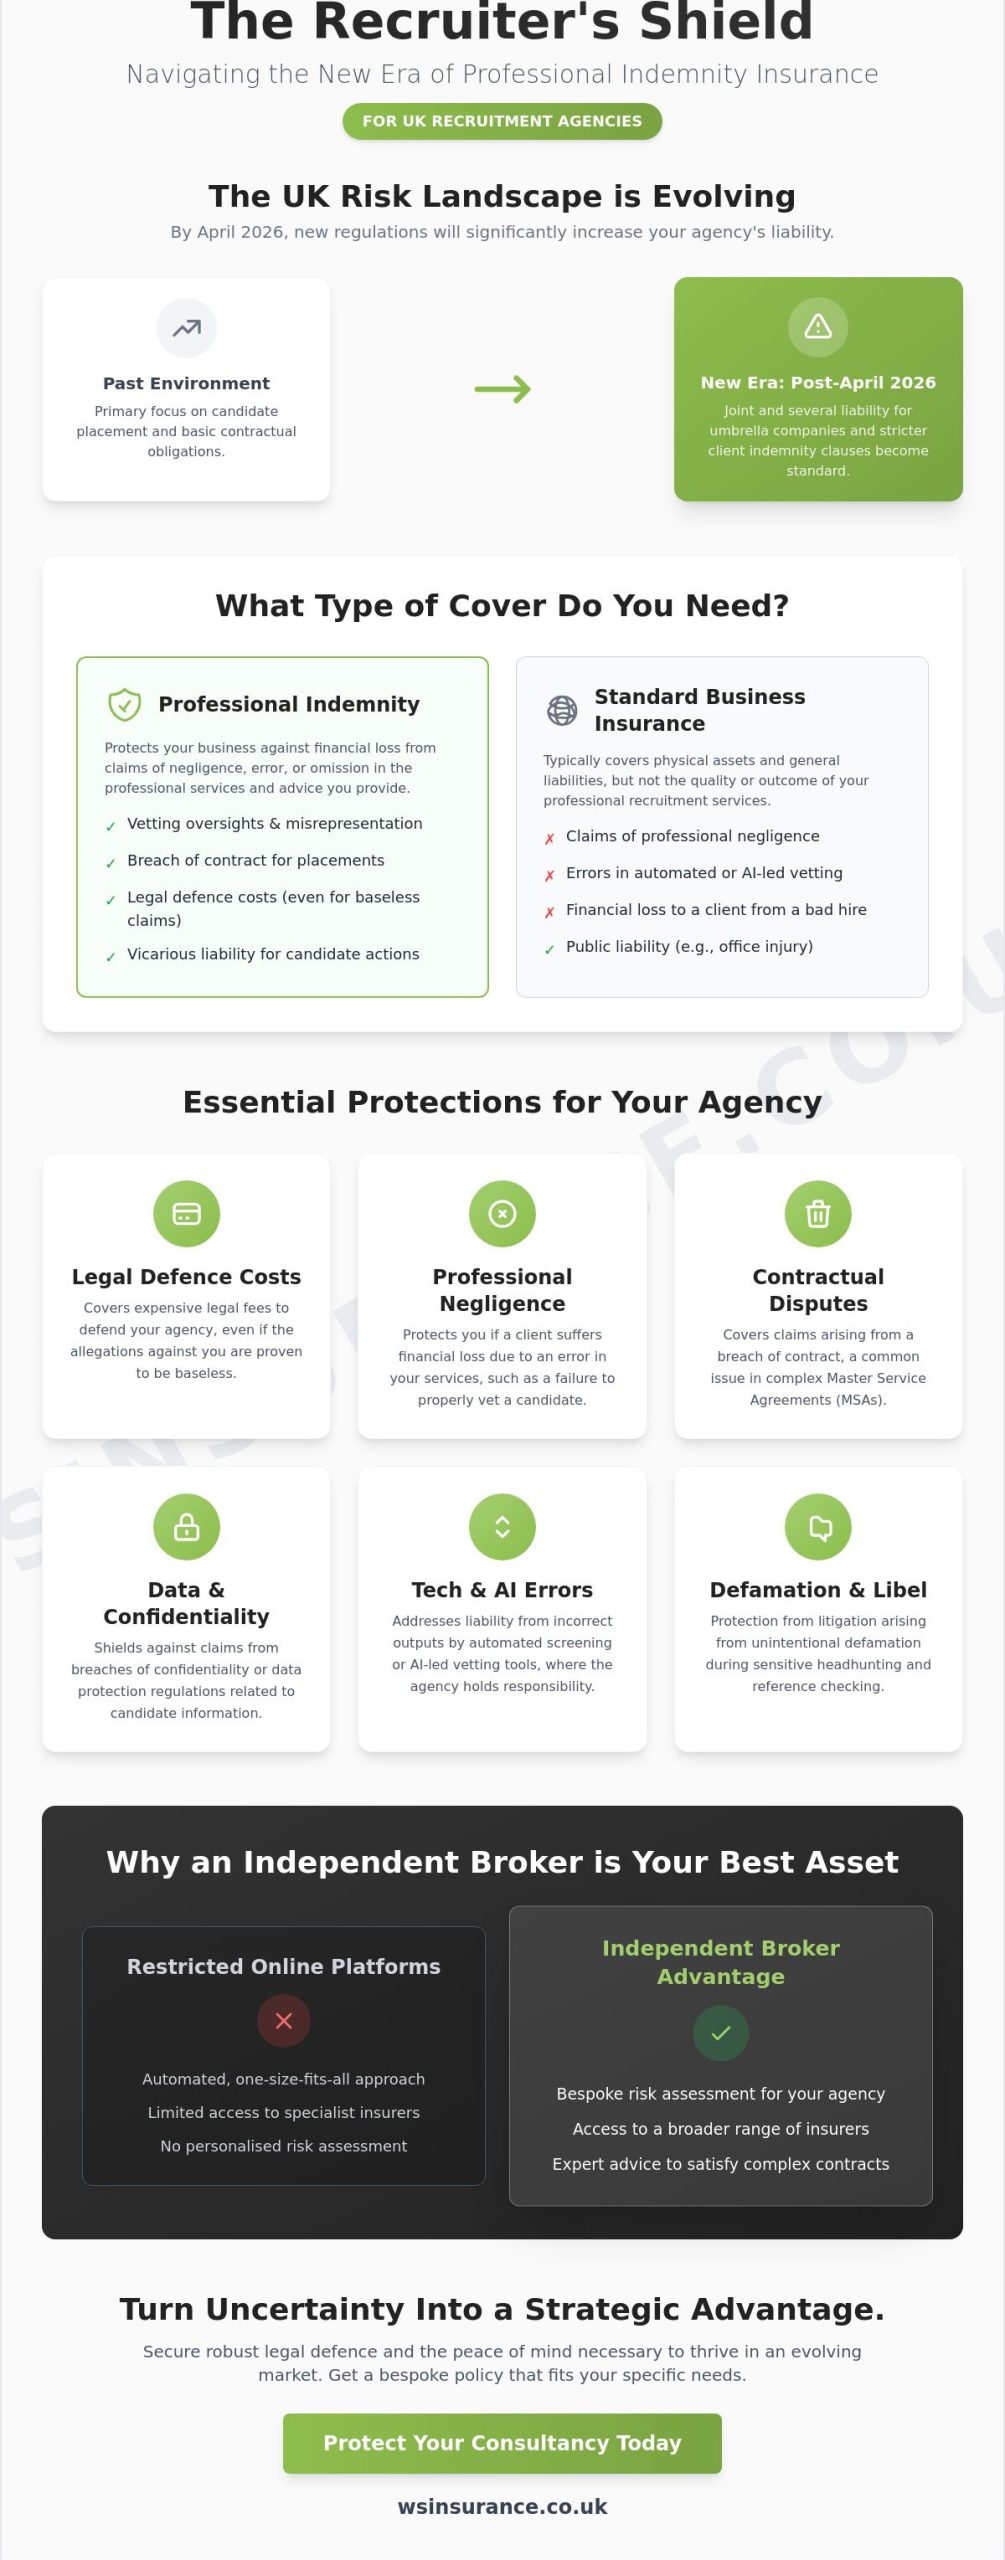
The UK recruitment sector entered a period of profound transformation in April 2026. With the implementation of the Employment Rights Bill and new joint liability rules for umbrella companies, the risks you face daily have become more intricate. It’s no longer just about finding the right candidate; it’s about managing a web of legal responsibilities that extend far beyond the initial placement. In this environment, professional indemnity insurance for recruitment agencies serves as a critical shield, protecting your consultancy from the financial fallout of professional oversights.
Blue-chip clients and large-scale public sector frameworks now treat high-level cover as a non-negotiable entry requirement. They recognise that Professional liability insurance is the only way to ensure an agency can survive a significant negligence claim. These organisations often demand evidence of cover before even beginning the onboarding process. This isn’t just about their safety; it’s a test of your agency’s professional standing and operational maturity.
While many directors confuse this protection with general business insurance, the two serve very different purposes. Standard commercial policies typically cover physical assets or public injuries, whereas professional indemnity focuses specifically on the advice you provide and the service of candidate selection. As digital-first recruitment becomes the norm, the risk of technical errors in automated screening or AI-led vetting has increased. If an AI tool produces an incorrect output during candidate selection, the responsibility typically rests with the agency, creating liabilities that traditional policies simply aren’t designed to handle.
The Definition of Professional Error in Recruitment
Errors in this sector are rarely malicious but can be devastatingly expensive. A primary risk involves the failure to properly vet or check the references of a candidate who later causes a loss for the client. You might also face claims regarding breaches of confidentiality or data protection regulations, especially with the 2026 emphasis on worker data rights. Additionally, unintentional defamation or libel during the sensitive headhunting process can lead to litigation that threatens your agency’s financial stability.
Contractual Compliance and Your Reputation
Modern Master Service Agreements (MSAs) are frequently loaded with stringent indemnity clauses that require specific levels of cover. If you cannot satisfy these requirements, you’ll find your agency excluded from lucrative Preferred Supplier Lists (PSLs). Beyond the immediate loss of revenue, a single negligence claim can tarnish your brand value for years. Maintaining robust professional indemnity insurance for recruitment agencies ensures that if a dispute arises, you have the resources to defend your reputation without draining your working capital.
Decoding Professional Indemnity: Essential Protections for Recruiters
Professional indemnity insurance for recruitment agencies provides protection against financial loss arising from professional advice or services. This fundamental definition serves as the cornerstone of your agency’s risk management strategy. Whilst your team strives for precision in every placement, the reality of the 2026 talent market is that even a minor oversight in candidate vetting can lead to a significant financial demand from a dissatisfied client. Following the UK government rules for employment agencies is essential for compliance, but insurance is what protects your bank balance when those rules are tested in court.
One of the most reassuring features of a high-quality policy is the coverage for legal defence costs. These expenses often spiral quickly; even if an allegation is entirely baseless, the cost of hiring a specialist solicitor to defend your reputation can be crippling for a growing consultancy. Your policy acts as a steady hand, ensuring that both the legal fees and any subsequent awards of damages or settlements are managed by professionals. This allows you to focus on your core business without the constant anxiety of a potential legal bill looming over your operations.
When selecting your cover, it’s vital to understand the difference between “Any One Claim” and “Aggregate” limits of indemnity. An “Any One Claim” structure is generally the preferred choice for recruitment firms because it provides the full limit of cover for every individual claim made during the policy year. In contrast, an “Aggregate” limit is a total pot that diminishes with every claim. Choosing the right structure removes the uncertainty of whether you’ll have enough protection left if multiple issues arise. If you’re concerned about how your current policy is structured, you can consult an expert advisor to ensure your protection is truly robust.
Key Policy Extensions for Agencies
Bespoke professional indemnity insurance for recruitment agencies often includes mitigation costs, which allow you to spend money to rectify a professional error before it escalates into a formal claim. This proactive labor can often save a client relationship while preventing a larger loss. Other essential extensions include court attendance compensation for your directors and protection against the loss of physical or digital documents, covering the often-overlooked expenses of data recovery.
Retroactive Cover: Protecting Your Past
Professional indemnity operates on a “claims-made” basis, which means the policy active at the time a claim is notified handles the matter, regardless of when the work was originally done. To ensure your past placements remain protected, your policy must include retroactive cover. You must never let your insurance lapse; even a small gap in cover can leave years of previous work entirely uninsured, creating a vulnerability that is difficult and expensive to fix later.
Case Study: Navigating a Breach of Contract and Negligence Claim
A specialist recruitment agency recently faced a catastrophic challenge after placing a candidate into a senior financial director role for a high-growth technology firm. The agency’s consultant, under pressure to meet a tight deadline, failed to conduct a formal verification of the candidate’s professional accounting qualifications, relying instead on a well-presented CV and a persuasive interview. This oversight proved to be a pivotal error. Six months into the role, the candidate made a series of significant errors in the client’s tax structuring and financial reporting, resulting in a multi-million pound loss for the employer. When the lack of qualification was discovered, the client immediately issued a claim for professional negligence and breach of contract against the agency.
Whilst UK law on compulsory insurance for employers mandates that agencies carry Employers’ Liability cover to protect their own staff, it is professional indemnity insurance for recruitment agencies that serves as the primary defence in these complex contractual disputes. In this instance, the agency was held liable for the financial consequences of their vetting failure. Without a robust policy in place, the sheer scale of the legal fees and the eventual settlement would have likely forced the consultancy into liquidation.
The Legal Defence Strategy
Upon notification of the claim, the insurer immediately appointed a panel of specialist solicitors who understood the nuances of the recruitment sector. This expert team took over the complex task of managing the dispute, which removed the immediate administrative burden from the agency’s directors. Throughout the process, the agency’s independent broker acted as a vital advocate, ensuring the insurer remained responsive and that the agency’s reputation remained a priority. This proactive labor allowed the agency to maintain a professional dialogue with the client, preventing a complete breakdown in the relationship whilst the legal particulars were being debated.
Financial Impact and Resolution
The total legal defence costs exceeded £150,000, a sum that the insurer paid directly, ensuring the agency’s operational cash flow remained untouched. After a period of negotiation, a settlement was reached that reflected the agency’s degree of responsibility for the client’s financial loss. The indemnity policy covered the multi-million pound settlement in full, minus the policy excess. This outcome allowed the agency to continue trading with its capital intact. Following the resolution, the agency worked with their broker to refine their vetting procedures, implementing a mandatory “double-check” system for all senior-level professional qualifications to ensure such an error could never happen again.
Determining Your Indemnity Limits and Navigating Vicarious Liability
Selecting an appropriate limit for your professional indemnity insurance for recruitment agencies shouldn’t be a matter of guesswork. It requires a clinical assessment of your largest contracts, your annual turnover, and the specific sectors you serve. Whilst a £1 million limit remains the entry-level standard for many startups, we’ve seen a clear shift in 2026 toward £5 million and even £10 million requirements. This is particularly true for agencies working with blue-chip clients or government frameworks where the potential for financial loss is magnified by the scale of the operations involved.
Your risk profile also changes significantly depending on whether you focus on permanent placements or temporary staffing. Permanent placement risks are generally centred on vetting and representation errors. Temporary staffing, however, introduces the complex challenge of vicarious liability, where you may be held responsible for the physical or financial actions of the workers you provide. To ensure total security, it’s often wise to consider integrating PI with public liability insurance, creating a seamless blanket of protection that covers both professional errors and on-site accidents.
The Vicarious Liability Challenge
Drivers Negligence and Specialist Extensions
Niche sectors require specialised language within the policy document. For agencies placing HGV or commercial drivers, a “Drivers Negligence” extension is essential to cover damage to the client’s vehicles. Similarly, healthcare and construction agencies face unique professional risks that require tailored wording. Understanding how the employers liability insurance cost factors into your overall budget is important, but the precision of your PI extensions is what truly protects your long-term solvency. If you’re unsure whether your current policy covers these specialist risks, you should contact us for a thorough policy audit to identify any hidden gaps.
Why an Independent Broker is Your Best Asset for Recruitment PI
In a market where many providers offer a single, restricted product, the value of an independent broker cannot be overstated. We don’t just sell a policy; we act as your expert guide through a complex insurance landscape. By accessing a broad panel of UK insurers, we ensure your professional indemnity insurance for recruitment agencies isn’t a generic template but a precise fit for your consultancy’s unique risks. Automated online forms often fail to capture the nuances of your business, whereas our proactive labour identifies the specific vulnerabilities that algorithms miss.
Having a dedicated expert in your corner is most vital when a claim arises. As we explored in our case study, the pressure of a multi-million pound dispute is immense. We provide the steady hand you need, advocating for your interests and ensuring the insurer meets their obligations. Our goal is to create a cohesive protection package. For instance, if you specialise in the building sector, we can integrate your PI with construction site insurance to ensure no gaps remain between your professional advice and on-site activities.
Removing Uncertainty from the Selection Process
We pride ourselves on translating clinical policy wordings into clear, actionable advice. By understanding your specific agency behaviour and your favourite sectors, we can tailor your cover to match your real-world operations. This authoritative review removes the anxiety of the unknown, giving you the security to pursue high-value contracts with complete confidence. We focus on the long-term security of your consultancy, acting as a shield between you and the complexities of the insurance market.
Cost-Effective Protection without Compromise
Securing competitive premiums is a natural result of our long-standing relationships with leading UK insurers. We look beyond the headline price to identify hidden exclusions that often plague cheap, off-the-shelf policies. This pragmatic approach ensures you don’t pay for unnecessary extras whilst maintaining the robust protection your agency deserves. Our independence means we’re fiercely loyal to you rather than the insurance companies. We invite you to engage with our recruitment specialists for a no-obligation consultation to ensure your consultancy is shielded for the years ahead.
Secure Your Consultancy’s Future in a Changing Market
The 2026 regulatory landscape demands a more diligent approach to risk management than ever before. By understanding the nuances of vicarious liability and ensuring your indemnity limits align with modern contract requirements, you position your agency for sustainable growth. Securing the right professional indemnity insurance for recruitment agencies is no longer just a compliance task; it’s a vital strategy for protecting your brand and your bottom line from the financial impact of professional negligence. Your ability to satisfy high-value client requirements whilst maintaining operational security is what will distinguish your consultancy in a competitive talent market.
We provide the clinical precision and steady hand needed to navigate these complexities with confidence. As an independent broker authorised and regulated by the Financial Conduct Authority, we offer access to a wide panel of leading UK insurers and provide dedicated claims advocacy if a dispute arises. You don’t have to face these market shifts alone. Request a bespoke recruitment insurance review from our expert brokers today and gain the clarity you need to move forward securely. We look forward to helping you build a more resilient consultancy.
Frequently Asked Questions
Is professional indemnity insurance a legal requirement for recruitment agencies?
Professional indemnity is not a legal requirement for recruitment agencies in the UK, unlike Employers’ Liability insurance which is mandatory if you have one or more employees. However, almost all commercial clients and public sector frameworks will contractually insist on it before you can begin placing candidates. It serves as a vital badge of professional standing and is essential for satisfying the stringent requirements of modern Master Service Agreements.
Does recruitment PI cover the mistakes made by candidates I place?
Standard professional indemnity insurance for recruitment agencies typically covers your agency’s internal errors, such as a failure to vet a candidate correctly or check their qualifications. To protect against the actual mistakes made by temporary workers or contractors whilst on-site, you must ensure your policy includes a vicarious liability extension. This specific addition removes the uncertainty regarding who is responsible for a candidate’s professional negligence during their assignment.
What is the difference between professional indemnity and public liability for recruiters?
Professional indemnity addresses financial losses resulting from your professional advice, vetting services, or candidate selection. In contrast, public liability covers physical risks, such as a candidate or visitor being injured at your premises or a temporary worker accidentally damaging a client’s property. Combining these ensures a cohesive shield that protects your consultancy against both professional errors and physical accidents.
How much does professional indemnity insurance for recruitment agencies cost?
The premium for this cover is calculated based on several factors, including your annual turnover, the number of staff you place, and the specific sectors you serve. Agencies placing senior financial executives or medical professionals may face different risk profiles than those in high-volume industrial sectors. We provide bespoke assessments to ensure you receive a competitive rate that reflects your actual exposure without paying for unnecessary extras.
What is retroactive cover and why does my agency need it?
Retroactive cover protects your agency against claims arising from work performed before your current policy period began. Because professional indemnity is written on a “claims-made” basis, you need this extension to ensure that past placements remain covered if an error is discovered months or years later. It eliminates the danger of a coverage gap when you switch insurers or renew your protection, providing long-term security for your previous work.
Can I get cover if I am a self-employed recruitment consultant?
Yes, self-employed recruitment consultants can and should secure their own professional indemnity cover. Even as a solo operator, you are still liable for the advice you provide and the vetting you perform on behalf of your clients. Having your own policy provides the same level of legal defence and financial protection as a larger agency, ensuring your personal assets aren’t at risk from a professional dispute.
What happens if I change my insurance provider mid-contract?
You can change your insurance provider at any time, but it’s vital to ensure there is no gap in your cover during the transition. When moving between insurers, your new broker must verify that the retroactive date on the new policy matches your previous start date. This diligent approach ensures that your agency remains protected for all past placements without any interruption in your legal defence or indemnity limits.
Does my policy cover claims for breach of data protection or GDPR?
Many modern policies for professional indemnity insurance for recruitment agencies include protection against unintentional breaches of data protection and GDPR regulations. This is particularly relevant for recruitment firms that handle sensitive candidate information and CVs daily. If a data breach occurs, the policy can help cover the costs of legal defence and managing the subsequent fallout, providing peace of mind in an increasingly digital-first industry.